










Emmforce US programme lifts OEM share to 41% in H1 FY27
Key highlights
- Emmforce’s OEM revenue share increased to 41% in H1 FY27 from 7% in FY26.
- The Rs 470 crore US programme is expected to contribute about Rs 60 crore in FY27.
- Consolidated H1 FY27 revenue rose 73% to Rs 92.5 crore.
- September receivables were Rs 63 crore, including about Rs 40 crore from the US customer.
powered by IRIS
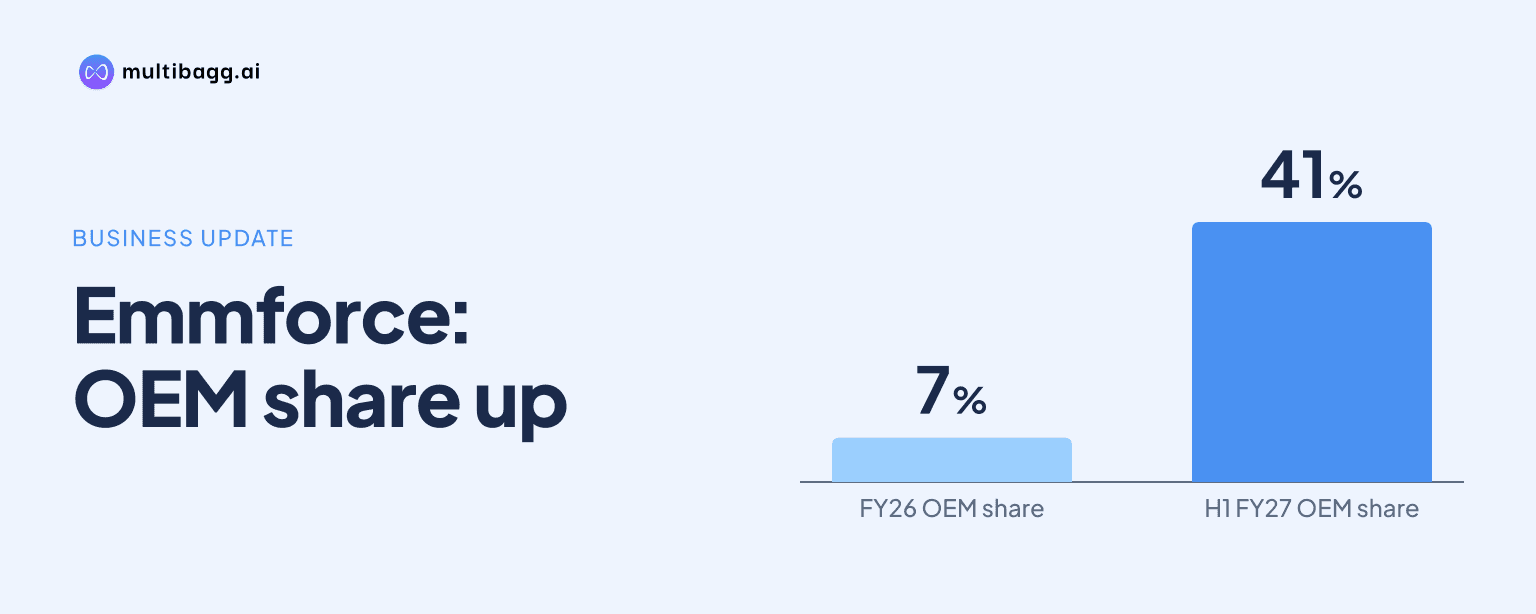
In H1 FY27, Emmforce Autotech Limited lifted original equipment manufacturer, or OEM, revenue share to 41% from 7% in FY26 as its Rs 470 crore US programme entered full-speed operation. Emmforce expects the programme to contribute about Rs 60 crore in FY27, alongside 73% growth in consolidated H1 revenue to Rs 92.5 crore.
Know Emmforce Autotech inside out
Results, valuation, peers and who's buying, in one view.
What drove Emmforce’s OEM revenue mix shift?
Emmforce’s OEM mix shifted because its Rs 470 crore US programme moved into active production, taking OEM revenue to 41% of H1 FY27 revenue from 7% in FY26. Management said the programme was running at full speed and should generate about Rs 60 crore in FY27, making it the stated driver of the 34-percentage-point change in sales mix.
The sales-mix change occurred alongside higher reported revenue and profit. Consolidated revenue rose to Rs 92.5 crore in H1 FY27 from Rs 54 crore a year earlier, while consolidated earnings before interest, tax, depreciation and amortisation, or EBITDA, increased to Rs 16 crore from Rs 11 crore. Consolidated profit after tax, or PAT, rose to about Rs 6 crore from about Rs 4 crore.
The non-OEM business also remained in the sales base. Responding to an analyst who questioned whether H1 growth was entirely OEM-led, management said its existing business was growing at about 15% to 20%, although the company had focused on adding OEM customers. Management also said the main new programme had generated about Rs 6 crore of sales by the end of FY26, so it was not starting from zero in FY27.
How has the US programme affected Emmforce’s cash cycle?
The US programme increased working-capital requirements because Emmforce must hold six to eight weeks of stock in a US warehouse, with about two months of transit and a further two-month payment cycle. Management described the combined cycle as roughly six months, a requirement tied to serving the US customer rather than a change in the company’s stated revenue target of Rs 60 crore for FY27.
Receivables rose to Rs 63 crore in September from Rs 34 crore in March, and management said about Rs 40 crore of the September balance related to the US customer. Operating cash flow was negative by Rs 5.9 crore in H1 FY27, which management attributed mainly to working capital and the initial inventory build for the new programme.
Management expects receivables to decline to around Rs 50 crore by the end of FY27 as the initial stock build normalises. This target is material because the US programme’s sales contribution is already reflected in the 41% OEM mix, while cash conversion depends on warehouse stock, goods in transit and the two-month customer payment period.
Got a follow-up? Ask IRIS
What further OEM orders could support Emmforce’s FY28 growth?
Emmforce has a separate long-term US OEM order worth about Rs 10.5 crore annually, with Production Part Approval Process, or PPAP, samples submitted to the customer. Management expects production to begin in the next quarter and said hydraulic gear-pump shipments should start in Q4, subject to the customer’s programme timetable.
Two additional US customers were testing Emmforce parts during the H1 FY27 call. Management said these opportunities could together add about Rs 10 crore a year and expected a first order in January 2027 after testing is completed. Those potential orders are distinct from the current programme’s expected Rs 60 crore FY27 contribution and remain conditional on testing and purchase orders.
Management retained FY27 revenue guidance of Rs 165 crore for Emmforce and outlined about Rs 195 crore for FY28. In response to an analyst’s calculation, management agreed that about Rs 20 crore of additional OEM business could be included in the FY28 estimate. It also said it expected some European revenue in FY28 after participating in a September exhibition, but did not disclose a European order value.
Can Emmforce improve margins as OEM sales expand?
Emmforce expects standalone EBITDA margin to return to its 20% to 22% range after reporting about 19.5% in H1 FY27. Management said it had absorbed higher costs for raw materials, consumables, power, gas and ocean freight during the half year rather than immediately seeking price revisions from overseas customers.
Management said freight rates had begun to fall and planned to seek customer price revisions effective from 1 December, with some customers potentially responding around 15 December. It did not quantify the proposed increases. For OEM contracts, management said input-cost indexing mechanisms exist and would be discussed after customers had started using the newly supplied parts.
Consolidated margins also reflect losses at Emmforce Mobility, the agriculture subsidiary. The unit recorded H1 FY27 revenue of Rs 14.5 crore, including Rs 8.6 crore of external sales, and a loss of Rs 2.8 crore. Management linked the outcome to two months of labour unrest at TAFE and inventory of blades held by TAFE’s previous supplier.
For FY27, management reduced consolidated revenue guidance to Rs 185 crore from Rs 195 crore after cutting Emmforce Mobility’s estimate to Rs 20 crore from Rs 30 crore. It expects Emmforce Mobility to have no cash loss in H2 FY27, but said the subsidiary would still lower consolidated margin for the full year. Management guided for standalone PAT of about Rs 18 crore and consolidated PAT of about Rs 14 crore.
Conclusion
Emmforce’s rise in OEM revenue share to 41% in H1 FY27 from 7% in FY26 reflects the operational ramp of its Rs 470 crore US programme. The programme supported consolidated revenue of Rs 92.5 crore, but it also drove receivables to Rs 63 crore and contributed to negative operating cash flow of Rs 5.9 crore as inventory, transit and payment requirements expanded.
The next disclosed milestones are price revisions planned from 1 December, the target to reduce receivables to around Rs 50 crore by FY27-end, and the expected next-quarter production start for the Rs 10.5 crore annual US OEM order. Management also expects the first order from two testing US customers in January 2027, which could determine whether the additional Rs 10 crore annual opportunity contributes to FY28 growth.