










Enviro Infra FY26 growth slowed as capital returns fell
Key highlights
- Enviro Infra's FY26 revenue from operations rose 7.5% to Rs 1,145.6 crore.
- FY26 EBITDA rose 3.4% to Rs 276.8 crore, while EBITDA margin declined to 24.2%.
- Enviro Infra's ROCE fell to 17.2% in FY26 from 22.6% in FY25.
- FY26 net worth reached Rs 1,232.7 crore and debt increased to Rs 422.3 crore.
powered by IRIS
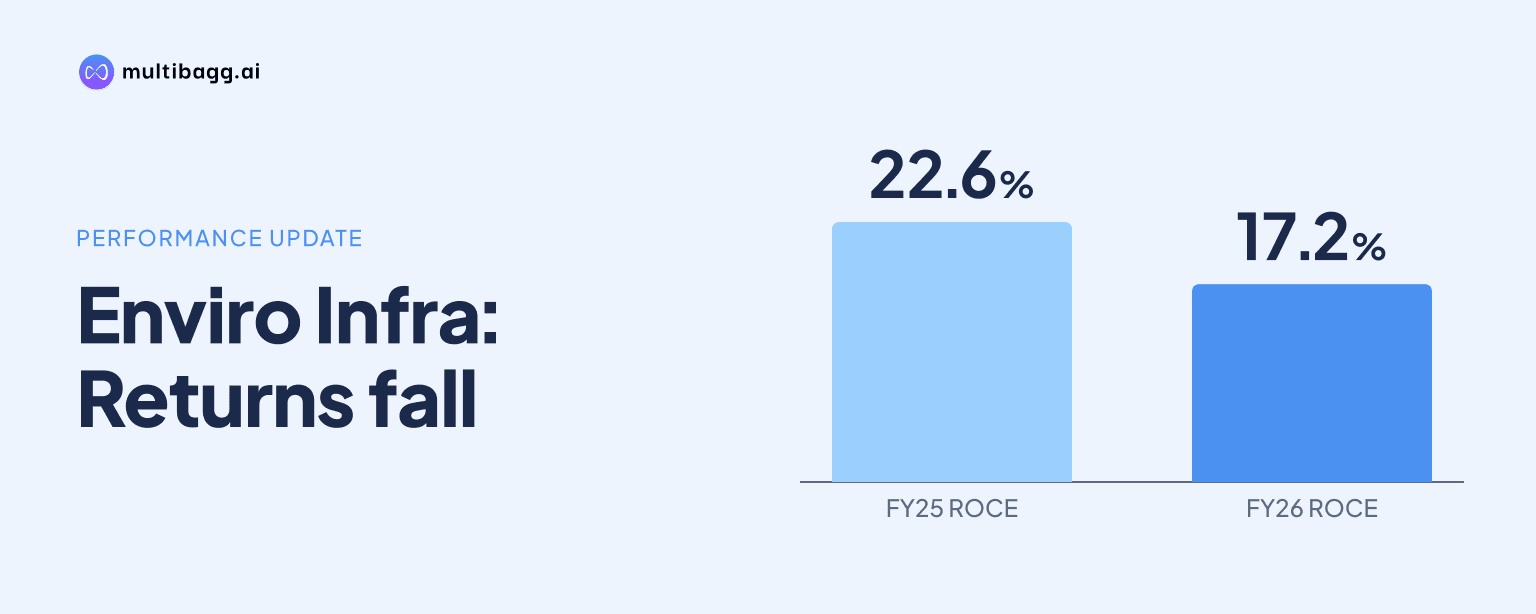
Enviro Infra Engineers Limited reported FY26 revenue from operations of Rs 1,145.6 crore, up 7.5% from FY25, while EBITDA rose 3.4% to Rs 276.8 crore and return on capital employed fell to 17.2% from 22.6%. Return on equity also declined to 15.3% as net worth and debt increased.
Know Enviro Infra Engineers inside out
Results, valuation, peers and who's buying, in one view.
How much did Enviro Infra grow in FY26?
Enviro Infra grew revenue and profit in FY26, but at a slower rate than in FY25. Revenue from operations increased from Rs 1,066.1 crore in FY25 to Rs 1,145.6 crore in FY26, an increase of Rs 79.5 crore or 7.5%. EBITDA, or earnings before interest, tax, depreciation and amortisation, increased from Rs 267.8 crore to Rs 276.8 crore, while profit after tax rose from Rs 177.1 crore to Rs 188.4 crore.
The FY26 outcome contrasts with the prior year’s larger expansion. Revenue increased by Rs 337.2 crore between FY24 and FY25, compared with Rs 79.5 crore in FY26. EBITDA rose by Rs 101.3 crore in FY25 but by Rs 9 crore in FY26, while profit after tax increased by Rs 70.6 crore in FY25 and Rs 11.3 crore in FY26. The presentation therefore shows continued annual growth, but a reduced absolute addition across all three reported profit measures.
Did Enviro Infra's margins change in FY26?
Enviro Infra’s EBITDA margin fell to 24.2% in FY26 from 25.1% in FY25, while its profit-after-tax margin declined to 15.9% from 16.3%. The 0.9 percentage-point EBITDA-margin movement accompanied the Rs 9 crore increase in EBITDA on Rs 79.5 crore of additional revenue. The 0.4 percentage-point decline in the profit-after-tax margin occurred even as reported profit after tax rose by Rs 11.3 crore.
FY26 margins were also below the levels reported in FY23, though they remained above FY24. EBITDA margin was 25% in FY23, declined to 22.8% in FY24, recovered to 25.1% in FY25 and then moved to 24.2% in FY26. Profit-after-tax margin followed a similar course, moving from 16.8% in FY23 to 14.4% in FY24, 16.3% in FY25 and 15.9% in FY26. These figures show that FY26 revenue growth did not translate into a higher annual margin.
The subsequent quarterly numbers disclosed in the presentation show further margin movement. In Q2 FY27, Enviro Infra reported revenue from operations of Rs 363.8 crore, up 60.01% year on year, but EBITDA margin was 20.58%, compared with 28.56% in Q2 FY26. Profit after tax was Rs 39.5 crore in Q2 FY27, down 20.22% from Rs 49.5 crore, and the profit-after-tax margin was 10.62%, versus 20.51% a year earlier.
Got a follow-up? Ask IRIS
How did Enviro Infra's return ratios change?
Enviro Infra’s return on capital employed, or ROCE, declined to 17.2% in FY26 from 22.6% in FY25, while return on equity, or ROE, fell to 15.3% from 17.8%. ROCE declined in each reported year, from 44.3% in FY23 to 32.3% in FY24, 22.6% in FY25 and 17.2% in FY26. ROE moved from 44.7% in FY23 to 36.4% in FY24, 17.8% in FY25 and 15.3% in FY26.
The reported capital base expanded substantially over the same period. Net worth increased by Rs 238.2 crore in FY26, reaching Rs 1,232.7 crore from Rs 994.5 crore in FY25. Debt increased by Rs 188.2 crore to Rs 422.3 crore from Rs 234.1 crore. Profit after tax, in comparison, rose by Rs 11.3 crore in FY26, so the presentation records declining returns alongside a larger net-worth and debt base; it does not specify a causal explanation for the ratio changes.
What changed in Enviro Infra's revenue mix?
Enviro Infra’s FY26 revenue mix included renewable energy revenue of Rs 129.2 crore, or 11% of total revenue from operations, whereas the FY25 table reported no renewable-energy revenue. Water revenue was Rs 947.9 crore in FY26, representing 83% of the Rs 1,145.6 crore total, compared with Rs 1,023.7 crore or 96% in FY25. The water business remained the largest reported category, but its share of annual revenue fell by 13 percentage points.
The delivery-model split also changed in FY26. Engineering, procurement and construction, or EPC, revenue was Rs 921.4 crore, or 80% of FY26 revenue, down from 87% in FY25. Hybrid annuity model, or HAM, revenue rose to Rs 145.1 crore from Rs 93.2 crore, lifting its share to 13% from 9%. Operations and maintenance revenue was Rs 41.1 crore, or 4%, while annuity revenue was Rs 27.4 crore, or 2%.
By H1 FY27, renewable energy revenue had increased to Rs 203.7 crore, representing 29% of Rs 723 crore in revenue from operations. Management said the core water and wastewater segment accounted for around 71% of consolidated revenue in that half year. The presentation also identifies a Rs 224.19 crore wind EPC order obtained through step-down subsidiary Suyog Urja from Tata Power Renewable Energy Limited, supporting the disclosed expansion of renewable activity.
Conclusion
Enviro Infra’s FY26 figures show that revenue, EBITDA and profit after tax all increased, but growth was much lower than in FY25 and both reported annual margins declined. At the same time, net worth reached Rs 1,232.7 crore and debt reached Rs 422.3 crore, while ROCE and ROE continued their multi-year decline to 17.2% and 15.3%, respectively.
The next disclosed items to watch are execution and revenue mix. Management said it was in advanced stages of completing 60 million litres per day (MLD) sewage treatment plant projects at Mathura, 77 MLD at Yamuna Nagar and 50 MLD at Amritsar, and cited an order book of about Rs 6,778 crore across water infrastructure and renewable energy. Management also said profitability had been affected by project mix and elevated costs, making later margin and return-ratio disclosures relevant to the stated execution plan.