










Ester Industries posts Rs 7.8 crore Q2 profit as EBITDA rises
Key highlights
- Ester Industries reported Rs 7.8 crore consolidated profit after tax in Q2 FY27 versus a Rs 15.8 crore loss in Q2 FY26.
- Ester Industries' Q2 FY27 consolidated EBITDA rose 160.0% to Rs 45.1 crore and margin reached 10.0% from 4.9%.
- Ester Industries' Film revenue increased 39.6% to Rs 414.5 crore while sales volume rose 13.9% to 24,291 MT.
- Ester Industries' Specialty Polymers sales volume fell 38.8% to 711 MT and EBIT margin was 33.9%.
powered by IRIS
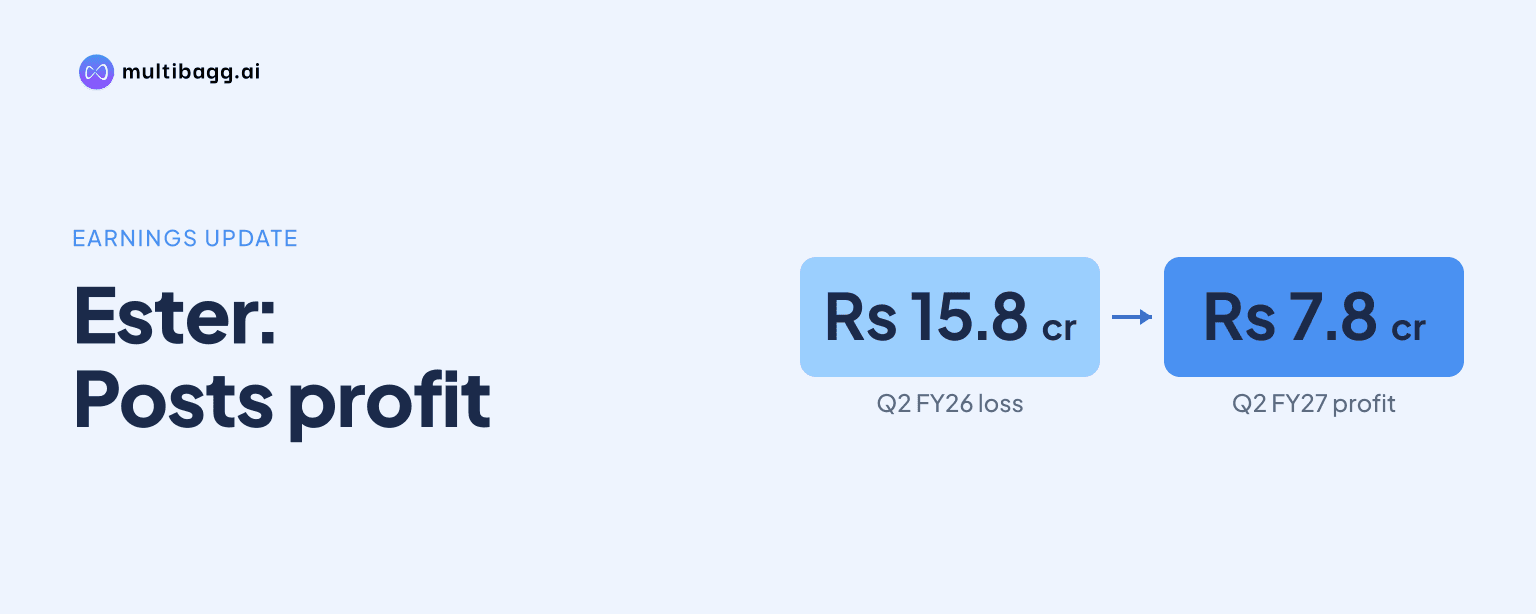
Ester Industries Limited returned to a consolidated Rs 7.8 crore profit in Q2 FY27 from a Rs 15.8 crore loss a year earlier, as earnings before interest, tax, depreciation and amortisation (EBITDA) rose 160.0% to Rs 45.1 crore and its EBITDA margin doubled to 10.0% from 4.9%.
Know Ester Industries inside out
Results, valuation, peers and who's buying, in one view.
How did Ester Industries return to profit in Q2 FY27?
Ester Industries returned to profit as consolidated total income rose 25.7% and EBITDA increased 160.0% in Q2 FY27. Total income reached Rs 449.0 crore, compared with Rs 357.2 crore in Q2 FY26, while EBITDA, including non-operating income, increased by Rs 27.8 crore from Rs 17.3 crore to Rs 45.1 crore. Profit after tax turned positive at Rs 7.8 crore after a Rs 15.8 crore loss in the corresponding quarter.
The first-half figures show that the improvement continued beyond the quarter. In H1 FY27, Ester Industries reported consolidated total income of Rs 891.0 crore, up 26.5% from Rs 704.1 crore, and EBITDA of Rs 104.0 crore, up 124.6% from Rs 46.3 crore. H1 profit after tax was Rs 26.5 crore, against a Rs 22.9 crore loss in H1 FY26.
What drove Ester Industries' margin expansion?
Ester Industries said higher realisations, increased throughput and a favourable product mix lifted its consolidated EBITDA margin by 510 basis points in Q2 FY27. A basis point is one-hundredth of a percentage point. The margin reached 10.0%, compared with 4.9% in Q2 FY26, as value-added products made a larger contribution within the Film segment and realisations improved across the product portfolio.
The standalone result also improved, though by less than the consolidated result on an EBITDA growth basis. Standalone total income increased 38.9% to Rs 365.8 crore in Q2 FY27, while standalone EBITDA rose 103.8% to Rs 28.6 crore from Rs 14.0 crore. Standalone EBITDA margin rose to 7.8% from 5.3%, and profit after tax was Rs 6.1 crore after a Rs 4.8 crore loss a year earlier.
For H1 FY27, consolidated EBITDA margin was 11.7%, versus 6.6% in H1 FY26, also an increase of 510 basis points. That first-half margin was 1.7 percentage points above the Q2 FY27 margin of 10.0%. Ester Industries said the operating environment for biaxially oriented polyethylene terephthalate, or BOPET, films remained stable during Q2 FY27, with US tariff-related disruptions from FY26 largely behind it.
How did Ester Industries' Film business perform?
Ester Industries' Film business increased capacity use, sales volume and revenue during Q2 FY27. Consolidated Film capacity utilisation was 92%, compared with 80% in Q2 FY26, supported by higher production at Ester Industries and Ester Filmtech. Film sales volume rose 13.9% to 24,291 metric tonnes, or MT, from 21,329 MT.
Film revenue rose 39.6% to Rs 414.5 crore from Rs 296.8 crore, outpacing the 13.9% volume increase. Ester Industries attributed the higher per-unit realisations to increases in petrochemical feedstock prices. The 12-percentage-point rise in capacity utilisation and the faster revenue increase were the disclosed operational changes in the segment during the quarter.
Value-added and specialty, or VAS, Film volume increased 25.8% to 6,200 MT from 4,927 MT in Q2 FY26. VAS represented 25.3% of total Film sales volume in Q2 FY27, linking the segment's sales mix to the consolidated margin improvement cited by management. Recycled polyethylene terephthalate, or rPET, volume grew 37.4% to 1,437 MT and rPET revenue increased 51.0% to Rs 18.4 crore.
Got a follow-up? Ask IRIS
What changed in Ester Industries' Specialty Polymers segment?
Ester Industries' Specialty Polymers sales volume declined 38.8% to 711 MT in Q2 FY27 from 1,161 MT in Q2 FY26 because demand eroded for one marquee product. The segment's earnings before interest and tax, or EBIT, margin was 33.9% in Q2 FY27, compared with 37.0% a year earlier. This was a 3.1-percentage-point decline despite the segment retaining a margin above 30%.
Management said its product pipeline and expected customer approval for a new product could partially offset lost Specialty Polymers sales volume and margins after marginal capital expenditure. The announcement did not disclose the amount of capital expenditure, the timing of approval or the potential sales contribution. The reported 711 MT quarterly volume therefore remains the stated measure of current demand pressure in the segment.
The consolidated turnaround occurred while Specialty Polymers volume contracted because the Film segment generated Rs 414.5 crore of Q2 FY27 revenue and increased VAS volume to 6,200 MT. Film capacity utilisation was 92%, whereas Specialty Polymers was affected by demand erosion in one product. The expected customer approval is a management outlook rather than a reported recovery in Q2 FY27.
What risks and project milestones should readers track?
Ester Industries said disruptions to crude-oil supply and price fluctuations caused by the war in West Asia increased shipping costs and extended transit times during Q2 FY27. According to the company, those developments adversely affected the working-capital cycle. It also cited global geopolitical uncertainty as a factor affecting raw-material costs and pricing visibility, despite Q2 FY27 consolidated total income of Rs 449.0 crore.
Ester Industries said work on the ELITe project, targeted for implementation by the last quarter of calendar year 2028, was progressing. Land acquisition is expected to be completed by Q4 FY27. The project has a marketing and offtake agreement with an anchor customer and a letter of intent from a leading global sports and athletic brand for Loop™ PET Fiber Grade resin from the planned Gujarat facility under a multi-year framework.
The company said these arrangements would commit a significant portion of planned ELITe capacity before commercial production, but it did not disclose project cost, capacity, committed volumes or the anchor customer's identity. Ester Industries' stated focus on premium and value-added products, operational efficiency, capacity utilisation and advanced Specialty products provides the framework for its medium- to long-term plans.
Conclusion
Ester Industries' Q2 FY27 result combined a return to Rs 7.8 crore consolidated profit with a 160.0% rise in EBITDA to Rs 45.1 crore and a 510-basis-point margin increase to 10.0%. Higher Film utilisation, a 39.6% increase in Film revenue and greater VAS and rPET volumes supported the improvement, while Specialty Polymers volume fell 38.8% to 711 MT.
Next, Ester Industries expects ELITe land acquisition to conclude in Q4 FY27 and targets project implementation by the last quarter of calendar year 2028. The next disclosed matters to watch are whether a new Specialty Polymers product receives customer approval and whether West Asia-linked freight costs and longer transit times continue to affect working capital.