










Foreign Institutional Investors Lead ₹13,802 Crore Flow Shift
Key highlights
- FIIs recorded ₹13,801.83 crore of net buying on 5 November 2026 in the cited NSE capital-market data.
- DIIs recorded ₹10,107.11 crore of net selling on 5 November 2026.
- The combined FII-DII net flow was positive ₹3,694.72 crore on the cited figures.
- FIIs bought a reported net ₹20,834.04 crore over four sessions between 30 October and 4 November.
powered by IRIS
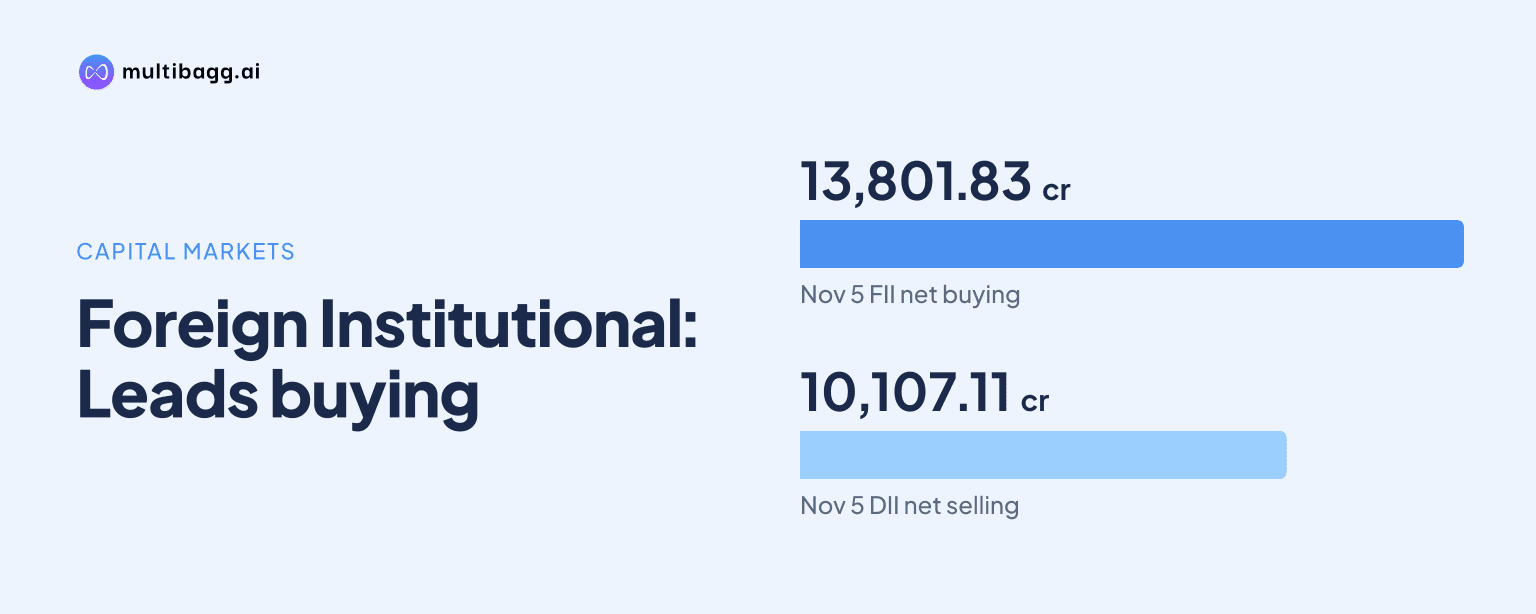
Foreign Institutional Investors led a ₹13,801.83 crore net buying flow on 5 November 2026, while Domestic Institutional Investors recorded ₹10,107.11 crore of net selling in the NSE capital-market snapshot. The opposing trades left a combined institutional net inflow of ₹3,694.72 crore, pointing to foreign buying exceeding domestic profit-booking that day.
What did Foreign Institutional Investors and Domestic Institutional Investors do on November 5?
Foreign Institutional Investors (FIIs) bought ₹29,886.70 crore of shares and sold ₹16,084.87 crore on 5 November, resulting in net purchases of ₹13,801.83 crore. Domestic Institutional Investors (DIIs) bought ₹19,739.19 crore and sold ₹29,846.30 crore, producing net sales of ₹10,107.11 crore.
The figures show a clear divergence in institutional positioning for the session. FIIs were adding more equity exposure than they were reducing, whereas DIIs sold more than they bought. The combined net result remained positive because FII purchases were larger than DII sales. Gross trading values should not be confused with net flows: net value is calculated by subtracting total sales from total purchases.
Why are FIIs buying while DIIs are selling?
FIIs buying while DIIs sell can reflect different investment decisions rather than a single market verdict. The social-media discussion described the domestic sales as profit-booking while foreign investors stepped up purchases, but the data alone does not establish why either group traded.
The pattern follows a four-session run between 30 October and 4 November in which FIIs reportedly bought a net ₹20,834.04 crore in the cash market. DIIs, in contrast, sold a net ₹8,600.79 crore during those four sessions. The reported daily DII net sales were ₹817.51 crore on 30 October, ₹392.20 crore on 2 November, ₹3,678.85 crore on 3 November and ₹3,712.23 crore on 4 November.
This change is notable against October's broader trend. FIIs reportedly ended October with net sales of about ₹45,162 crore, while DIIs purchased ₹62,220 crore. Domestic buying was therefore the larger counterweight during that month, whereas the early-November sequence has featured foreign buying and domestic selling.
Got a follow-up? Ask IRIS
Does the combined institutional flow signal a bullish market?
A positive combined institutional flow signals that purchases exceeded sales across the two groups in the reported session, but it is not a standalone forecast for the market. On 5 November, the combined net inflow was ₹3,694.72 crore based on the NSE capital-market figures provided.
Market direction can also be shaped by global cues, corporate earnings and price action. The context noted that the Nifty closed at a two-month high of 23,961 and the Sensex at 77,301 during the FII buying wave, completing five straight sessions of gains. That backdrop is consistent with stronger near-term demand, but it does not prove that the reported flows alone caused the move.
Retail investors should also distinguish a one-day reading from a sustained trend. The discussion around institutional flows notes that five- to ten-day streaks are more meaningful than an isolated trading session. A market that holds firm during foreign selling may indicate domestic absorption, while a market with neither foreign nor domestic buying support may have a weaker liquidity cushion.
What should investors monitor after this flow reversal?
Investors should monitor whether FII net buying continues over several sessions and whether DII selling persists or returns to net buying. The immediate question is whether the early-November reversal develops into a longer pattern after FIIs had been net sellers in October.
Published snapshots in the discussion also show that figures can differ by data feed and timing. One 5 November data set listed FII net buying of ₹14,974.68 crore and DII net selling of ₹10,444.54 crore, while a 6 November update listed FII net buying of ₹13,749.82 crore and DII net selling of ₹5,968.70 crore. Investors should therefore check the exchange source, market segment and provisional or final status before comparing numbers.
Conclusion
The available data shows a meaningful short-term shift: FIIs were net buyers while DIIs were net sellers, and foreign purchases were large enough to keep the combined institutional flow positive on 5 November. It contrasts with October, when DII buying more than offset a much larger FII outflow over the month.
The next indicator is whether the four-session FII buying run extends and whether DII sales remain profit-booking or reverse into purchases. Investors should track daily net figures alongside the Nifty and Sensex, while noting differences between provisional exchange updates and other reported data sets.