










Greaves MHP Gensets Gain Share With 35% H1 FY27 Expansion
Key highlights
- Greaves’ 160–750 kVA MHP genset portfolio grew 35% in H1 FY27, versus 28% for Energy Solutions.
- Management said the seven-percentage-point MHP growth advantage increased Greaves’ market share in H1 FY27.
- Energy Solutions grew 36% year on year in Q2 FY27, compared with 21% in Q1 FY27.
- Core Business EBITDA margin was 11.5% in Q2 FY27, versus 14.8% a year earlier.
powered by IRIS
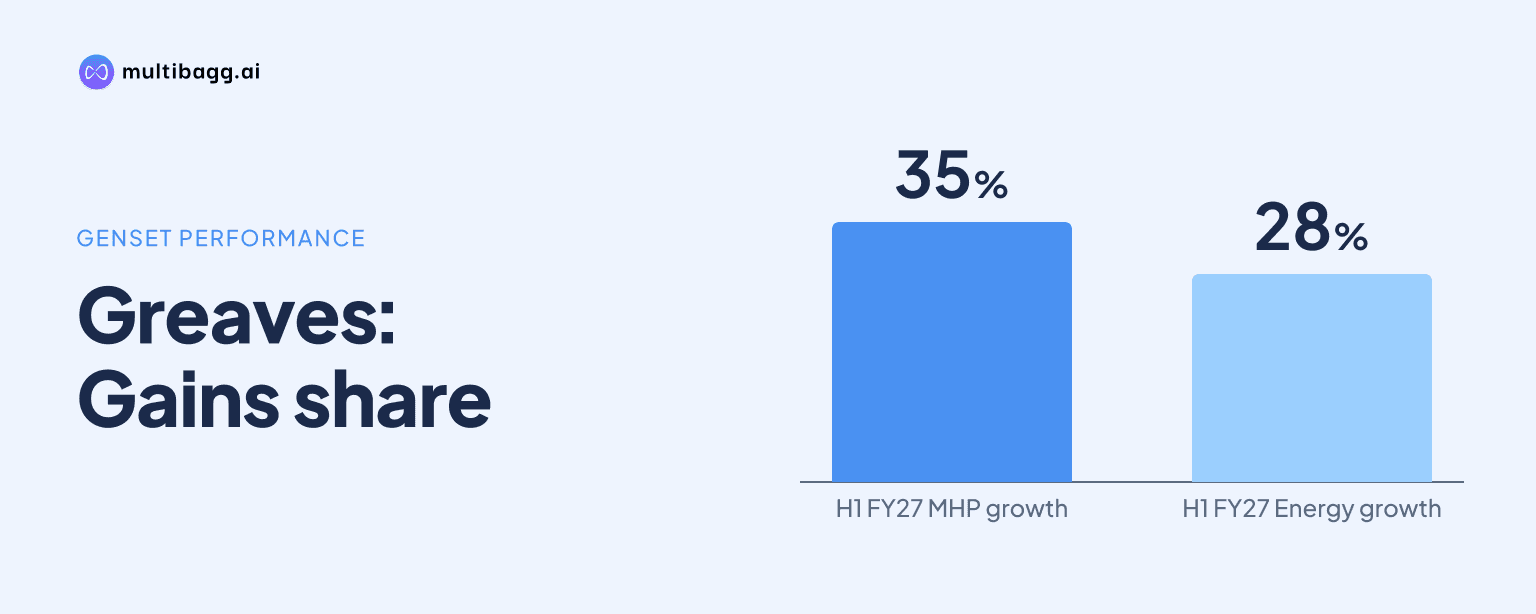
In H1 FY27, Greaves Cotton Limited’s 160–750 kilovolt-ampere, or kVA, medium-horsepower genset portfolio grew 35%, seven percentage points faster than the 28% expansion of Energy Solutions, and management said the outperformance increased Greaves’ market share. The portfolio is a strategic focus under the GREAVES.NEXT plan.
Know Greaves Cotton inside out
Results, valuation, peers and who's buying, in one view.
How fast did Greaves’ MHP gensets grow in H1 FY27?
Greaves’ medium-horsepower, or MHP, genset portfolio grew 35% in H1 FY27, compared with 28% growth for Energy Solutions overall. The MHP range covers gensets rated from 160 kVA to 750 kVA. Management gave these first-half growth rates in response to an analyst’s question on the genset business and said the faster MHP expansion resulted in a rise in market share.
The gap between the two growth rates was seven percentage points, showing that the targeted range expanded faster than its wider business segment. The call did not disclose MHP revenue, unit sales, the total addressable market or Greaves’ market-share percentage before and after the increase. Management’s share-gain statement is therefore the available measure of the portfolio’s competitive progress.
Energy Solutions also accelerated during Q2 FY27, when it grew 36% year on year against 21% in Q1 FY27. Greaves did not report separate Q2 growth for MHP gensets, so the H1 comparison is the direct basis for assessing the portfolio against Energy Solutions. Management cited demand across infrastructure, manufacturing, commercial and industrial applications for the segment’s quarterly growth.
Why is Greaves prioritising the 160–750 kVA range?
Greaves is prioritising the 160–750 kVA range because management describes MHP gensets as an area where it has chosen to strengthen its presence and increase share under GREAVES.NEXT. Managing Director and Group Chief Executive Officer Parag Satpute said Greaves considers the MHP portfolio strong and plans to “double down” on it. The 35% H1 FY27 growth was presented as an outcome of that focus.
Management said its MHP product range is complete from 160 kVA to 750 kVA, including the genset, the broader customer solution and aftermarket support. This means the stated offering extends beyond the equipment itself to service-related support. The transcript does not quantify the number of models, customers or service locations associated with the 160–750 kVA portfolio.
Greaves has also expanded at the upper end of the range through 625 kVA and 650 kVA products launched a couple of quarters before the October 29, 2026 earnings call. Management said these additions were making good progress. For very-high-horsepower applications, Greaves uses a strategic partner for engines while developing some engines internally to provide a broader product programme.
What changed in Greaves Energy Solutions during Q2 FY27?
Greaves’ Energy Solutions growth rose to 36% year on year in Q2 FY27 from 21% in Q1 FY27, a 15-percentage-point acceleration in the reported quarterly growth rate. Management linked Q2 demand to infrastructure, manufacturing, commercial and industrial uses. This quarterly improvement followed the 28% H1 FY27 growth reported for the segment as a whole.
The MHP portfolio’s 35% H1 FY27 increase was faster than Energy Solutions’ 28% rate, but Greaves did not provide industry growth for 160–750 kVA gensets or growth rates for named competitors. It also did not disclose the proportion of Energy Solutions revenue generated by MHP gensets. The evidence available from the call is management’s explicit statement that relative MHP growth lifted Greaves’ share.
Energy Solutions forms part of Greaves’ Core Business, which generated revenue of Rs 1,478 crore in H1 FY27, up 20% from Rs 1,233 crore a year earlier. Core Business includes Energy Solutions, Mobility Solutions and Industrial Solutions, so those figures cannot establish Energy Solutions revenue or MHP genset revenue. Mobility Solutions grew 23% year on year in Q2 FY27, while Industrial Solutions reported 9% like-for-like growth after a portfolio exit.
Got a follow-up? Ask IRIS
Is Greaves expanding its genset business outside India?
Greaves is pursuing exports of gensets, with the Middle East and Africa identified by management as focus markets, although it said the bulk of current genset business remains domestic. During Q2 FY27, Greaves completed and shipped the first batch of enhanced gensets developed for a key Middle Eastern market. Management described that batch as a step in building an international business.
The company said gensets need product enhancements to fit operating conditions in its target export markets. Greaves has set up an entity in the Middle East, is building a sales team there and is developing product-service capability. The call did not identify the destination country, customer, batch size, export revenue or a date for a subsequent shipment.
The export effort accompanies domestic demand across infrastructure, manufacturing, commercial and industrial uses in Q2 FY27. Management’s plan is to sustain Energy Solutions growth and build a larger domestic and international business. It did not provide an export-sales target or a timetable for Africa, so the first Middle East batch is evidence of execution rather than a disclosed contribution to segment revenue.
What is affecting Greaves’ genset profitability?
Greaves’ margins faced input-cost pressure in Q2 FY27 from aluminium, iron, copper and platinum-group metals used in engines and gensets, according to Group Chief Financial Officer Manish Poddar. Management said pricing actions begun during the quarter had started to help, but commodity inflation offset part of the gain. Pricing arrangements in business-to-business and original-equipment-manufacturer sales can operate with a lag.
Core Business earnings before interest, tax, depreciation and amortisation, or EBITDA, margin was 11.5% in Q2 FY27, down from 14.8% a year earlier. Core Business revenue nevertheless rose 24% year on year to Rs 768 crore from Rs 621 crore. The lower margin reflects the mismatch between higher input costs and the timing of price recovery rather than a disclosed Energy Solutions-specific margin.
Management said it expects the full company-wide benefit of pricing actions to be reflected by Q4 FY27 and is also using cost optimisation, value engineering, productivity measures and tighter cost control. Poddar said management remains committed to a 13% to 15% mid- to long-term EBITDA-margin range under GREAVES.NEXT and expects H2 FY27 margins to be better than H1 FY27. These are management expectations, not reported outcomes.
Conclusion
Greaves’ 35% MHP genset growth in H1 FY27, against 28% for Energy Solutions, is the clearest disclosed indicator that its focus on the 160–750 kVA range is producing a market-share gain. The segment’s 36% Q2 FY27 growth, up from 21% in Q1 FY27, also points to stronger momentum across domestic infrastructure, manufacturing, commercial and industrial demand.
The next disclosures to watch are whether the first enhanced-genset batch for the Middle East develops into repeat export business and whether 625 kVA and 650 kVA products add to MHP growth. Management also expects price increases and efficiency measures to show their full company-wide benefit by Q4 FY27, while targeting a 13% to 15% mid- to long-term Core Business EBITDA margin.