










Hindalco expects normalized copper EBITDA of Rs 1,200 crore
Key highlights
- Hindalco reported record copper EBITDA of Rs 1,673 crore in Q2 FY27, up 164% year on year.
- Hindalco expects normalized quarterly copper EBITDA of about Rs 1,200 crore to Rs 1,300 crore.
- Management estimated Rs 350 crore to Rs 400 crore of Q2 FY27 copper EBITDA was not sustainably repeatable.
- Sulphuric-acid realisation was about Rs 16,000 per tonne, versus around Rs 7,000 per tonne a year earlier.
powered by IRIS
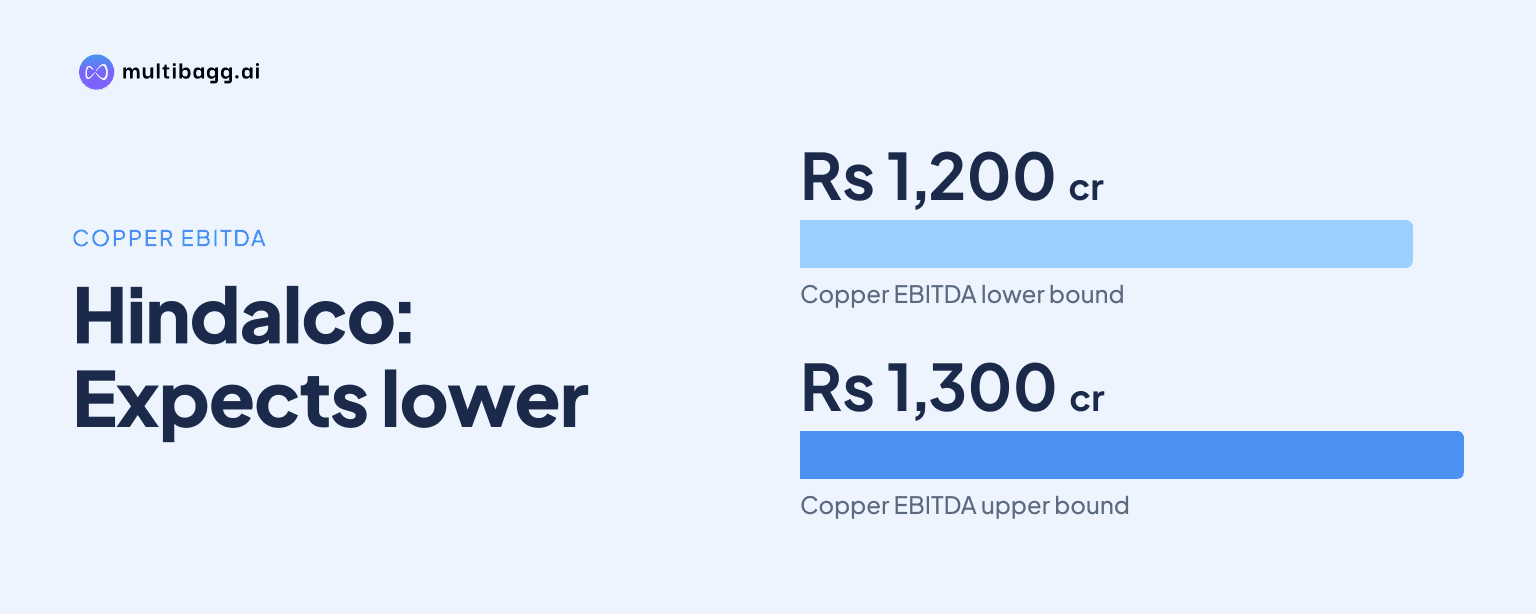
Hindalco Industries Limited expects normalized quarterly copper EBITDA of Rs 1,200 crore to Rs 1,300 crore in coming quarters after reporting a record Rs 1,673 crore in Q2 FY27. Management said roughly Rs 350 crore to Rs 400 crore of the quarter’s copper result came from items it does not regard as sustainably repeatable.
Know Hindalco Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did Hindalco copper EBITDA reach a record in Q2 FY27?
Hindalco’s copper EBITDA reached a record Rs 1,673 crore in Q2 FY27, up 164% year on year, as operating performance, by-product realisations and certain non-recurring gains combined. Metal shipments rose 2% year on year to 116 kilotonnes, while continuous cast rod, or CCR, volumes were stable at 96 kilotonnes. Management also cited healthy domestic demand across its served segments despite elevated London Metal Exchange prices.
The reported result was Rs 373 crore to Rs 473 crore above Hindalco’s indicated normalized quarterly range of Rs 1,200 crore to Rs 1,300 crore. Management said the gap was not one exceptional item. It included higher realised proceeds from copper slag sales than accrued, derivative-related effects and additional precious-metals sales, which together accounted for roughly Rs 350 crore to Rs 400 crore that it did not consider sustainably repeatable.
Hindalco’s copper performance was part of a broader increase in India earnings. India business segment EBITDA rose 66% year on year to Rs 9,011 crore in Q2 FY27, while consolidated EBITDA increased 52% to Rs 13,869 crore. Copper, Novelis and aluminium downstream, which Hindalco identifies as non-LME-linked businesses, generated combined earnings of Rs 6,860 crore during the quarter.
What supports Hindalco’s Rs 1,200 crore to Rs 1,300 crore copper outlook?
Hindalco said its Rs 1,200 crore to Rs 1,300 crore quarterly copper EBITDA expectation is largely supported by sulphuric-acid pricing, precious-metals sales and pricing for copper downstream products. This is management’s outlook for coming quarters, rather than a full-year target. The business produces and sells around 300,000 tonnes of sulphuric acid each quarter, making acid pricing a material factor in segment earnings.
Sulphuric-acid realisations were about Rs 16,000 per tonne in Q2 FY27, compared with around Rs 7,000 per tonne in the same quarter a year earlier, according to management. It said even the year-earlier Rs 7,000 per tonne was high compared with the Rs 3,000 to Rs 4,000 per tonne range seen before that. The Q2 FY27 realisation was therefore more than twice the prior-year level and about four to five times that earlier range.
Management gave only a broad indication of the earnings mix when discussing sulphuric-acid contribution, saying about 50% came from “other stuff” and 50% from copper. Hindalco did not disclose separate EBITDA amounts for sulphuric acid, precious metals or downstream copper products. The durability of the Rs 1,200 crore to Rs 1,300 crore range is consequently linked in part to the future path of acid prices and the contribution from those other products.
Got a follow-up? Ask IRIS
How unusual are Hindalco’s current sulphuric-acid prices?
Hindalco’s sulphuric-acid realisation of about Rs 16,000 per tonne in Q2 FY27 was substantially higher than both the Rs 7,000 per tonne recorded a year earlier and the Rs 3,000 to Rs 4,000 per tonne level management described as typical before that. Management said sulphuric-acid and sulphur prices were “really high” during the quarter. That difference helps explain the importance of acid to near-term copper profitability.
The elevated acid market came as India’s refined-copper demand declined 3% year on year to 388 kilotonnes in Q2 FY27. Hindalco said growth in building, construction and power demand was partly offset by softer demand from consumer durables and electrical equipment. Its reported metal shipments nevertheless increased 2% to 116 kilotonnes, while its CCR volume remained at 96 kilotonnes.
Copper concentrate markets also remained tight during Q2 FY27, reflecting a structural gap between growing global smelting capacity and constrained mine-supply growth. Hindalco said it was comfortable obtaining concentrate because it has long-term contracts with large miners. The transcript did not quantify the earnings benefit of those contracts or provide a sensitivity for changes in concentrate-market conditions.
What could change Hindalco’s normalized copper earnings?
Hindalco’s normalized copper earnings could change with sulphuric-acid pricing, precious-metals sales, copper downstream product pricing and any recurrence of the items excluded from its Q2 FY27 run rate. Management identified roughly Rs 350 crore to Rs 400 crore from copper-slag realisation differences, derivatives and additional precious-metals sales as not sustainably repeatable. Its Rs 1,200 crore to Rs 1,300 crore expectation is therefore below the quarter’s Rs 1,673 crore reported EBITDA.
Concentrate availability is another operating consideration for the segment. Hindalco said its long-term miner contracts meant it had no problem sourcing concentrate despite the wider market’s tight conditions in Q2 FY27. At the same time, India’s refined-copper demand was 388 kilotonnes, down 3% year on year, showing that the segment’s record EBITDA was supported by factors beyond domestic refined-copper demand growth.
Hindalco is also progressing copper capacity projects. Management said its Pakhajan copper recycling plant is scheduled to commission in December of the current year, while a copper smelter is planned for commissioning in December 2028. It also identified a potential expansion of copper recycling capacity from 50 kilotonnes to 150 kilotonnes, but said updates would follow as projects receive execution approvals.
Conclusion
Hindalco’s record Rs 1,673 crore copper EBITDA in Q2 FY27 included roughly Rs 350 crore to Rs 400 crore that management does not view as sustainably repeatable. The stated Rs 1,200 crore to Rs 1,300 crore quarterly level separates that non-recurring contribution from an earnings base supported by sulphuric-acid prices, precious-metals sales and downstream copper pricing.
The next developments to watch are sulphuric-acid realisations after the Q2 FY27 level of about Rs 16,000 per tonne and commissioning of the Pakhajan recycling plant in December. Management also plans to commission a copper smelter in December 2028 and has said it aims to keep consolidated net debt to EBITDA at around two times while funding its expansion programme.