










Hindalco Industries Limited Q2 EBITDA rises 52% to ₹13,869 crore
Key highlights
- Hindalco Industries Limited's earnings-call summary reported Q2 FY27 consolidated EBITDA of ₹13,869 crore, up 52% year-on-year.
- Record quarterly revenue from operations was ₹91,708 crore, up 39% year-on-year.
- India business EBITDA rose 66% year-on-year to ₹9,111 crore, while PAT increased 91% to ₹5,852 crore.
- Hindalco expects India capex of ₹12,000 crore to ₹13,000 crore in FY27 and plans the Pakhajan recycling plant for December 2026.
powered by IRIS
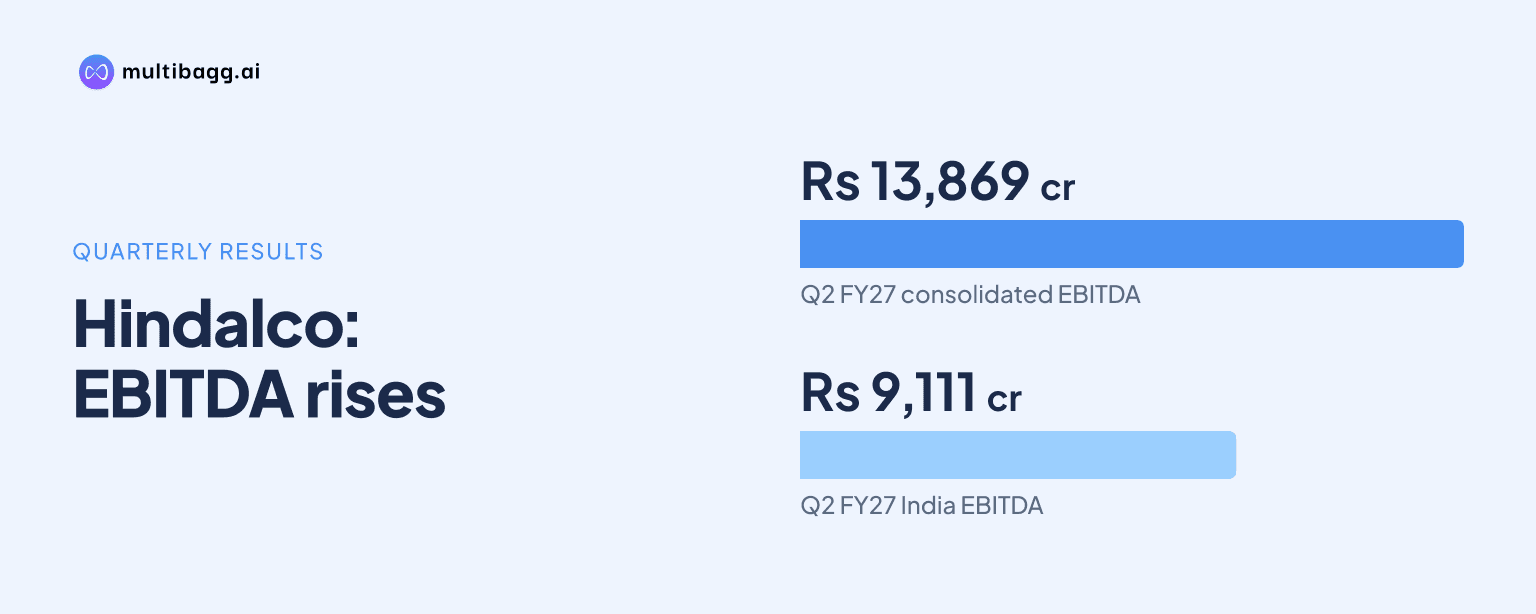
Hindalco Industries Limited reported consolidated EBITDA of ₹13,869 crore for Q2 FY27, up 52% year-on-year, with India operations delivering ₹9,111 crore of segment EBITDA and management detailing a ₹50,000 crore expansion pipeline. The quarter reflected strong aluminium performance, record copper EBITDA and higher consolidated revenue.
Know Hindalco Industries inside out
Results, valuation, peers and who's buying, in one view.
What did Hindalco report for Q2 FY27?
Hindalco reported strong year-on-year growth in its Q2 FY27 earnings-call summary, led by its India aluminium operations. Consolidated EBITDA was stated at ₹13,869 crore, up 52% year-on-year, while consolidated profit after tax rose 59% to ₹7,534 crore. The company also reported record quarterly revenue from operations of ₹91,708 crore, a 39% increase year-on-year.
The India business was the principal contributor to the improvement. Segment EBITDA rose 66% year-on-year to ₹9,111 crore and quarterly profit after tax increased 91% to ₹5,852 crore. Management attributed the performance to favourable macroeconomic conditions and operational execution across the value chain.
Aluminium upstream EBITDA increased 55% year-on-year to ₹7,009 crore. Copper EBITDA rose 164% to a record ₹1,673 crore. Management indicated that copper earnings included approximately ₹350 crore to ₹400 crore of one-off items, an important consideration when assessing the recurring level of profitability in that business.
There is a difference in the EBITDA figure across the supplied materials. The earnings-call summary cited consolidated EBITDA of ₹13,869 crore, while a results release cited ₹13,757 crore, up 42% year-on-year. The figures in this article refer to the earnings-call summary where discussing management commentary, while noting the reported difference for readers comparing disclosures.
Which businesses drove Hindalco's quarterly performance?
Hindalco's India aluminium operations drove the quarter, supported by favourable industry conditions and stronger value-chain performance. The rise in upstream aluminium EBITDA was a central factor behind the 66% growth in India business EBITDA. This segment's performance also helped lift India business profit after tax by 91% year-on-year.
Copper was another material contributor, with EBITDA reaching ₹1,673 crore. However, management's indication that ₹350 crore to ₹400 crore of this amount came from one-off factors means the headline growth rate does not represent only underlying operating trends. Analysts on the call focused on the possible normalisation of copper earnings and on aluminium cost pressures expected in the following quarter.
Novelis, Hindalco's wholly owned subsidiary, remained relevant to discussions around group leverage and capital allocation. Management said Novelis leverage was expected to be around 4 times by the end of Q4 FY27. Its EBITDA-per-tonne target of $600 was unchanged, according to the call summary.
Got a follow-up? Ask IRIS
What is Hindalco's India expansion timetable?
Hindalco plans to sequence its evaluated ₹50,000 crore India expansion programme around project completion dates and a debt discipline target. Managing Director Satish Pai said the immediate priority was completing the first set of projects before taking up subsequent investments. The company intends to start a new project approximately every 18 months.
The copper recycling plant at Pakhajan is scheduled for completion in December 2026. The Aditya alumina refinery and the first 180 kT Aditya line are both scheduled for December 2027. The second Aditya line and a copper smelter are planned next, with a December 2028 timeline, followed by the Mahan expansion.
This sequencing is significant because it links a substantial growth pipeline to completion milestones rather than presenting all projects as simultaneous investments. Management said it aims to maintain consolidated net debt to EBITDA at around 2 while pursuing the programme. That target provides a stated framework for judging the pace and funding of future projects.
How will capex and leverage shape Hindalco's plans?
Hindalco expects India capital expenditure of about ₹12,000 crore to ₹13,000 crore in FY27, with spending described as substantially higher in FY28. The investment plan covers the first group of projects that management identified as its near-term execution priority.
The higher capex commitment follows a period of stronger operating earnings, but it also makes cash generation, project delivery and balance-sheet management important for investors. Management's target of around 2 times consolidated net debt to EBITDA indicates that the company intends to align future project starts with leverage capacity.
The structure of the programme also matters for industry operations. The Pakhajan recycling plant expands Hindalco's copper recycling presence, while the Aditya refinery and aluminium lines add to its aluminium value chain. The subsequent copper smelter and Mahan expansion remain part of the disclosed pipeline, rather than immediate FY27 completion projects.
What does the quarter mean for investors and the metals sector?
The quarter shows that Hindalco's India operations benefited from a combination of aluminium strength and operational performance, while copper produced a record EBITDA contribution. Revenue growth of 39% and profit-after-tax growth of 59% show the scale of the reported improvement at the consolidated level.
For investors, the disclosed one-off component in copper EBITDA is relevant when comparing quarterly earnings. The FY27 and FY28 capex plans, Novelis leverage trajectory and the stated net debt-to-EBITDA objective are also central to evaluating how the company balances growth investment with financial discipline. No revised Novelis EBITDA-per-tonne target was disclosed in the call summary.
For the broader metals sector, the planned projects point to continued investment in aluminium refining, smelting-related capacity and copper recycling. The timetable gives suppliers, customers and market participants specific milestones to monitor, although the supplied material does not provide revised project costs or production volumes for each asset.
Conclusion
Hindalco's Q2 FY27 earnings-call commentary showed a sharp rise in India business profitability, with consolidated EBITDA of ₹13,869 crore and India segment EBITDA of ₹9,111 crore. Aluminium upstream performance and record copper EBITDA supported the result, though management identified a ₹350 crore to ₹400 crore one-off contribution within copper earnings.
The next milestones are the planned December 2026 commissioning of the Pakhajan copper recycling plant and the December 2027 targets for the Aditya alumina refinery and first 180 kT line. Investors will also watch FY27 capex of ₹12,000 crore to ₹13,000 crore, higher expected FY28 spending, Novelis leverage guidance and Hindalco's ability to maintain net debt to EBITDA around 2 times.