










Hitachi Energy India’s ex-HVDC orders rise 86% in Q2 FY27
Key highlights
- Hitachi Energy India’s Q2 FY27 orders excluding HVDC rose 85.9% year on year and 21.8% quarter on quarter.
- Hitachi Energy India reported Q2 FY27 revenue of Rs 2,996.5 crore, up 63.5% year on year.
- Hitachi Energy India ended Q2 FY27 with an order backlog of Rs 33,335.4 crore.
- Hitachi Energy India’s Q2 FY27 service orders rose 77.1% year on year and export orders rose 41%.
powered by IRIS
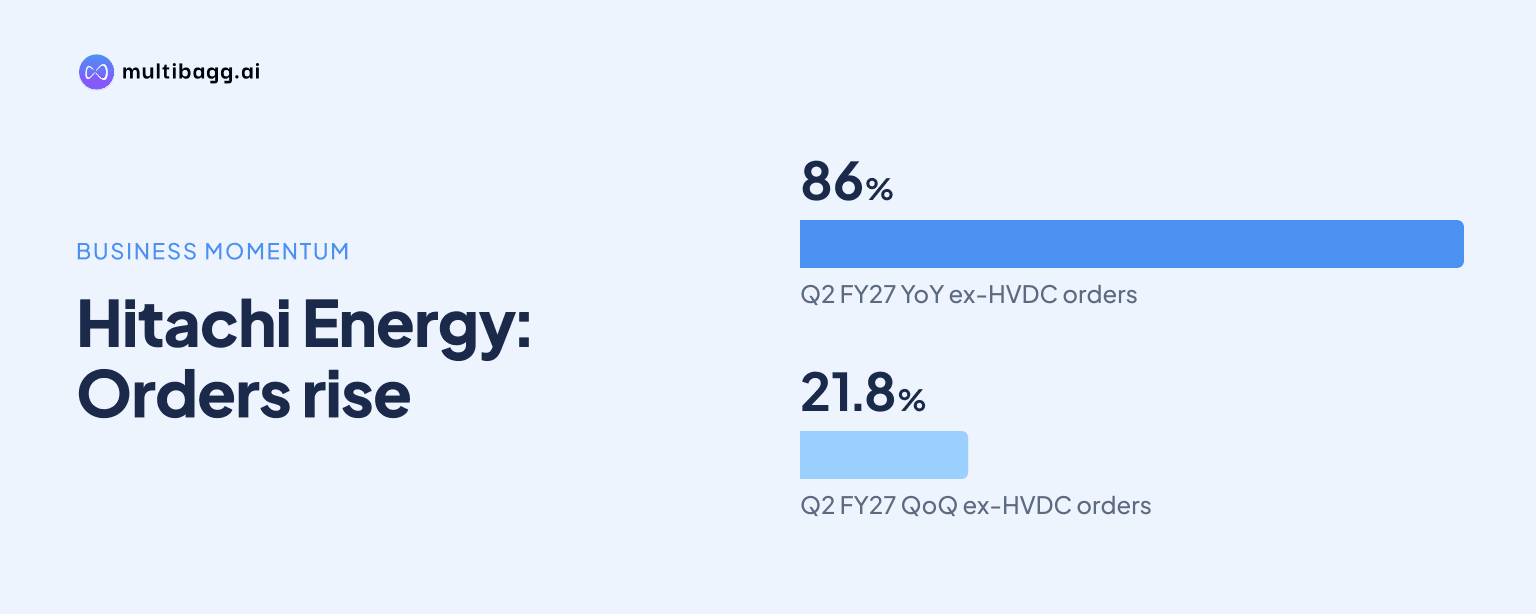
Hitachi Energy India Limited reported 85.9% year-on-year growth in Q2 FY27 orders excluding high-voltage direct current (HVDC) projects, with revenue rising 63.5% to Rs 2,996.5 crore and the order backlog reaching Rs 33,335.4 crore. The company attributed underlying order growth to transmission, industries, data centres, services and exports.
Know Hitachi Energy India inside out
Results, valuation, peers and who's buying, in one view.
How fast did Hitachi Energy India’s underlying orders grow?
Hitachi Energy India booked Rs 4,120.8 crore of orders in Q2 FY27, while order intake excluding HVDC grew 85.9% year on year and 21.8% quarter on quarter. For H1 FY27, total orders were Rs 9,217.3 crore, and underlying order intake excluding HVDC rose 53.1% from H1 FY26.
The reported H1 FY27 order intake, including HVDC, was down 32% year on year because the prior-year comparison included large HVDC awards. Hitachi Energy India ended Q2 FY27 with an order backlog of Rs 33,335.4 crore, which management described as showing double-digit year-on-year growth and providing revenue visibility for coming years.
Order composition shifted towards projects in Q2 FY27. Products accounted for 60% of orders, projects accounted for 34% compared with 19% a year earlier, and services represented about 7%. Utilities made up 52% of the sector mix, followed by industries at 24% and transport and infrastructure at 23%; management said the mix was more balanced than the utilities-heavy prior-year quarter.
Which businesses drove Hitachi Energy India’s orders?
Hitachi Energy India said domestic orders excluding HVDC were led by transmission, industries and data centres in Q2 FY27. The company won four tariff-based competitive bidding orders from two engineering, procurement and construction players, including a static synchronous compensator order, and also received grid-automation orders from two utilities.
Service-order intake increased 77.1% year on year during Q2 FY27. Management cited digitally enabled services, service-level agreements, gas-insulated switchgear augmentation and substation extensions for utility, industrial and engineering, procurement and construction customers. Management said the service business remains predominantly focused on India and is being supported by additional field personnel, productised offerings and digital investments.
Export orders rose 41% year on year in Q2 FY27, with wins in Asia, Africa, the Middle East, Europe and the United States, including a TenneT order. Management said Hitachi Energy India has no United States data-centre orders in its backlog, while its data-centre supplies are in India, Southeast Asia and the broader Asia-Pacific region.
The company also reported execution milestones during the quarter. It delivered India’s first grid-forming 400 kilovolt, two-by-550 megavolt-ampere reactive static synchronous compensator projects at Fatehgarh, and inaugurated a grid-automation project covering more than 180,000 circuit kilometres of transmission line for the country’s largest power utility.
Got a follow-up? Ask IRIS
What did order growth mean for Hitachi Energy India’s profit?
Hitachi Energy India converted its backlog into Q2 FY27 revenue of Rs 2,996.5 crore, up 63.5% year on year and 20.2% from Q1 FY27. H1 FY27 revenue was Rs 5,490.2 crore, up 65.8% from H1 FY26, while Q2 profit after tax rose at a slower 20.5% rate to Rs 318.5 crore.
Operational earnings before interest, tax, depreciation and amortisation (EBITDA) were Rs 494.4 crore in Q2 FY27, up 69.5% year on year and 23.6% quarter on quarter. Operational EBITDA margin was 16.5%, despite product-mix effects, supply-chain pressures and raw-material price escalation cited by management. H1 FY27 operational EBITDA reached Rs 894.3 crore, nearly double the prior-year period.
Profit before tax was Rs 430.4 crore in Q2 FY27, up 22% year on year and 10.5% quarter on quarter. The figure included an Rs 88.1 crore notional foreign-exchange loss, which management classified as non-operational and excluded from EBITDA. H1 FY27 profit before tax rose 54.8% to Rs 819.9 crore.
Material cost represented 61.7% of Q2 FY27 revenue, personnel expense was 6.2%, and other operating expenses were 16.6%. Hitachi Energy India reported exchange and commodity losses of Rs 56.1 crore, or 1.9% of revenue, while other income was Rs 56.8 crore, primarily from interest on bank deposits.
What capacity plans and markets could support future growth?
Hitachi Energy India is investing in transformer, high-voltage product and grid-automation capacity, with most projects targeted for completion by the end of 2027. Its newly announced large power-transformer facility is targeted for 2028, and management said the programme is intended to progressively increase manufacturing readiness against its Rs 33,335.4 crore backlog and opportunity pipeline.
Management based its market commentary on industry and policy indicators rather than company guidance. India’s renewable-energy capacity reached 299.25 gigawatts at September 2026-end, against a national ambition of 900 gigawatts for 2035-36. Management also cited approved projects including Green Energy Corridor Phase-III and 50 gigawatt-hours of battery energy storage.
For FY27, management listed utilities and HVDC as core priorities, alongside mobility, services, battery energy storage, data centres, exports and digital businesses. It said Hitachi Energy India has launched a grid-to-rack data-centre offering and is discussing it with customers; if orders are received, the solutions would be manufactured in India. Management did not give financial guidance.
Conclusion
The Q2 FY27 performance indicates that Hitachi Energy India’s order momentum was not limited to large HVDC awards. Underlying orders grew 85.9%, service orders rose 77.1%, export orders increased 41%, and revenue grew 63.5%, while the project share of orders rose to 34% from 19% a year earlier.
The next disclosed milestones are conversion of the Rs 33,335.4 crore backlog into revenue, completion of most current capacity projects by the end of 2027, and the large power-transformer facility targeted for 2028. Management’s conversion of grid-to-rack customer discussions into orders is also unresolved, as it provided neither data-centre backlog figures nor financial guidance.