










Hy-Tech Engineers Q2 revenue up 22% as PAT rises 23% in FY27
Key highlights
- Hy-Tech Engineers reported Q2 FY27 revenue from operations of Rs 60.9 crore, up 22% year-on-year and 41% quarter-on-quarter.
- Hy-Tech Engineers reported Q2 FY27 EBITDA of Rs 14.5 crore, up 21% year-on-year, with a 23.8% margin.
- Hy-Tech Engineers reported Q2 FY27 PAT of Rs 8.5 crore, up 23% year-on-year, with a 14% margin.
- Hy-Tech Engineers reported H1 FY27 revenue of Rs 103.9 crore and PAT of Rs 13.1 crore, up 19% year-on-year.
powered by IRIS
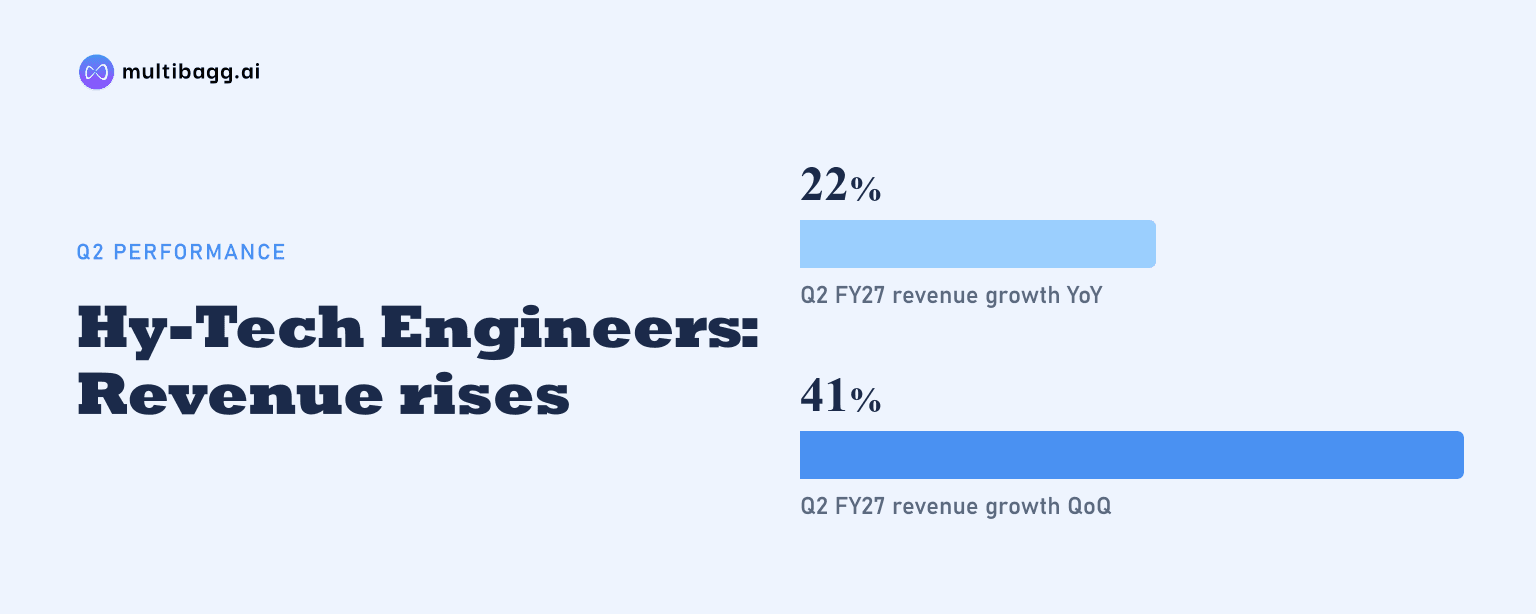
Hy-Tech Engineers Limited reported Rs 60.9 crore of revenue from operations in Q2 FY27, up 22% year-on-year, and Rs 8.5 crore of profit after tax, up 23%, for the quarter ended September 30, 2026. Earnings before interest, tax, depreciation and amortisation (EBITDA) were Rs 14.5 crore, with a reported margin of 23.8%.
Know Hy-Tech Engineers inside out
Results, valuation, peers and who's buying, in one view.
How did Hy-Tech Engineers perform in Q2 FY27?
Hy-Tech Engineers recorded revenue from operations of Rs 60.9 crore in the second quarter (Q2) of financial year (FY) 27, rising 22% year-on-year and 41% quarter-on-quarter. EBITDA increased 21% year-on-year and 72% quarter-on-quarter to Rs 14.5 crore, while profit after tax (PAT) rose 23% year-on-year and 86% quarter-on-quarter to Rs 8.5 crore.
PAT grew one percentage point faster than revenue on a year-on-year basis, at 23% versus 22%. EBITDA growth, at 21%, was one percentage point below revenue growth, while the company reported Q2 EBITDA and PAT margins of 23.8% and 14%, respectively.
The sequential comparison showed faster growth in earnings than sales during Q2 FY27. Revenue increased 41% from the preceding quarter, compared with EBITDA growth of 72% and PAT growth of 86%, although the November 5, 2026 release does not provide a cost, pricing, product-mix or finance-cost bridge explaining those differences.
What do Hy-Tech Engineers’ Q2 margins show?
Hy-Tech Engineers reported a Q2 FY27 EBITDA margin of 23.8% and a PAT margin of 14% on revenue of Rs 60.9 crore. EBITDA of Rs 14.5 crore was equivalent to the disclosed operating margin, while PAT of Rs 8.5 crore represented the reported post-tax margin.
The company described Q2 FY27 profitability as sustained, but its release does not provide Q2 FY26 EBITDA or PAT margin figures. The disclosed figures therefore support comparison between Q2 FY27’s 23.8% EBITDA margin and 14% PAT margin and the first-half ratios, rather than a conclusion on year-on-year margin movement.
Q2 FY27 margins were above those reported for the first half (H1) of FY27, when EBITDA margin was 22.1% and PAT margin was 12.6%. The difference was 1.7 percentage points for EBITDA and 1.4 percentage points for PAT, based on the company’s reported quarterly and six-month ratios.
How did Hy-Tech Engineers’ first-half results compare with Q2?
Hy-Tech Engineers reported H1 FY27 revenue from operations of Rs 103.9 crore, up 18% year-on-year, EBITDA of Rs 22.9 crore, up 14%, and PAT of Rs 13.1 crore, up 19%. Its H1 FY27 EBITDA margin was 22.1%, while its PAT margin was 12.6%.
Q2 FY27 growth exceeded H1 FY27 growth across all three disclosed measures. Revenue grew 22% in Q2 against 18% in H1, EBITDA rose 21% against 14%, and PAT increased 23% against 19%, while Q2 margins were also higher than the H1 ratios.
The Q2 figures formed a substantial part of the reported six-month totals, with Rs 60.9 crore of H1 revenue of Rs 103.9 crore, Rs 14.5 crore of H1 EBITDA of Rs 22.9 crore, and Rs 8.5 crore of H1 PAT of Rs 13.1 crore. Hy-Tech Engineers did not provide a separate Q1 FY27 income statement in the release.
Got a follow-up? Ask IRIS
What products and operations support Hy-Tech Engineers’ sales?
Hy-Tech Engineers designs, manufactures and supplies hydraulic fittings and forged metal components for construction, agriculture, automotive, industrial equipment, defence and railways. The Rs 60.9 crore Q2 FY27 revenue figure is not split by customer, industry, product, geography or export market in the results release.
Hy-Tech Engineers operates six manufacturing facilities across Maharashtra and Madhya Pradesh, with forging, machining, finishing and testing capabilities. The company cites backward integration and technology-driven manufacturing in describing its operating model, but the H1 FY27 announcement does not disclose plant capacity, utilisation, output volumes or plant-level profit.
The company said it is strengthening its portfolio through stainless-steel double-ferrule fittings for specialised and high-growth sectors. Hy-Tech Engineers did not disclose a launch date, order value, revenue contribution, margin target or expected sales share for this product category as of the September 30, 2026 results.
What is Hy-Tech Engineers planning in the United States?
Hy-Tech Engineers said it has established a wholly owned subsidiary and warehouse in New Jersey to improve customer proximity, engagement and supply-chain responsiveness in the United States. The release does not state the facility’s cost, operating date, inventory commitment, US revenue base or expected financial contribution.
Chairman and Managing Director Hemant Mondkar said the 41% sequential revenue increase in Q2 FY27 reflected business momentum and existing customer relationships. He said management is pursuing wider product offerings, deeper international market penetration and specialised applications alongside the core hydraulic fittings business, without issuing a revenue, EBITDA or PAT forecast.
Management described the New Jersey initiative as expected to strengthen Hy-Tech Engineers’ reach in the US market and support future opportunities. The company’s November 5, 2026 release also cautioned that actual results may differ from forward-looking statements due to factors including economic conditions, demand and supply conditions, domestic prices, regulations and laws.
Conclusion
Hy-Tech Engineers converted 22% Q2 FY27 revenue growth into 23% PAT growth, reporting Rs 60.9 crore of revenue, Rs 14.5 crore of EBITDA and Rs 8.5 crore of PAT for the quarter ended September 30, 2026. The reported Q2 EBITDA margin of 23.8% and PAT margin of 14% were higher than H1 FY27 ratios of 22.1% and 12.6%, respectively.
The next disclosed execution points are the New Jersey subsidiary and warehouse and the expansion into stainless-steel double-ferrule fittings. Management has identified customer proximity, supply-chain responsiveness, broader products and international penetration as objectives, but has not given a timeline, revenue target, cost estimate or profit contribution for either initiative.