










IC Electricals targets Rs 270 crore FY28 revenue growth
Key highlights
- IC Electricals expects more than Rs 100 crore of fresh orders in the next four to five months.
- IC Electricals targets about Rs 270 crore of FY28 top-line revenue.
- The September 30, 2026 order book was Rs 231 crore, including Rs 140 crore in contracts.
- Revenue increased from Rs 99.24 crore in FY24 to Rs 143.04 crore in FY26.
powered by IRIS
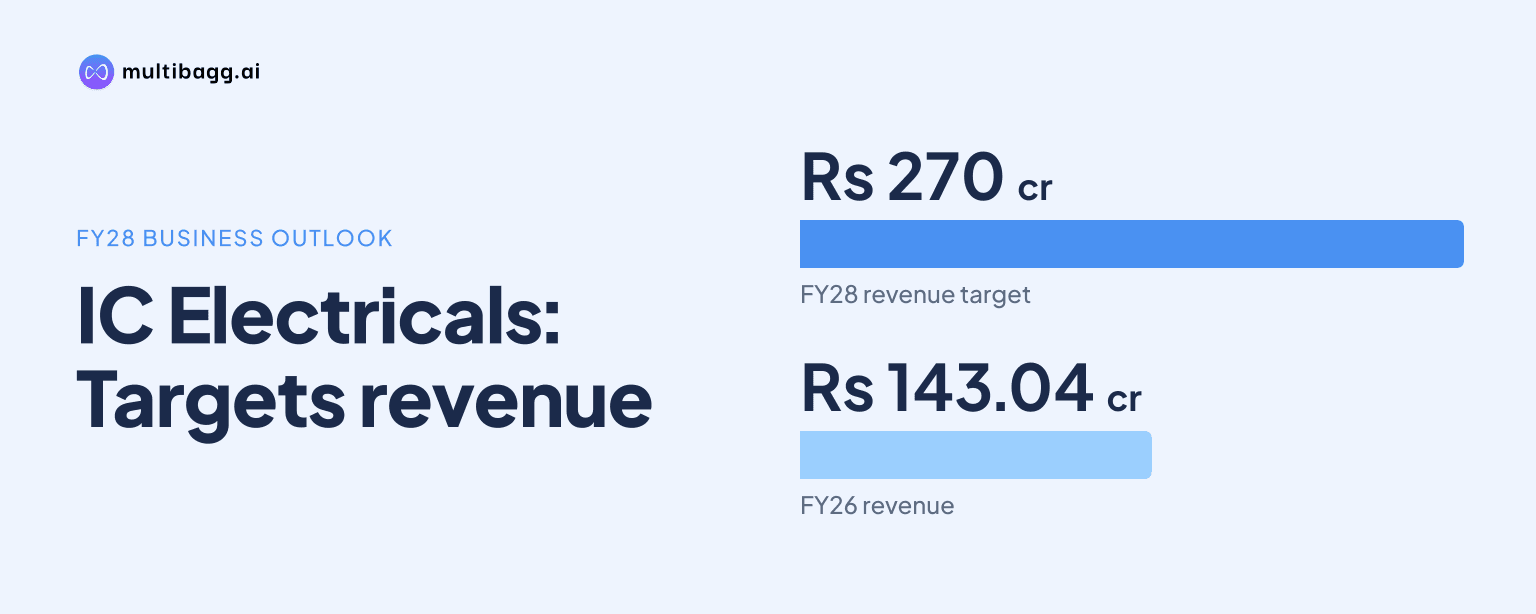
IC Electricals Company Ltd. targets about Rs 270 crore of FY28 top-line revenue, which management agreed would imply roughly 35% growth from the Rs 200 crore FY27 projection cited by an investor, while expecting more than Rs 100 crore of fresh orders in the next four to five months.
Know IC Electricals Company inside out
Results, valuation, peers and who's buying, in one view.
What is IC Electricals guiding for FY28 revenue?
IC Electricals is guiding to about Rs 270 crore of top-line revenue in FY28. During the call, an investor said this would represent close to 35% growth from a Rs 200 crore FY27 projection, and management agreed with that calculation.
The target follows reported revenue growth from Rs 99.24 crore in FY24 to Rs 143.04 crore in FY26. FY28 is a management target rather than a reported result, and the call did not provide a separate FY27 revenue guidance statement beyond the investor's reference to Rs 200 crore.
IC Electricals operates in railway electronics, rotating machines and turnkey electrification contracts. Management said its growth strategy includes contract participation in railway modernization and speed-enhancement projects, product innovation, better working-capital efficiency and export expansion for rotating machines.
How many new orders does IC Electricals expect?
IC Electricals expects more than Rs 100 crore of additional order book in the next four to five months. Management gave that expectation when asked how the company would build orders while targeting a pending order book of more than Rs 200 crore at the end of FY27.
The company had an outstanding order book of Rs 231 crore at September 30, 2026, comprising Rs 91 crore in the product division and Rs 140 crore in the contract division. Management said the Rs 140 crore contract component was expected to be executed over six months to 1.5 years, but did not provide a separate timeline for product orders.
The expected fresh orders are not disclosed awards. IC Electricals did not identify customers, tender stages, product categories or the timing of individual orders within the stated four-to-five-month period.
Can the planned order book support FY28 growth?
Management said a year-end pending order book above Rs 200 crore would support the growth path because the company has been closing years with higher order books and improving execution. It cited an order book of Rs 120 crore at March 31, 2025, followed by Rs 170 crore alongside FY26 turnover of Rs 143 crore.
A closing book of more than Rs 200 crore would exceed the Rs 170 crore FY26 reference level by more than Rs 30 crore and the Rs 120 crore March 2025 level by more than Rs 80 crore. However, IC Electricals did not disclose an order-conversion rate, cancellation rate or the proportion of the targeted book expected to become FY28 revenue.
Execution is particularly relevant for the Rs 140 crore contract book. Management said April through August are difficult months for field work because of hot weather and the rainy season, and it expects the project division to overtake the manufacturing division in the next six months.
Got a follow-up? Ask IRIS
What railway opportunities is IC Electricals pursuing?
IC Electricals is positioning its contract business for Indian Railways' transition from 1x25 kilovolt, or kV, traction systems to 2x25 kV systems. Management cited anticipated investment of more than Rs 3 lakh crore over the next seven to eight years for that transition and a rolling-stock budget allocation of about Rs 54,000 crore for the current financial year.
Management said about 90% of rail electrification has been completed, while the remaining 10% still represents business potential. It also said existing electrification may require overhauls, substations, sub-sectioning and paralleling posts, or SSPs, and upgraded overhead equipment as rail capacity and train speeds increase.
The company is in discussions with Korean vendors on technology related to its electronics, rotating-machines and contract divisions. Management did not disclose counterparties or products because discussions and signing processes were under way, but said advanced overhead equipment is relevant to rail ambitions for speeds of 180 kilometres per hour and 200 kilometres per hour.
How do IC Electricals' segments affect the plan?
IC Electricals said inventory had been built ahead of its busy contract-execution period, and management described current capital employed in the contract business as peak capital employed. The investor put that figure at about Rs 97 crore, while management said inventory would begin reducing as execution progressed without specifying a date or value target.
For FY26, the investor compared Rs 75 crore of capital employed and Rs 59 crore of revenue in the contract division with Rs 70 crore of capital employed in manufacturing, where revenue was described as about 1.2 times capital employed. Management responded that backward integration and new products would support both the engineering, procurement and construction, or EPC, business and the product division, rather than providing a segment return target.
At the company level, return on capital employed increased to 18.47% in FY26 from 15.25% in FY24, while receivables turnover rose to 4.53 times from 3.22 times. Government customers represented about 82.01% of FY26 revenue and exports 3.56%, leaving the plan principally linked to domestic government-related railway demand.
Conclusion
IC Electricals has set out connected operating aims: more than Rs 100 crore of expected fresh orders in four to five months, a FY27 pending order book above Rs 200 crore and about Rs 270 crore of FY28 revenue. The plan depends on converting the Rs 231 crore order book at September 30, 2026, particularly the Rs 140 crore contract component, while expanding product and EPC activity.
The next disclosures to watch are whether the anticipated orders arrive in the stated four-to-five-month window, whether contract inventory declines from the peak capital-employed position, and whether Korean technology discussions reach signed arrangements. Management also expects contract activity to improve over the next six months as weather conditions become more favourable for field execution.