










IC Electricals targets Rs 200 crore FY27 after H1 profit surge
Key highlights
- IC Electricals reported H1FY27 consolidated revenue of Rs 75.47 crore, up 36.1% year on year.
- IC Electricals' H1FY27 consolidated PAT rose 124.7% to Rs 8.03 crore.
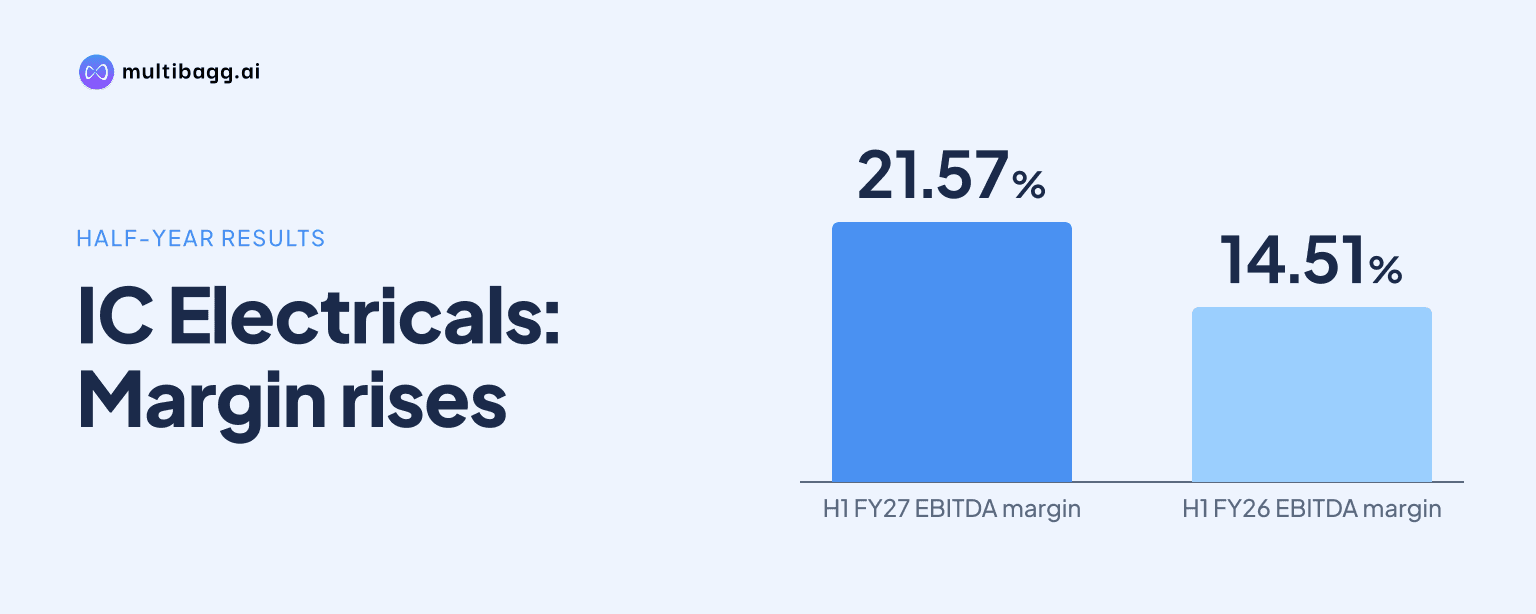
- IC Electricals' consolidated EBITDA margin increased to 21.57% in H1FY27 from 14.51% in H1FY26.
- IC Electricals reported an Rs 231.06 crore order book as of September 30, 2026.
powered by IRIS
IC Electricals Company Limited targets consolidated FY27 turnover of Rs 200 crore or more after H1FY27 revenue reached Rs 75.47 crore, while profit after tax rose 124.7% year on year to Rs 8.03 crore and EBITDA margin increased to 21.57%. Management says the target depends on a traditionally stronger second half.
Know IC Electricals Company inside out
Results, valuation, peers and who's buying, in one view.
Can IC Electricals reach Rs 200 crore turnover in FY27?
IC Electricals has guided for consolidated FY27 turnover of Rs 200 crore or above, compared with actual FY26 turnover of Rs 143.04 crore. Management said this guidance implies about 40% growth over FY26 and is supported by an order pipeline, timely execution of key contracts and expanded manufacturing capabilities.
IC Electricals recorded Rs 75.47 crore of consolidated revenue in H1FY27, or about 38% of the Rs 200 crore guidance. That leaves at least Rs 124.53 crore to be delivered in H2FY27. Management specifically notes that the second half has historically been stronger: consolidated H2FY26 revenue was Rs 87.59 crore, against Rs 55.46 crore in H1FY26.
The required H2FY27 revenue is therefore Rs 36.94 crore above the consolidated H2FY26 figure. This is a comparison with a prior half-year rather than an IC Electricals forecast. The presentation identifies execution of key contracts and an order pipeline as the stated supports, but does not provide an H2FY27 quarterly schedule or a formal margin target.
How much did IC Electricals' H1FY27 profit and margin improve?
IC Electricals' consolidated profit after tax, or PAT, more than doubled to Rs 8.03 crore in H1FY27 from Rs 3.57 crore in H1FY26, a 124.7% year-on-year increase. PAT margin rose to 10.64% from 6.45%, an increase of 4.19 percentage points, while revenue from operations grew 36.1% to Rs 75.47 crore.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 102.3% to Rs 16.28 crore from Rs 8.05 crore. EBITDA margin reached 21.57%, compared with 14.51% a year earlier. The gap between revenue growth and EBITDA growth is reflected in the 7.06-percentage-point margin expansion over H1FY26.
The H1FY27 EBITDA margin was broadly level with the immediately preceding H2FY26, when it was 21.66%, while PAT margin was 12.29% in that earlier half. H2FY26 PAT of Rs 10.76 crore exceeded H1FY27 PAT of Rs 8.03 crore, alongside higher H2FY26 revenue of Rs 87.59 crore. This comparison is consistent with management's observation that the second half has been the larger revenue period.
Got a follow-up? Ask IRIS
Which IC Electricals segments generated H1FY27 revenue?
IC Electricals generated 68% of consolidated H1FY27 revenue from manufacturing and 32% from contracts. Manufacturing revenue was Rs 51.45 crore, while contract revenue was Rs 24.02 crore, together producing consolidated revenue from operations of Rs 75.47 crore for the half year ended September 30, 2026.
Manufacturing also produced the higher segment result margin at 27.8% in H1FY27, compared with 13.1% for contracts. The manufacturing margin rose from 25.1% in FY26, while the contract margin increased from 12.9%. These segment results are stated before interest and tax, rather than EBITDA or PAT.
On an annual-versus-half-year comparison, manufacturing revenue in H1FY27 was Rs 51.45 crore against Rs 84.11 crore in FY26, while contracts contributed Rs 24.02 crore against Rs 58.93 crore in FY26. The periods are not directly comparable in duration, but manufacturing remained the larger revenue contributor in the first half.
What supports IC Electricals' FY27 execution plan?
IC Electricals reported an order book of Rs 231.06 crore as of September 30, 2026. Its business includes manufacturing railway electronic equipment and executing turnkey railway electrification projects, including design, supply, erection, testing and commissioning of 25 kilovolt alternating-current overhead equipment and traction substations.
IC Electricals operates three manufacturing units in Haridwar, has a product portfolio of more than 24 products and reported 288 employees. Its manufacturing operations cover regulators, battery chargers, emergency lights, inverters, control systems, alternators, traction motors and permanent magnet alternators with controllers, while the contracts business covers railway electrification work.
Management said IC Electricals is focused on market positioning, working-capital-cycle optimisation and profitable growth across operational verticals. It also said the research and development setup has been relocated to Delhi for better synergies, and IC Electricals is pursuing a technical tie-up with Korean partners after its representatives visited Korea. No timing, commercial terms or final agreement for that potential tie-up were disclosed.
Conclusion
IC Electricals' H1FY27 results show revenue growth of 36.1% alongside faster growth in EBITDA and PAT, lifting consolidated EBITDA margin to 21.57% and PAT margin to 10.64%. Manufacturing accounted for 68% of revenue and delivered a 27.8% segment margin, compared with 13.1% in contracts, making the manufacturing mix material to first-half profitability.
The next measure is whether H2FY27 can supply at least Rs 124.53 crore of revenue needed to reach Rs 200 crore, following Rs 87.59 crore in consolidated H2FY26. Management's disclosed supports are the Rs 231.06 crore order book, contract execution, expanded manufacturing capacity and work on a potential Korean technical tie-up; the presentation does not disclose a dated execution schedule or a final tie-up agreement.