










IGPL Q2 EBITDA margin rises to 18.8% on Rs 769.7 crore revenue
Key highlights
- IGPL reported record Q2 FY27 revenue of Rs 769.7 crore, up 63.2% year on year.
- IGPL's Q2 FY27 EBITDA was Rs 144.4 crore and its EBITDA margin was 18.8%, versus 5.8% a year earlier.
- IGPL reported H1 FY27 PAT of Rs 161.4 crore, compared with a Rs 6.8 crore loss in H1 FY26.
- IGPL's plasticizer plant began production on 30 September 2026, and its FY27 interim dividend was Rs 10 per share.
powered by IRIS
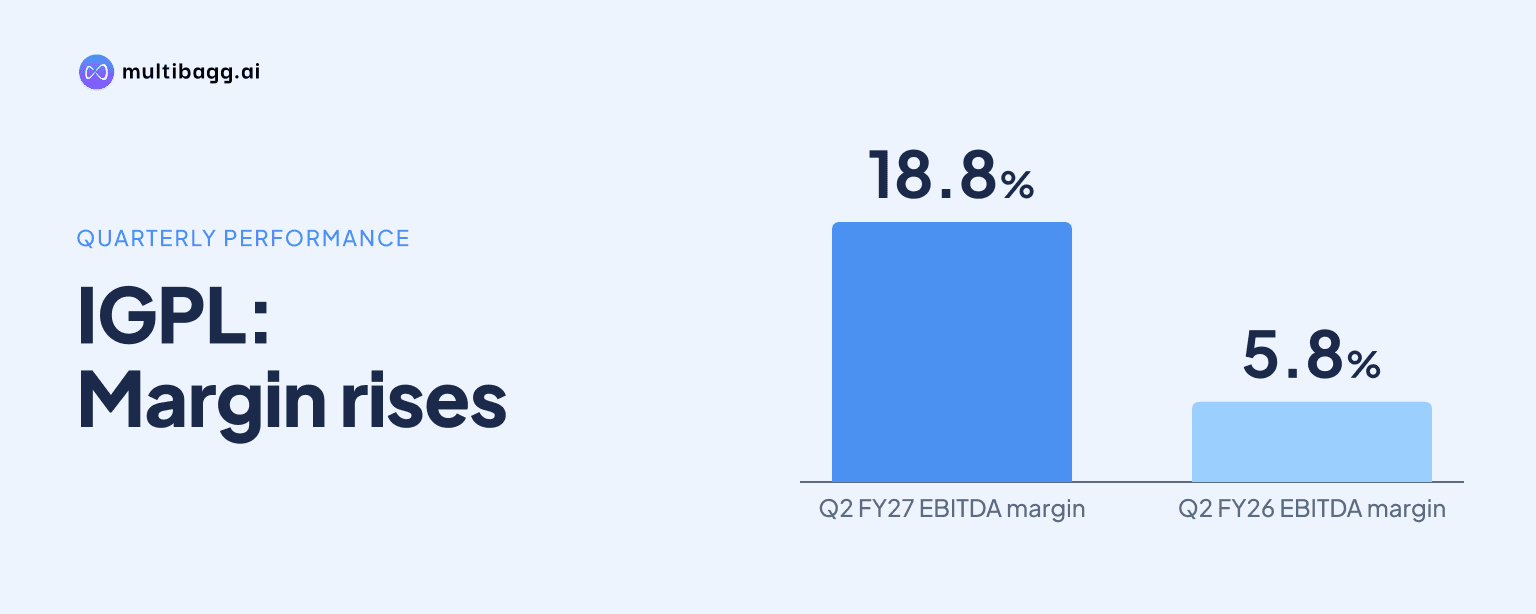
I G Petrochemicals Limited reported an 18.8% EBITDA margin in Q2 FY27, up from 5.8% in Q2 FY26, as total revenue reached a record Rs 769.7 crore. IGPL attributed the 63.2% year-on-year revenue increase to improved realisations across all products, while profit after tax rose to Rs 90.4 crore from Rs 1.4 crore.
Know I G Petrochemicals inside out
Results, valuation, peers and who's buying, in one view.
How did IGPL perform in Q2 FY27?
IGPL delivered record Q2 FY27 total revenue of Rs 769.7 crore, up 63.2% from Rs 471.6 crore in Q2 FY26. The presentation states that total revenue includes other income and attributes the increase to improved realisations across all products. EBITDA, or earnings before interest, tax, depreciation and amortisation, rose 428.1% to Rs 144.4 crore from Rs 27.3 crore.
The higher operating profit was accompanied by a 13-percentage-point change in EBITDA margin, to 18.8% in Q2 FY27 from 5.8% a year earlier. Profit after tax, or PAT, was Rs 90.4 crore compared with Rs 1.4 crore in Q2 FY26, while PAT margin increased to 11.7% from 0.3%. Earnings per share rose to Rs 29.35 from Rs 0.46.
IGPL reports these Q2 FY27 figures on a standalone basis. That means the Rs 769.7 crore revenue, Rs 144.4 crore EBITDA and Rs 90.4 crore PAT refer to the company’s standalone financial performance rather than a consolidated group result.
What drove IGPL's Q2 FY27 margin turnaround?
IGPL said improved realisations across all products drove Q2 FY27 revenue growth, while other expenses declined despite the increase in sales. Raw-material expense rose to Rs 537.3 crore from Rs 357.4 crore, employee expenses rose to Rs 27.8 crore from Rs 24.0 crore, and other expenses fell to Rs 60.2 crore from Rs 62.9 crore.
Depreciation was broadly unchanged at Rs 15.5 crore in Q2 FY27 versus Rs 15.2 crore in Q2 FY26, while finance cost fell to Rs 8.1 crore from Rs 10.2 crore. Earnings before interest and tax increased to Rs 129.0 crore from Rs 12.2 crore, and profit before tax rose to Rs 120.9 crore from Rs 2.0 crore.
IGPL recorded a Q2 FY27 tax charge of Rs 30.5 crore, compared with Rs 0.6 crore a year earlier. After tax, the company retained Rs 90.4 crore of profit, compared with Rs 1.4 crore in Q2 FY26, alongside the rise in PAT margin to 11.7%.
Got a follow-up? Ask IRIS
How did IGPL's first-half FY27 earnings change?
IGPL reported H1 FY27 revenue of Rs 1,394.7 crore, up 46.4% from Rs 952.5 crore in H1 FY26, and described this as its highest-ever first-half revenue. EBITDA rose 554.6% to Rs 264.4 crore from Rs 40.4 crore, while EBITDA margin expanded to 19.0% from 4.2%.
The first-half comparison shows a move from loss to profit. Profit before tax was Rs 215.8 crore in H1 FY27, compared with a loss before tax of Rs 8.8 crore in H1 FY26. PAT was Rs 161.4 crore, compared with a loss of Rs 6.8 crore, and earnings per share were Rs 52.39 against negative Rs 2.21.
Costs also changed during the six-month period. Raw-material expense increased to Rs 954.9 crore from Rs 736.2 crore and employee expense rose to Rs 58.2 crore from Rs 47.8 crore, while other expenses declined to Rs 117.3 crore from Rs 128.2 crore. Depreciation was Rs 31.0 crore versus Rs 30.8 crore, and finance cost decreased to Rs 17.6 crore from Rs 18.4 crore.
The H1 FY27 EBITDA margin of 19.0% was 0.2 percentage points above the 18.8% reported in Q2 FY27. Both periods were above the respective prior-year margins of 4.2% in H1 FY26 and 5.8% in Q2 FY26, while H1 FY27 PAT margin was 11.6%.
What did IGPL disclose on new businesses, exports and capital decisions?
IGPL reported Rs 68 crore of revenue from its non-phthalic business in Q2 FY27 and Rs 117 crore in H1 FY27. Export-market revenue contributed about 4% of Q2 FY27 revenue. The presentation does not disclose separate profitability for either the non-phthalic business or exports.
IGPL said its plasticizer plant commenced production on 30 September 2026. Its listed products include phthalic anhydride, maleic anhydride, benzoic acid, di-ethyl phthalate and advance plasticizers; the presentation defines PAN as phthalic anhydride and MAN as maleic anhydride.
The board declared an interim dividend for FY27 of 100%, or Rs 10 per equity share. Separately, India Ratings affirmed the IND AA-/Stable/IND A1+ ratings on existing bank loan facilities and assigned the same ratings to additional loan facilities, according to the presentation.
Conclusion
IGPL’s Q2 FY27 results show a substantial change in reported earnings alongside higher realisations: revenue increased 63.2% to Rs 769.7 crore, EBITDA margin rose by 13 percentage points to 18.8%, and PAT reached Rs 90.4 crore. In H1 FY27, revenue was Rs 1,394.7 crore and PAT was Rs 161.4 crore, compared with a loss in H1 FY26.
The next disclosed operational development to watch is the contribution from the plasticizer plant that began production on 30 September 2026. Subsequent results can also show whether non-phthalic revenue, reported at Rs 117 crore in H1 FY27, and export revenue, which accounted for about 4% of Q2 FY27 revenue, change further.