










Indus Infra Trust adds two Kerala NH-66 assets with 13.81-year life
Key highlights
- KNR Guruvayur has a 37.35-kilometre NH-66 project length and 13.81 years of residual tenor as of September 30, 2026.
- KNR Ramanattukara spans 39.682 kilometres and had 13.81 years of balance life as of September 30, 2026.
- KNR Guruvayur had received two annuities and reported Rs 1,506.395 crore of annuities receivable.
- Indus Infra Trust reported 17 HAM projects and about 994.87 kilometres of total length as of September 30, 2026.
powered by IRIS
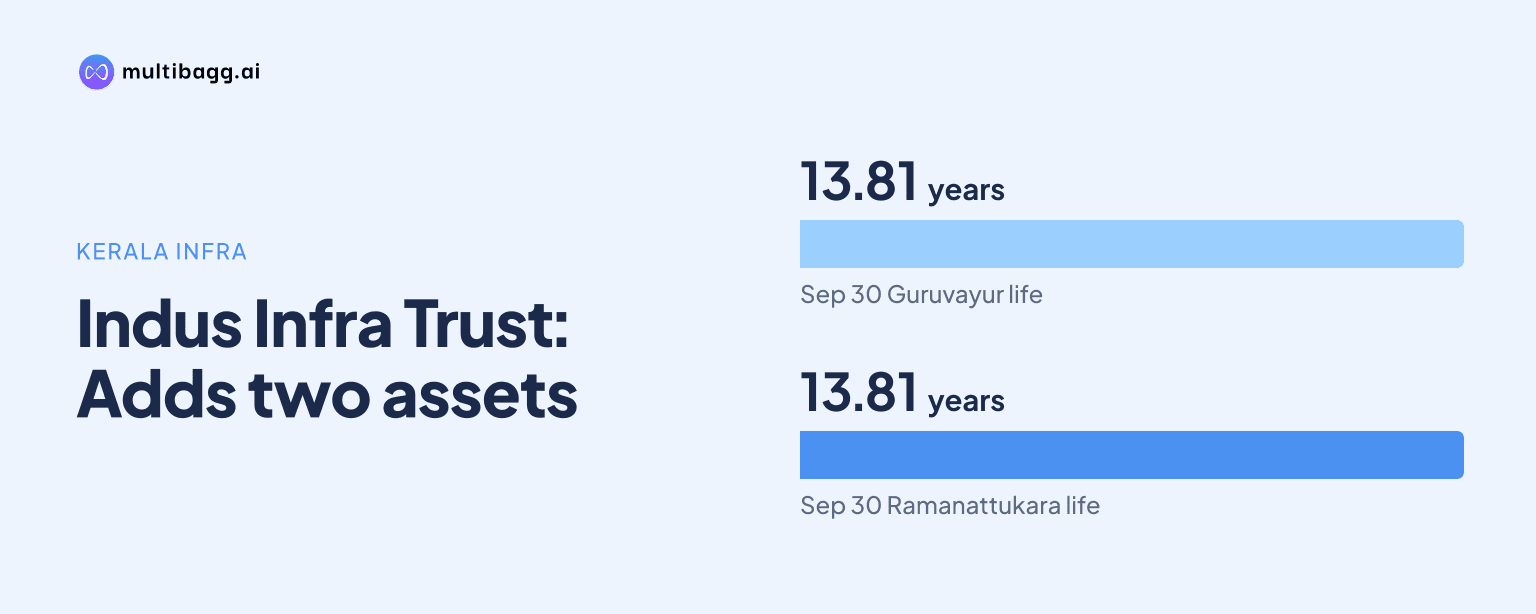
Indus Infra Trust added two operational Kerala NH-66 assets, each with 13.81 years of reported residual or balance life as of September 30, 2026; KNR Guruvayur Infra Private Limited had received two annuities and disclosed Rs 1,506.395 crore of annuities receivable. KNR Guruvayur was acquired during the quarter, while KNR Ramanattukara was acquired after September 30, 2026.
Know Indus Infra Trust inside out
Results, valuation, peers and who's buying, in one view.
What Kerala NH-66 assets did Indus Infra Trust add?
Indus Infra Trust added KNR Guruvayur Infra Private Limited and KNR Ramanattukara Infra Private Limited, two Kerala roads on National Highway 66, or NH-66. KNR Guruvayur covers the Valanchery bypass-Kappirikkad section from design chainage km 298.500 to km 335.850, with a stated project length of 37.35 kilometres and 224.10 lane kilometres.
KNR Ramanattukara covers 39.682 kilometres from Ramanattukara junction to the start of the Valanchery bypass, between design chainage km 258.818 and km 298.500. The stated chainages meet at km 298.500, making the two described sections adjacent and giving them a combined stated length of 77.032 kilometres. The presentation identifies KNR Guruvayur as a hybrid annuity model, or HAM, project under the National Highways Authority of India, or NHAI.
When did the Kerala NH-66 roads begin operations and enter the portfolio?
Indus Infra Trust reports a PCOD of July 17, 2025 for KNR Guruvayur and July 18, 2025 for KNR Ramanattukara. The two roads therefore reached their reported operational dates one day apart, before their respective portfolio-acquisition disclosures.
The transaction timing differs between the assets. KNR Guruvayur appears under “acquisition completed during the quarter”, while KNR Ramanattukara is labelled as an asset acquired after September 30, 2026. This separates the completed acquisition reported for KNR Guruvayur from the later acquisition disclosure for KNR Ramanattukara.
KNR Guruvayur’s concession is scheduled to end on July 17, 2040 and had a residual tenor of 13.81 years as of September 30, 2026. KNR Ramanattukara is shown with a 15-year operation period and 13.81 years of balance life on the same date. The shared 13.81-year figure contrasts with the one-day difference in their PCODs.
What annuity and valuation figures did Indus Infra Trust disclose for KNR Guruvayur?
Indus Infra Trust disclosed that KNR Guruvayur had received two annuities and had Rs 1,506.395 crore of annuities receivable. Its bid project cost was Rs 2,121.469 crore, while its acquisition enterprise value, stated net of cash, was Rs 1,144.1 crore.
The acquisition enterprise value was Rs 977.369 crore below the disclosed bid project cost. That comparison uses two separate measures reported in the presentation and does not establish project profitability or investment returns. The supplied pages provide no equivalent enterprise value, bid project cost or annuities-receivable amount for KNR Ramanattukara.
Got a follow-up? Ask IRIS
How do the additions compare with Indus Infra Trust’s existing projects?
Indus Infra Trust reported 17 HAM projects, about 994.87 kilometres of total length and 4,494 lane kilometres as of September 30, 2026. Its reported residual concession range was about 8.41 to 13.91 years, placing the two new Kerala assets’ 13.81-year reported life near the top of that portfolio range.
The project table shows GR Phagwara Expressway with 8.41 years of residual concession period and 13 of 30 annuities received as of September 30, 2026. KNR Guruvayur, by comparison, had 13.81 years of residual tenor and two annuities received. The comparison indicates that KNR Guruvayur was earlier in its disclosed annuity-receipt sequence than the Phagwara project.
KNR Guruvayur is listed in the asset portfolio as a Kerala project with 37.35 kilometres of design length and flexible pavement. The same portfolio lists ULCCS Kasaragod Expressway, another Kerala asset, at 39.00 kilometres, while the acquisition disclosure describes KNR Ramanattukara as 39.682 kilometres. KNR Ramanattukara does not appear in the 17-project portfolio listing, consistent with its acquisition being reported after September 30, 2026.
How was Indus Infra Trust’s Kerala acquisition activity reflected in debt disclosures?
Indus Infra Trust did not disclose the funding source, purchase-consideration structure or closing date for either Kerala acquisition in the supplied presentation pages. It reported consolidated external debt of Rs 6,181.797 crore as of September 30, 2026, but did not link that balance to KNR Guruvayur or KNR Ramanattukara.
The debt profile states that 100% of borrowings were linked to the repo rate and Treasury bill rates. It also reports a debt service coverage ratio of 2.81 times and net debt to assets under management of 37.68% as of September 30, 2026. These are reported portfolio debt measures rather than financing terms for either NH-66 asset.
The presentation shows AAA/Stable ratings from CRISIL Ratings, CareEdge Ratings and India Ratings & Research. CareEdge reaffirmed ratings for proposed and outstanding bank facilities aggregating Rs 7,901.52 crore and assigned a CARE A1+ short-term rating for Rs 500 crore of facilities, but the presentation does not say whether those facilities financed the two acquisitions.
Conclusion
The disclosures add adjacent Kerala NH-66 sections with nearly identical operating timelines and the same reported 13.81-year remaining-life measure. KNR Guruvayur provides the more complete financial disclosure, including two annuities received, Rs 1,506.395 crore of receivables and a Rs 1,144.1 crore acquisition enterprise value, while KNR Ramanattukara is identified mainly through its route, length and post-September acquisition status.
The unresolved item to watch is further disclosure on KNR Ramanattukara’s annuity receivables, valuation and annuity count, because these figures are not provided on the supplied pages. Subsequent portfolio reporting could also show how its 39.682 kilometres is incorporated alongside the 17 HAM projects and approximately 994.87 kilometres reported as of September 30, 2026.