










Indus Infra Trust targets Rs 4,700 crore ROFO deals next quarter
Key highlights
- Indus Infra is targeting about Rs 4,700 crore of ROFO acquisitions across five or six assets in the next quarter.
- Management outlined Rs 4,500 crore to Rs 5,000 crore of further ROFO acquisitions in FY28.
- The Rs 13,000 crore portfolio reported on September 30 could reach Rs 22,000 crore to Rs 23,000 crore by FY28 end through ROFO deals.
- Management said its recent four-plus-five acquired projects generated equity IRRs above 13% to 13.5%.
powered by IRIS
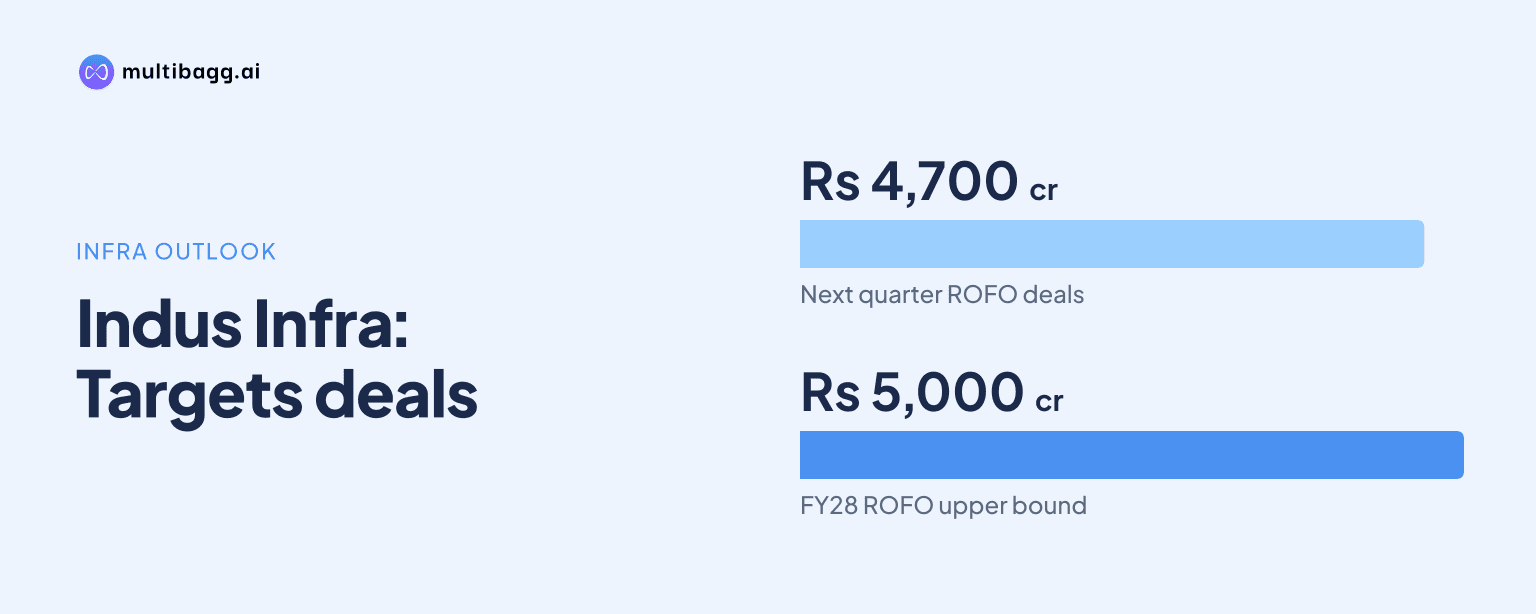
Indus Infra Trust is targeting about Rs 4,700 crore of right-of-first-offer acquisitions across five or six assets in the next quarter, and management said a further Rs 4,500 crore to Rs 5,000 crore programme in FY28 could take the portfolio from Rs 13,000 crore on September 30 to Rs 22,000 crore to Rs 23,000 crore by FY28 end.
Know Indus Infra Trust inside out
Results, valuation, peers and who's buying, in one view.
What acquisitions is Indus Infra targeting next quarter?
Indus Infra is targeting five or six ROFO assets with an enterprise value, or EV, of about Rs 4,700 crore in the next quarter. Management said it had already started seeking no-objection certificates, or NOCs, from the National Highways Authority of India, or NHAI, and indicated that the process could advance in December or the next quarter.
The proposed acquisitions still require a board meeting and board approval, followed by unitholders' pre-approval. Management did not identify the individual roads or disclose asset-level values, and described the Rs 4,700 crore figure as a ballpark aggregate EV rather than a binding commitment.
Indus Infra said it has acquired 18 assets in total, including 11 after its initial public offering, or IPO. Management said each asset acquired since listing had been yield accretive and that it aimed to retain this test for future purchases because transactions require unitholder approval.
How much could Indus Infra's portfolio grow through FY28?
Indus Infra said its ROFO roadmap could raise the portfolio from about Rs 13,000 crore on September 30 to Rs 22,000 crore to Rs 23,000 crore by the end of FY28. Management confirmed that third-party purchases, if completed, would be additional to that ROFO-based range.
For FY28, management outlined another Rs 4,500 crore to Rs 5,000 crore of ROFO acquisitions. It said the assets becoming available may be smaller, which could mean buying around six to eight assets in FY28, compared with five or six assets in the next-quarter target.
The comparison shows a broadly similar EV addition in both periods despite a potentially higher asset count in FY28. The Rs 22,000 crore to Rs 23,000 crore portfolio range is therefore contingent on completing the stated ROFO path and excludes as-yet unspecified third-party, build-operate-transfer, or BOT, and toll-operate-transfer, or TOT, transactions.
Got a follow-up? Ask IRIS
Will Indus Infra buy third-party toll roads as well?
Indus Infra is evaluating third-party roads and intends to participate in TOT opportunities, but management gave no acquisition-value guidance for either category. It said volatile bitumen prices required careful assessment of operating and maintenance, or O&M, and major-maintenance costs across the next 13 to 14 years before it could provide guidance on third-party assets.
Management said it had begun reviewing BOT and TOT toll roads because suitable hybrid annuity model, or HAM, assets were less available. It also identified Agra-Gwalior as a future ROFO BOT opportunity from GR, although management said it would not become available early.
For toll roads, management described revenue growth as a combination of traffic growth and wholesale price index, or WPI, escalation. It said the toll formula includes a rate component plus 40% of WPI, while existing TOT roads can offer five, seven or 10 years of toll-collection history to help assess traffic assumptions.
Management did not disclose bid prices, prospective acquisition values or the number of TOT roads it could acquire. It said a TOT tender that had been issued about 1.5 years earlier was coming up for bidding, but added that the bidding timetable remained an NHAI decision and that NHAI could seek proceeds before March 31.
How will Indus Infra assess returns and financing capacity?
Indus Infra said it assesses acquisitions using equity internal rate of return, or equity IRR, rather than a fixed price-to-book multiple. Management said the four-plus-five projects acquired over the recent period were producing equity IRRs above 13% to 13.5%, while stressing that future assets have no fixed 12% or 13% return threshold.
Management said value depends on discounted cash flows and the amount of money remaining in a special purpose vehicle, or SPV. It explained that earlier engineering, procurement and construction payments may have extracted value from an SPV, meaning a price-to-book multiple alone does not determine whether an acquisition is yield accretive.
On debt, management used roughly 50% leverage as a current example and said it generally did not want to exceed 65%. It said it would begin considering a fund raise once leverage moved above about 60% or 61%, instead of operating near 63%, which it described as 90% of the 70% limit.
Management put average borrowing cost at about 7.25% after a 25-basis-point repo-rate increase. It cited recent borrowings from Union and HDFC at about 7.15% to 7.25% before that increase, and said average cost could reach roughly 7.50% to 7.75% under the rate increases it envisaged; the independent valuer used an 8.05% debt assumption for an SPV without sponsor support.
Conclusion
Indus Infra has set out a sponsor-led ROFO expansion plan of about Rs 4,700 crore in the next quarter and Rs 4,500 crore to Rs 5,000 crore in FY28. If completed as described, those acquisitions could move the Rs 13,000 crore portfolio reported on September 30 toward Rs 22,000 crore to Rs 23,000 crore by FY28 end, while third-party purchases would sit outside that range.
The next milestones are NHAI NOCs, board approval and unitholder pre-approval for the five or six proposed ROFO assets, with management indicating December or the next quarter as the likely timeframe. Investors will also watch whether Indus Infra progresses on TOT or BOT evaluations and whether management provides an update at its next quarterly call.