










Indian Oil Corporation outlook stays mixed, targets Rs 135-145
Key highlights
- Motilal Oswal retained a Neutral rating on IOCL with a Rs 135 target price on November 1, 2026.
- IOCL trades at about 6x FY28E consolidated EPS of Rs 21.9 and 0.7x FY28E price to book, according to Motilal Oswal.
- PL Research forecasts FY27E EBITDA of Rs 378 billion and FY28E EBITDA of Rs 567 billion for IOCL.
- SMIFS set a Rs 160 technical target and a Rs 137 closing-basis stop loss for IOCL.
powered by IRIS
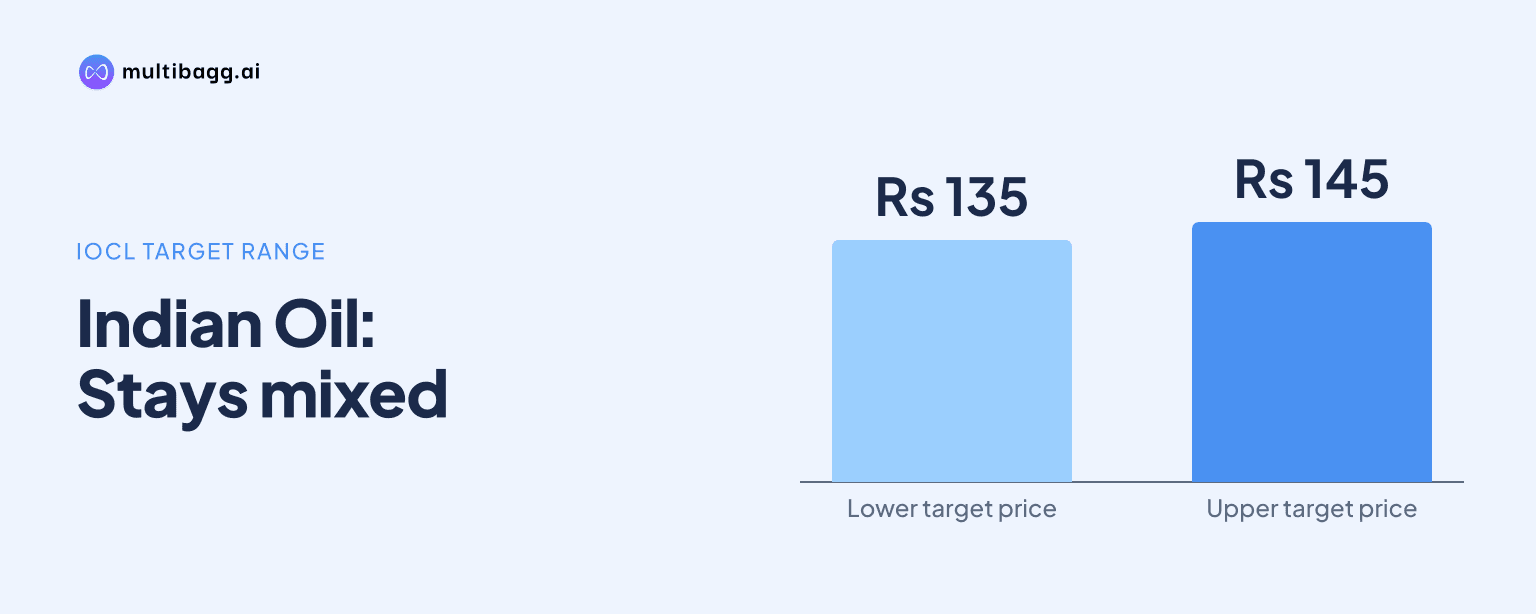
Indian Oil Corporation Limited faces a mixed stock outlook, with Motilal Oswal setting a Rs 135 target and PL Research a Rs 145 target while both point to pressure from fuel under-recoveries, refinery shutdowns and uncertain refining margins. The valuation case rests on FY28 estimates, but the near-term operating outlook remains contested.
What are the latest IOCL stock price targets?
The latest targets in the provided research range from Rs 135 to Rs 145, while SMIFS has issued a shorter-term technical target of Rs 160. Motilal Oswal retained its Neutral rating with a Rs 135 per share target in its November 1, 2026 update. PL Research retained an Accumulate call but reduced its target to Rs 145 from Rs 163.
The different calls reflect distinct time horizons and assumptions. SMIFS described a constructive chart setup after a breakout from a prolonged consolidation range, placing a Rs 160 target and Rs 137 closing-basis stop loss against a cited market price of Rs 144.50. Motilal Oswal, by contrast, highlighted limited expected upside despite low valuation metrics.
Why does IOCL look inexpensive on FY28 estimates?
IOCL trades at about 6x FY28E consolidated earnings per share of Rs 21.9 and 0.7x FY28E price to book, according to Motilal Oswal. Both metrics are below the company’s 10-year averages, which supports the view that the shares are inexpensive on the broker’s longer-term estimates.
Motilal Oswal values IOCL at 4.5x December 2027 EBITDA and adds Rs 39 per share for investments to derive its Rs 135 target. PL Research also lowered its valuation multiple amid current weakness, using 0.8x FY28E rather than 0.9x previously. The differing valuation frameworks still point to the same issue: low multiples alone may not produce substantial upside if operating assumptions weaken.
What could weigh on IOCL earnings in FY27?
Fuel under-recoveries, West Asia-related volatility, uncertainty over gross refining margins and planned refinery shutdowns are the principal FY27 risks identified by PL Research. The firm expects shutdowns to restrict FY27 throughput to about 75 million metric tonnes.
PL Research cut its FY27E EBITDA and EPS estimates by 30.4% and 45.9%, respectively. It forecasts consolidated FY27E revenue of Rs 8,899 billion, EBITDA of Rs 378 billion and profit after tax of Rs 137 billion. Motilal Oswal also reduced its EBITDA expectation for FY27 to Rs 412 billion from Rs 576 billion earlier.
Marketing performance is especially important because it can materially alter reported earnings. Motilal Oswal said IOCL reported EBITDA of Rs 303 billion and profit after tax of Rs 216 billion in the referenced period, above its estimates of Rs 143 billion and Rs 68 billion, respectively. It attributed the beat to better-than-expected marketing performance, with gross marketing margin at negative Rs 0.7 per litre versus its estimate of negative Rs 7.7 per litre.
Got a follow-up? Ask IRIS
Can refinery expansions improve IOCL's growth outlook?
IOCL’s refinery expansions could support growth after completion, with the Panipat, Gujarat and Barauni projects targeted for December 2026. The projects lift Panipat capacity from 15 million metric tonnes per annum to 25 million metric tonnes per annum, Gujarat from 13.7 million to 18 million, and Barauni from 6 million to 9 million.
Motilal Oswal expects multiple projects to be commissioned over the next two years, driving growth acceleration. This is the principal longer-term counterweight to the FY27 constraints from planned shutdowns. Whether additional capacity translates into stronger earnings will still depend on marketing margins and gross refining margins, both of which remain uncertain in the research commentary.
How should investors interpret the technical and fundamental signals?
IOCL has a positive short-term technical setup according to SMIFS, but the fundamental broker views are more measured because their targets incorporate earnings and margin risks. SMIFS cited strong price and volume participation near the breakout zone, supportive moving averages and strengthening momentum indicators.
For investors, the gap between these perspectives matters. The technical view depends on the stock sustaining above Rs 137 on a closing basis, while the longer-term valuation view depends on normalisation in margins, the extent of under-recoveries and delivery of capacity additions. PL Research’s FY28E forecasts of Rs 9,830 billion revenue, Rs 567 billion EBITDA and Rs 273 billion profit after tax indicate the scale of improvement embedded in the recovery case.
Conclusion
IOCL’s investment case combines low FY28 valuation metrics and planned refinery capacity additions with meaningful near-term uncertainty. The Rs 135 to Rs 145 fundamental targets show that broker views remain restrained despite the stock’s inexpensive price-to-book and earnings multiples, while the Rs 160 technical target is conditional on the breakout structure holding.
Investors will next watch the December 2026 completion target for the Panipat, Gujarat and Barauni expansions, FY27 throughput near the projected 75 million metric tonnes, and movements in marketing margins, fuel under-recoveries and gross refining margins. These factors will determine whether the FY28 earnings recovery projected by PL Research is realised.