










Kalyan Jewellers India Ltd targets rise to Rs 950 after Q2
Key highlights
- Kalyan Jewellers' India revenue rose 32% year-on-year to Rs 9,007 crore in Q2 FY27.
- India same-store sales growth was 20%, with 19% in the South and 21% outside the South.
- Published Buy targets ranged from Rs 765 to Rs 950 in the supplied brokerage updates.
- India profit rose 62% year-on-year to Rs 424 crore.
powered by IRIS
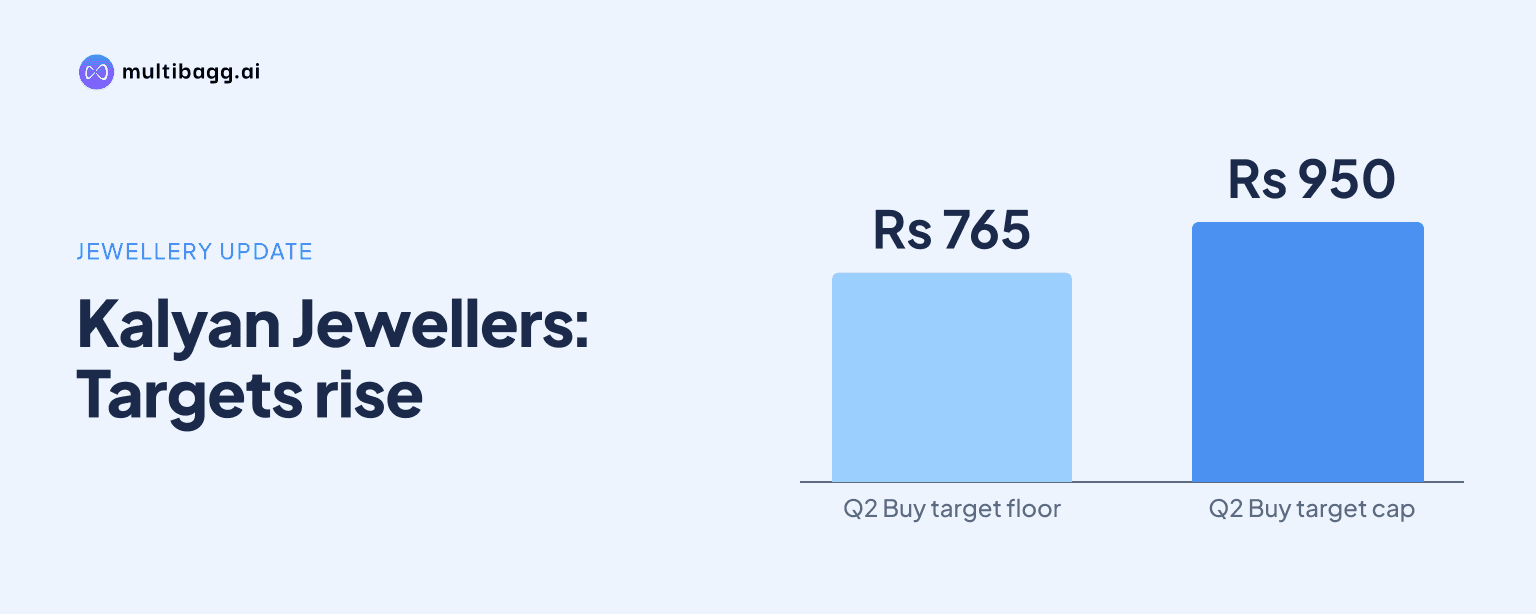
Kalyan Jewellers India Ltd saw brokerage target prices move as high as Rs 950 in November 2026 after Q2 FY27 India revenue rose 32% year-on-year to Rs 9,007 crore, supported by 20% same-store sales growth. The target revisions followed strong reported demand and upbeat commentary on the festive and wedding season.
What are the latest Kalyan Jewellers target prices?
Kalyan Jewellers has received Buy recommendations with published targets ranging from Rs 765 to Rs 950, based on the brokerage updates cited in social-media discussions. The highest target in the supplied brokerage table is Rs 950 from UBS, while another report cited UBS at Rs 900, showing that investors should check the date and version of each research note.
Motilal Oswal and ICICI Securities both retained Buy ratings and set targets of Rs 800. ICICI Securities raised its target from Rs 700, while Motilal Oswal based its Rs 800 target on 35 times estimated September 2028 price-to-earnings. Citi raised its target to Rs 880 from Rs 800, and Jefferies raised its target by 8% to Rs 900.
Why did brokerages raise Kalyan Jewellers targets?
Brokerages raised or reiterated their targets after Kalyan Jewellers reported strong Q2 FY27 performance in its India business and pointed to healthy festive and wedding demand. India revenue was reported at Rs 9,007 crore, up 32% year-on-year, while India profit rose 62% to Rs 424 crore.
Same-store sales growth was 20%, with southern markets at 19% and non-southern markets at 21%, according to the cited Motilal Oswal update. The reported performance was notable because revenue growth remained stronger than expected even as the festive calendar shifted into the December quarter.
How did Kalyan Jewellers shares react to the target revisions?
Kalyan Jewellers shares rallied after the results and brokerage actions, with one report saying the stock gained nearly 8% on November 12 to reach a fresh 52-week high of Rs 714.40. Another report said the shares jumped 15% across two sessions as targets were revised higher.
The reference prices used by brokerages differed by publication date. Jefferies calculated nearly 36% potential upside to its Rs 900 target from a November 11 closing price of Rs 663.75, while the table showing a Rs 950 UBS target used Rs 662.55 as its reference. These figures are brokerage calculations, not assurances of future returns.
Got a follow-up? Ask IRIS
What supports Kalyan Jewellers' growth outlook?
Kalyan Jewellers' near-term support case rests on reported festive demand, wedding-season momentum and broad-based same-store sales growth across southern and non-southern markets. The India business supplied the central evidence used in the cited research updates, with Rs 9,007 crore of revenue and 20% same-store sales growth.
BOB Capital Markets upgraded Kalyan Jewellers to Buy from Hold with a Rs 786 target, implying about 18% upside from a cited price of Rs 664. Its target was based on 35 times estimated earnings for the 12 months to September 2028, indicating that valuation assumptions remain important to the published upside cases.
What risks should investors consider for Kalyan Jewellers?
Kalyan Jewellers faces risks from gold-price volatility, competition and margin pressure, all of which were flagged in the supplied market discussion. A sharp rise in the share price can also reduce the gap between the prevailing market price and analysts' targets.
Target prices are not uniform: the cited range runs from Rs 765 to Rs 950, and the UBS target was reported as both Rs 900 and Rs 950 in separate items. Retail investors should therefore treat broker targets as valuation opinions tied to assumptions on earnings, demand and multiples rather than as a single market forecast.
Conclusion
The November 2026 discussion around Kalyan Jewellers is centred on stronger Q2 FY27 India performance and a cluster of Buy calls following the festive-demand outlook. Reported India revenue growth of 32%, Rs 9,007 crore of revenue and 20% same-store sales growth provided the key operating evidence behind revised targets.
The next factors to watch are festive and wedding-season demand, the sustainability of same-store sales growth, gold-price movements and any effect on margins. Investors should also track subsequent brokerage updates, particularly where published target figures differ, and compare them with the company's reported results and management commentary.