










KBL Says UK Margins May Recover to Prior Levels Next Year
Key highlights
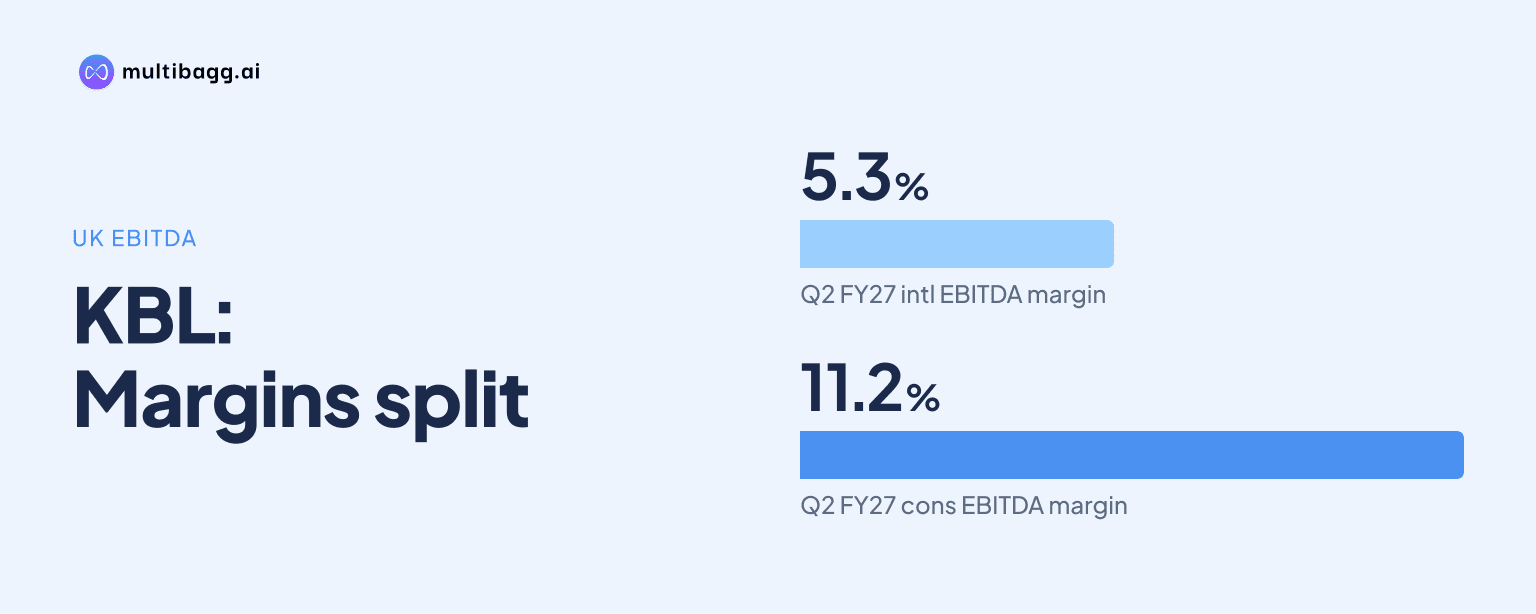
- KBL reported a 5.3% international EBITDA margin in Q2 FY27, versus an 11.2% consolidated EBITDA margin.
- KBL said UK material costs rose exactly 8% during FY27.
- KBL's overseas pending order book reached Rs 1,701.3 crore in September 2026, up 32% year on year.
- KBL said UK margins should improve in FY27 but may resemble FY24-25 levels only in the following year.
powered by IRIS
Kirloskar Brothers Limited said on October 28, 2026 that UK margins should improve in the second half of FY27, but may not resemble FY25 levels until the following year, as UK material costs rose 8%, oil-and-gas work carries lower initial margins, and service-contract starts have been delayed.
Know Kirloskar Brothers inside out
Results, valuation, peers and who's buying, in one view.
Why are KBL's UK margins under pressure?
KBL said UK profitability is being affected by three linked factors: an exactly 8% increase in UK material costs, a larger share of oil-and-gas work, and a lower services contribution in the first part of the year. The company reported international EBITDA of Rs 23.3 crore in Q2 FY27, equivalent to a 5.3% margin, and attributed the moderation primarily to services, which traditionally carry higher margins.
An analyst said the UK business made 0% profit in H1 FY27, compared with EBITDA margins of 12% in FY25 and 7% in FY26. Management did not confirm a separate reported H1 UK profit or margin figure, but said margins would recover during the year on both KBL's financial-year basis and the UK calendar-year basis. It also said the recovery in FY27 would not be like FY25.
Oil-and-gas orders add a further margin constraint at the product-execution stage, according to management. KBL said this work has lower product margins and requires more specialised skills, increasing employee-related expenses. Management said the economic benefit comes later when spare-parts demand develops, meaning the current order book can raise revenue and workload before generating the related aftermarket contribution.
When does KBL expect UK margins to improve?
KBL expects only a partial recovery in the current quarter and the following quarter, while management said the second half should deliver better margins than H1 FY27. The timing reflects the different reporting calendars: KBL's FY27 ends in March 2027, while its international companies follow the January-to-December calendar. Management identified January to March as the international businesses' first quarter of the next calendar year.
The expected improvement depends on service contracts moving into execution. KBL said it had won more service contracts, but site evaluations must be completed before work can begin. The company assesses customer assets, including equipment made by other brands, to determine whether refurbishment, repair or replacement is required and to agree a budget for contracts that commonly run for three or five years.
Management expects more service contracts to start in the current quarter, with further activity in the following quarter. Alok Kirloskar said this year's margins should recover but would not resemble FY24-25, while the next year should be similar in margin terms. That was a management outlook rather than a numerical FY27 margin target, and it depends on contract mobilisation, material costs and the pace of oil-and-gas execution.
Got a follow-up? Ask IRIS
How did KBL's overseas results compare with domestic operations?
KBL's international revenue rose 24% year on year in Q2 FY27, driven by execution at SPP U.K., SPP USA and the Dutch Group. International EBITDA was Rs 23.3 crore at a 5.3% margin. By comparison, consolidated revenue rose 24% to Rs 1,276.7 crore and consolidated EBITDA increased 16% to Rs 143.2 crore, producing an 11.2% margin.
The domestic standalone business showed a different earnings pattern in Q2 FY27. Revenue grew 23% year on year to Rs 799.1 crore, while EBITDA rose 37% to Rs 93.7 crore and profit after tax increased 45% to Rs 54.4 crore. The faster domestic EBITDA growth contrasts with the international 5.3% margin, where KBL specifically identified the reduced services mix as the main factor.
On a half-year basis, consolidated revenue increased 19% to Rs 2,381.6 crore in H1 FY27, while EBITDA rose 9% to Rs 273.8 crore and the EBITDA margin was 11.5%. The slower growth in EBITDA than revenue is consistent with the overseas margin pressures discussed on the call, although KBL did not disclose a separate UK revenue or EBITDA result for H1 FY27.
KBL's overseas pending order book stood at Rs 1,701.3 crore in September 2026, up 32% year on year. Domestic pending orders were Rs 2,926.4 crore, up 29% year on year and excluding the small-pumps order book. These figures show that both businesses have order visibility, but their margin profiles and execution cycles differ.
What needs to happen for KBL's UK services mix to recover?
KBL said its service framework contracts remain in place and described the issue as a delay in implementation rather than cancellations or a strategic shift. Before contracts start, the company must inspect assets and agree a work programme with the customer. Once that process is complete, annual work can include refurbishment through service centres, repairs or replacement of pumps.
The slower service start affected the UK businesses for their first three calendar-year quarters, or KBL's first two financial-year quarters, according to management. More contract starts would increase the contribution from services, which KBL says is a higher-margin activity. The call did not provide the number or value of service contracts awaiting assessment or mobilisation.
SPP USA has a different demand mix, with KBL citing traction in data centres, fire projects and heating, ventilation and air conditioning projects. KBL did not disclose separate SPP USA profitability. Its inclusion in the Q2 FY27 overseas-revenue commentary indicates that international growth was not limited to the UK, while the 8% material-cost increase and delayed-service discussion were specifically about the UK business.
Conclusion
KBL's UK margin outlook rests on identifiable operating factors rather than a disclosed retreat from services. The company expects the 5.3% international EBITDA margin reported in Q2 FY27 to improve as service work begins, but says 8% UK material-cost inflation, lower-margin oil-and-gas execution and related staffing needs mean FY27 will not match FY25 margin levels.
The next issue to watch is whether the service contracts expected to start in the current and following quarters progress from asset assessments to billable refurbishment, repair and replacement work. Management also expects raw-material effects to moderate over the next few quarters and said the following year should be similar to FY24-25 in margin terms.