










Krishana Phoschem Q2 FY27 profit rises 135% as margins expand
Key highlights
- Krishana Phoschem's Q2 FY27 revenue rose 15.6% year-on-year to ₹702.5 crore.
- Q2 FY27 EBITDA increased 74.1% year-on-year to ₹127.4 crore, while EBITDA margin reached 18.1%.
- Q2 FY27 net profit rose 134.7% year-on-year to ₹77.9 crore.
- H1 FY27 revenue was ₹1,234.8 crore and net profit was ₹125.0 crore, up 23.1% and 96.0% year-on-year, respectively.
powered by IRIS
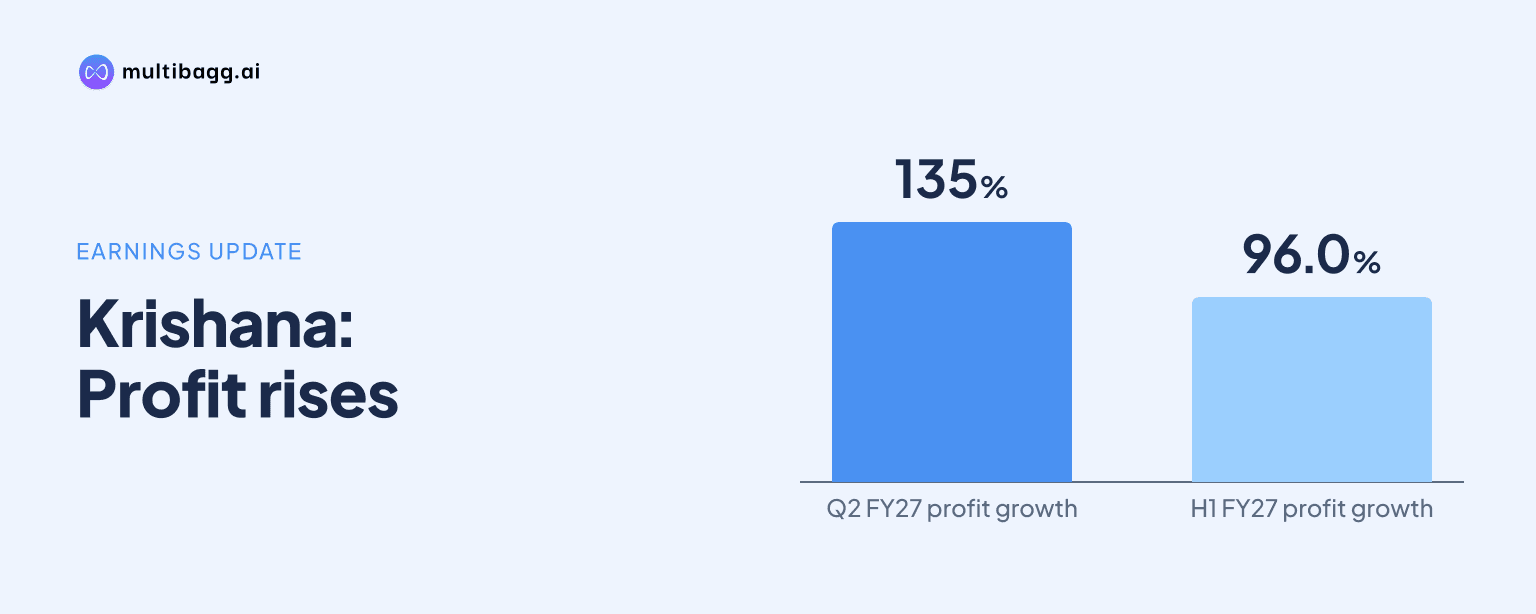
Krishana Phoschem Ltd reported Q2 FY27 net profit of ₹77.9 crore, up 134.7% year-on-year, as revenue rose 15.6% to ₹702.5 crore and EBITDA increased 74.1% to ₹127.4 crore. The September-quarter performance is significant because margin expansion drove profit growth faster than sales growth during the period.
Know Krishana Phoschem inside out
Results, valuation, peers and who's buying, in one view.
What did Krishana Phoschem report in Q2 FY27?
Krishana Phoschem reported standalone revenue from operations of ₹702.5 crore for the quarter ended September 30, 2026, compared with ₹607.9 crore in Q2 FY26. Revenue also increased 32.0% sequentially from ₹532.3 crore in Q1 FY27, indicating a stronger second quarter after the first-quarter level.
Total income was ₹708.2 crore, including other income of ₹5.7 crore. Profit before tax rose 72.3% year-on-year to ₹104.4 crore, while net profit reached ₹77.9 crore from ₹33.2 crore a year earlier. Sequentially, net profit increased 65.3% from ₹47.1 crore in Q1 FY27.
The board approved the unaudited standalone financial results for the quarter and half year ended September 30, 2026, on November 14, 2026. Krishana Phoschem had also filed its investor presentation with the National Stock Exchange of India under the symbol KRISHANA.
Why did Krishana Phoschem's profitability improve?
Krishana Phoschem's profitability improved chiefly because EBITDA rose materially faster than revenue. EBITDA of ₹127.4 crore was ₹54.2 crore higher than the year-earlier quarter, and the EBITDA margin expanded to 18.1% from 12.0%, a gain of 610 basis points.
The investor presentation attributed the half-year performance to an integrated capacity ramp-up. Management described the H1 FY27 outcome as record performance and cited operational resilience. The company reported a Q2 profit after tax margin of 11%, while the detailed results table showed net profit margin of 11.1%.
The results also showed higher financing and depreciation charges compared with the prior-year quarter. Interest cost rose to ₹16.1 crore from ₹6.9 crore, while depreciation increased to ₹12.6 crore from ₹9.1 crore. Even with these higher costs, the gain in operating profit supported the increase in pre-tax and net profit.
How did Krishana Phoschem perform in the first half of FY27?
Krishana Phoschem generated H1 FY27 revenue of ₹1,234.8 crore, up 23.1% from ₹1,003.4 crore in H1 FY26. Net profit for the six months rose 96.0% to ₹125.0 crore from ₹63.7 crore, while the investor presentation reported EBITDA growth of 56% for the period.
The H1 revenue figure is consistent with the company's reported revenue from operations of ₹1,234.85 crore for the half year. The first-half profit growth exceeded revenue growth, extending the margin improvement visible in the September quarter.
However, volumes in two reported product categories were lower during H1 FY27. Single Super Phosphate, or SSP, volumes declined 15% year-on-year, while NPK volumes fell 22%. The presentation nevertheless pointed to demand visibility from the rabi nutrient-based subsidy allocation and higher fertiliser inventory.
Got a follow-up? Ask IRIS
What does the fertiliser market data indicate for Krishana Phoschem?
Krishana Phoschem cited a rabi nutrient-based subsidy allocation of ₹62,370 crore and fertiliser inventory growth of 35.6% year-on-year as supportive demand indicators. These data points provide context for the company's operating environment, although the reported volume declines show that broader inventory conditions did not translate into higher H1 volumes across every product category.
The fertiliser business is influenced by seasonal agricultural demand, inventory positions and subsidy-related policy support. The reported rabi allocation is relevant because it relates to the fertiliser season that follows the September quarter and forms part of the demand backdrop highlighted by management.
For investors, the difference between revenue growth and volume trends is important. Revenue rose in both Q2 and H1, while SSP and NPK volumes declined during H1. The available presentation does not provide a detailed product-wise explanation for this difference, so the reported figures should be assessed alongside future disclosures on volumes, capacity utilisation and product mix.
What should investors note from the financial position and schedule?
Krishana Phoschem's September-quarter results reflected a substantial improvement in earnings, but the reported data also showed increased borrowings. Borrowings were stated at ₹1,233 crore in September 2026, up 199% from September 2025. Interest expense of ₹16.1 crore in Q2 FY27 was also 135% higher year-on-year.
The company has scheduled its Q2 and H1 FY27 earnings call for November 18, 2026. That call may provide further management commentary on the integrated capacity ramp-up, reported volume trends and the factors behind the movement in borrowings. The results filing itself reported no exceptional items in the quarter.
The reported EPS was ₹2.52 in Q2 FY27, compared with ₹5.36 in Q2 FY26, despite the rise in net profit. This is the figure disclosed in the results data and should be read with the company's financial statements and any information it provides on its share capital during the earnings discussion.
Conclusion
Krishana Phoschem delivered stronger Q2 FY27 revenue and a marked rise in profitability, with net profit increasing 134.7% year-on-year to ₹77.9 crore and EBITDA margin reaching 18.1%. The H1 FY27 record revenue of ₹1,234.8 crore and net profit of ₹125.0 crore show that earnings growth continued through the first six months, even as reported SSP and NPK volumes declined.
The next disclosed event is Krishana Phoschem's earnings call on November 18, 2026. Investors will watch for further details on capacity ramp-up, product volumes, fertiliser demand conditions, borrowings and the sustainability of the September-quarter margin improvement.