










Lloyds Metals & Energy Q2 EBITDA Rises 83% to ₹1,538 Crore
Key highlights
- Lloyds Metals reported standalone Q2 FY27 revenue of ₹4,132 crore, up 62% year on year.
- Standalone Q2 FY27 EBITDA rose 83% year on year to ₹1,538 crore.
- Standalone H1 FY27 EBITDA reached ₹3,658 crore, up 126%, with a 38.33% margin.
- The board approved a 360 MW thermal power plant at Konsari, Maharashtra, comprising two 180 MW units.
powered by IRIS
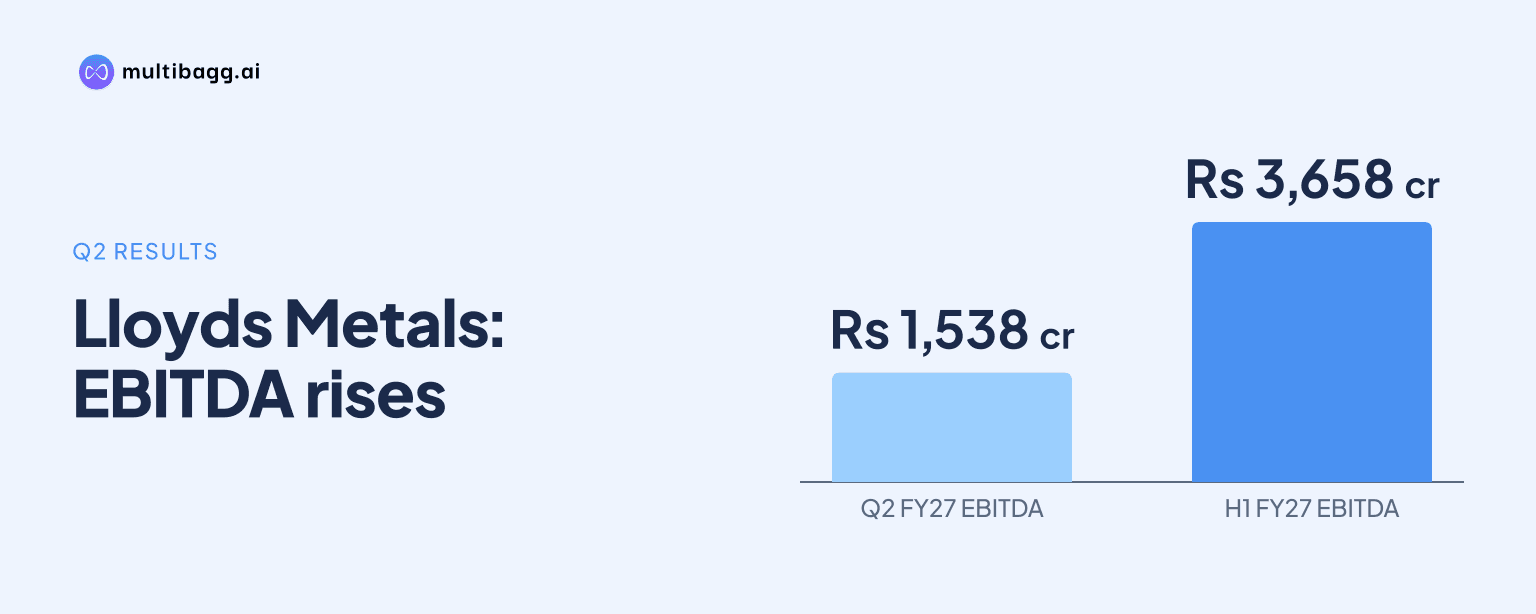
Lloyds Metals & Energy Limited reported standalone Q2 FY27 EBITDA of ₹1,538 crore, up 83% year on year, alongside revenue of ₹4,132 crore, up 62%. The company said higher iron ore EC limits, faster pellet plant ramp-up and improved sponge iron volumes supported the quarterly performance.
Know Lloyds Metals & Energy inside out
Results, valuation, peers and who's buying, in one view.
What did Lloyds Metals report for Q2 FY27?
Lloyds Metals reported standalone revenue from operations of ₹4,132 crore for the quarter ended 30 September 2026, compared with growth of 62% from the year-earlier period. Standalone EBITDA rose 83% year on year to ₹1,538 crore. The company reported a Q2 EBITDA margin of 37.22%, an expansion of 419 basis points year on year.
The company also reported standalone profit after tax of ₹1,111.89 crore in Q2 FY27. On a consolidated basis, net profit was ₹1,023.24 crore and basic earnings per share stood at ₹18.57, compared with ₹11.04 in Q2 FY26. The reported consolidated Q2 EBITDA was ₹1,803.5 crore, up 75% year on year.
Management described the first-half performance as its best-ever H1 margin performance. The earnings update was released after the board approved the standalone and consolidated unaudited results for the quarter and half year ended 30 September 2026 on 3 November 2026.
How did H1 FY27 financial performance compare with last year?
Lloyds Metals reported standalone H1 FY27 revenue of ₹9,545 crore, a 94% year-on-year increase, while EBITDA rose 126% to ₹3,658 crore. The H1 standalone EBITDA margin was 38.33%, up 542 basis points from the comparable period last year.
The consolidated H1 figures also showed strong growth. Consolidated revenue was reported at ₹13,009.01 crore and profit after tax at ₹2,790.98 crore. Consolidated EBITDA for H1 FY27 was ₹4,595.6 crore, up 151% year on year, while basic earnings per share increased to ₹49.28 from ₹23.16 in H1 FY26.
The standalone numbers illustrate that operating profit grew faster than revenue during both reported periods. The margin improvement is important because it indicates that the company retained a larger share of revenue as EBITDA despite operating at a substantially higher scale.
Got a follow-up? Ask IRIS
What drove Lloyds Metals' revenue and margin growth?
Lloyds Metals attributed its H1 FY27 growth to higher iron ore EC limits, a faster-than-planned ramp-up at its pellet plant and improved sponge iron volumes. These operational factors supported higher revenue and EBITDA in the first half of the financial year.
The pellet plant and sponge iron operations are relevant to the company’s ability to convert iron ore into value-added products. Higher volumes from these operations, combined with the stated rise in EC limits for iron ore, were cited by management as the principal reasons for the reported expansion in financial performance.
During the earnings call, Managing Director Rajesh Gupta addressed a question on pricing and said there was no specific benchmark in India, with the price reflecting quality. The company also referred to its BHQ beneficiation initiative, which involves processing hematite quartzite or lower-grade ore that has historically been treated as waste by many Indian mines.
What are the key operational developments investors should track?
Lloyds Metals' board approved a 360 MW thermal power plant at Konsari, Maharashtra, comprising two units of 180 MW each, along with the Q2 and H1 FY27 results. The announcement establishes a new capacity project but the provided disclosures do not specify its investment cost, commissioning schedule or expected financial contribution.
The company hosted its earnings conference call on 4 November 2026 at 3:30 PM, and subsequently made the audio recording available on its website. Lloyds Metals stated that no unpublished price-sensitive information was disclosed during the session, allowing shareholders to review management commentary on the reported results.
For investors, the earnings outcome is notable for the pace of revenue growth and the faster increase in EBITDA. Standalone H1 EBITDA rose 126%, exceeding the 94% rise in revenue, while the H1 margin reached 38.33%. These results were supported by disclosed operating improvements rather than a single stated one-off item.
The planned power plant and beneficiation initiative point to continued operational development across the company’s mining and metals value chain. However, the disclosed information does not provide a target date for the power project or separate financial forecasts for these initiatives.
Conclusion
Lloyds Metals delivered strong standalone operating growth in Q2 and H1 FY27, with EBITDA increasing faster than revenue and margins expanding to 37.22% for Q2 and 38.33% for H1. Management linked the performance to higher iron ore EC limits, pellet plant ramp-up and improved sponge iron volumes.
Investors will watch for further disclosures on the 360 MW Konsari thermal power plant, including project timing and financial details, as well as updates on the BHQ beneficiation initiative. The next reported results and management communication will provide additional evidence on whether the operational drivers cited for H1 FY27 continue.