










Lords Mark forecasts FY29E revenue of Rs 2,586 crore, 25.1% margin
Key highlights
- Lords Mark forecasts FY29E revenue of Rs 2,586 crore, up from Rs 710 crore in FY25.
- Lords Mark projects FY29E EBITDA of Rs 650.36 crore and a 25.1% margin, versus Rs 75 crore and 10.5% in FY25.
- Lords Mark expects IVD revenue to rise from Rs 334 crore in FY25 to Rs 1,117 crore in FY29E.
- Lords Mark projects solar and renewables revenue of Rs 543 crore in FY29E, versus Rs 76 crore in FY25.
powered by IRIS
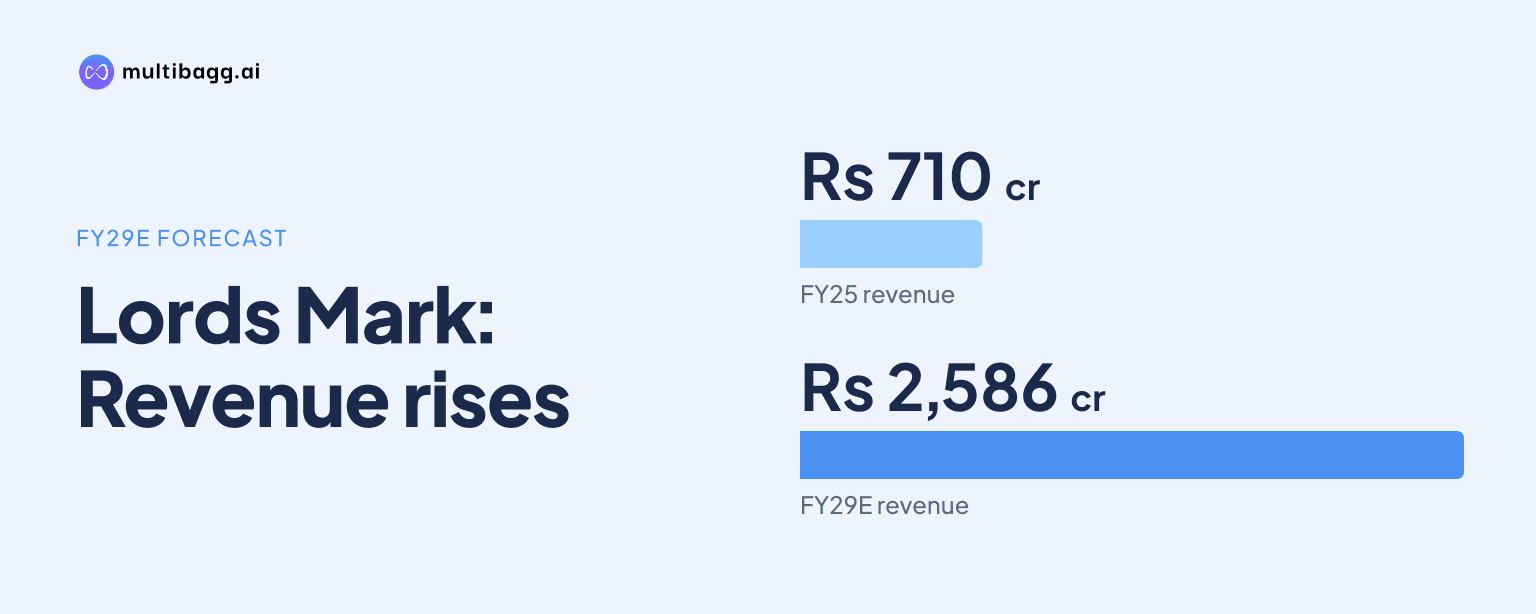
For FY29E, Lords Mark Industries Limited forecasts revenue of Rs 2,586 crore and an EBITDA margin of 25.1%, compared with Rs 710 crore and 10.5% in FY25. The presentation credits Nuvama Wealth Management Limited with the financial analysis and identifies healthcare and renewable energy as the principal drivers of the projected expansion.
Know Lords Mark Industries inside out
Results, valuation, peers and who's buying, in one view.
What is Lords Mark forecasting for FY29E?
Lords Mark forecasts revenue of Rs 2,586 crore in FY29E, a stated 3.6-times increase from Rs 710 crore in FY25. The forecast spans the FY25 to FY29 period and includes FY26P, FY27E and FY28E in the presentation chart. Healthcare and renewable energy are identified as the businesses supporting the projected Rs 1,876 crore increase in revenue.
Lords Mark also projects earnings to increase faster than revenue over the period. Earnings before interest, tax, depreciation and amortisation, or EBITDA, are forecast to rise from Rs 75 crore in FY25 to Rs 650.36 crore in FY29E, or about 8.7 times. Adjusted profit after tax, or adjusted PAT, is projected to increase from Rs 40 crore to Rs 422 crore, which the presentation describes as nearly 10-times growth.
How would Lords Mark's profitability change by FY29E?
Lords Mark projects its EBITDA margin to rise by 1,460 basis points, from 10.5% in FY25 to 25.1% in FY29E. One basis point equals one-hundredth of a percentage point. This margin expansion accompanies projected EBITDA growth of Rs 575.36 crore, compared with the Rs 1,876 crore increase in revenue over the same FY25 to FY29E period.
Lords Mark also forecasts return on capital employed, or ROCE, of 25% in FY29E, versus 12% in FY25, and diluted earnings per share, or EPS, of Rs 9.50, versus Rs 1.07. The metric table describes the EPS increase as about nine times, while a chart caption calls it nearly six-times earnings accretion. The presentation therefore contains two different descriptions of the same FY25-to-FY29E EPS change.
Which businesses are expected to drive Lords Mark's growth?
Lords Mark expects in-vitro diagnostics, or IVD, to become its largest segment by FY29E, with revenue rising from Rs 334 crore in FY25 to Rs 1,117 crore. The segment includes diagnostics, biochemistry, analysers and reagents. Its projected Rs 783 crore increase is the largest stated expansion for an individual business and supports the presentation's expectation that healthcare will contribute more than half of incremental revenue growth.
Lords Mark's Renalcare dialysis business is scheduled to fully launch in FY27 at Rs 62 crore and is projected to reach Rs 294 crore by FY29E. The presentation assigns Renalcare an EBITDA margin range of 25% to 50%. MedTech is shown at Rs 8 crore in FY27 and Rs 175 crore in FY29E, with an approximately 34% EBITDA margin, while the Rs 75 crore paper business is to be discontinued after FY25.
Lords Mark also projects lighting and renewables to remain a second revenue pillar. Combined revenue from those businesses is forecast to rise from Rs 301 crore in FY25 to Rs 1,000 crore in FY29E. Within the total, lighting is projected to grow from Rs 225 crore to Rs 457 crore, while solar and renewables are expected to rise from Rs 76 crore to Rs 543 crore, a stated 3.3-times increase for solar.
Got a follow-up? Ask IRIS
What plans and risks underpin Lords Mark's FY29E outlook?
Lords Mark's FY2026-27 roadmap includes a proposed National Stock Exchange listing, partnerships for a global footprint in the European Union, United States and Gulf Cooperation Council countries, and an independent research and development team in India. It also lists a proposed follow-on public offer or preferential allotment of Rs 500 crore. For FY2027-28, the roadmap targets a MedTech manufacturing unit, 2,000 pathology laboratories, 1,000 Renal Care Units and execution of an IVD/MedTech demerger.
Lords Mark identifies regulatory approval timing, government payment cycles, manufacturing and clinic rollout execution, and competition from global diagnostics and MedTech companies as risks. The presentation names approvals from the Central Drugs Standard Control Organisation, the US Food and Drug Administration and CE processes. Its stated mitigations include an in-house regulatory team, phased capital expenditure, a diversified public-sector client base, a growing export and private-sales mix, and in-house project execution as Renalcare targets Rs 294 crore by FY29E.
Conclusion
The FY25-to-FY29E forecast describes a shift in Lords Mark's projected scale and business mix. Revenue is forecast to rise from Rs 710 crore to Rs 2,586 crore, EBITDA from Rs 75 crore to Rs 650.36 crore, and EBITDA margin from 10.5% to 25.1%. IVD provides the largest stated revenue increase, while dialysis and MedTech are expected to add healthcare revenue with higher stated segment margins.
The next disclosed milestones are the FY2026-27 proposed Rs 500 crore capital raise and exchange-listing plan, followed in FY2027-28 by the targets for 2,000 pathology laboratories, 1,000 Renal Care Units and the IVD/MedTech demerger. Progress on regulatory approvals, customer payment collections, manufacturing capacity and clinic rollout will remain relevant to the FY29E targets.