










Mangalam Organics Q2 revenue rose 78%, profit stayed flat
Key highlights
- Mangalam Organics reported Q2 FY27 revenue of Rs 281.46 crore, up 78.03% from Rs 158.10 crore in Q2 FY26.
- Mangalam Organics' Q2 FY27 gross profit margin declined to 29.5% from 35.1% a year earlier.
- Mangalam Organics' Q2 FY27 EBITDA was Rs 21.55 crore, compared with Rs 0.28 crore in Q2 FY26.
- Mangalam Organics reported Q2 FY27 profit for the year of Rs 3.20 crore, unchanged year on year, with PAT margin at 1.14%.
powered by IRIS
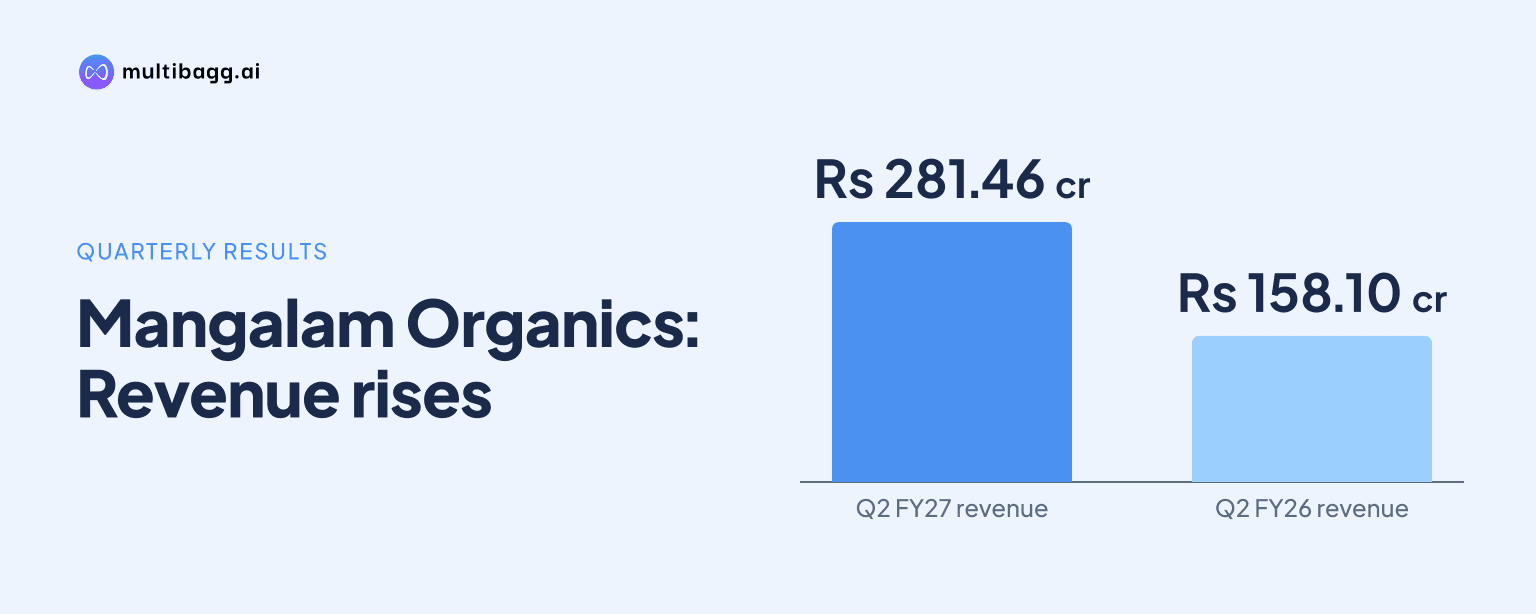
Mangalam Organics Limited reported Q2 FY27 revenue from operations of Rs 281.46 crore, up 78.03% from Q2 FY26, while profit for the year remained Rs 3.20 crore in the detailed statement. Gross profit margin fell to 29.5% from 35.1%, and PAT margin declined to 1.14% from 2.02%, limiting the conversion of sales growth into net profit.
Know Mangalam Organics inside out
Results, valuation, peers and who's buying, in one view.
Why did Mangalam Organics' profit stay flat despite higher revenue?
Mangalam Organics recorded profit for the year of Rs 3.20 crore in both Q2 FY27 and Q2 FY26, according to its detailed consolidated profit and loss statement, even as revenue increased by Rs 123.36 crore from Rs 158.10 crore. The presentation summary separately lists PAT of Rs 3.02 crore for both quarters, but both source disclosures show no year-on-year increase in quarterly profit.
The movement below operating profit explains the outcome. Earnings before interest and tax, or EBIT, declined 4.08% to Rs 14.09 crore from Rs 14.69 crore, although earnings before interest, tax, depreciation and amortisation, or EBITDA, rose to Rs 21.55 crore from Rs 0.28 crore. Other income fell to Rs 17.25 lakh from Rs 20.54 crore, while depreciation and amortisation increased to Rs 7.51 crore from Rs 6.13 crore and finance costs rose to Rs 9.09 crore from Rs 6.99 crore.
How did Mangalam Organics' margins change in Q2 FY27?
Mangalam Organics' gross profit margin declined to 29.5% in Q2 FY27 from 35.1% in Q2 FY26, a 5.6-percentage-point reduction. Gross profit increased 49.62% to Rs 83.07 crore, but this was slower than the 78.03% increase in revenue. Cost of materials consumed more than doubled to Rs 199.45 crore from Rs 99.67 crore, increasing faster than sales.
EBITDA margin moved in the opposite direction year on year, rising to 7.66% from 0.18%, or by 748 basis points. A basis point is one-hundredth of a percentage point. EBITDA increased by Rs 21.27 crore as the Rs 27.55 crore increase in gross profit exceeded the combined rise in employee benefits and other expenses.
The quarter was less profitable than Q1 FY27 on both operating and net-margin measures. EBITDA margin was 12.40% in Q1 FY27, compared with 7.66% in Q2 FY27, while PAT margin fell from 4.06% to 1.14%. Revenue rose 57.16% sequentially from Rs 179.09 crore to Rs 281.46 crore, but profit for the year declined 55.98% from Rs 7.27 crore to Rs 3.20 crore.
What operating costs changed for Mangalam Organics in Q2 FY27?
Mangalam Organics' material consumption was Rs 199.45 crore in Q2 FY27, compared with Rs 99.67 crore in Q2 FY26 and Rs 122.89 crore in Q1 FY27. Changes in inventories of finished goods, work in progress and stock-in-trade were negative Rs 1.15 crore in Q2 FY27, versus negative Rs 1.03 crore a year earlier and negative Rs 19.97 crore in the immediately preceding quarter.
Employee benefits expense increased to Rs 14.13 crore from Rs 12.08 crore, while other expenses rose to Rs 47.39 crore from Rs 43.16 crore. Together, these two expense lines totalled Rs 61.52 crore in Q2 FY27, up Rs 6.28 crore from Q2 FY26. That increase was lower than the Rs 27.55 crore increase in gross profit, producing EBITDA of Rs 21.55 crore.
Purchases of stock in trade fell to Rs 9 lakh in Q2 FY27 from Rs 3.94 crore in Q2 FY26, while gross profit nevertheless lagged revenue growth. The presentation does not provide product, customer or segment disclosures for the quarter, so it does not identify which business activity drove the increase in material consumption or the lower gross margin.
Got a follow-up? Ask IRIS
How did other income and exceptional items affect Mangalam Organics' comparison?
Mangalam Organics reported Rs 17.25 lakh of other income in Q2 FY27, versus Rs 20.54 crore in Q2 FY26. This helps explain why EBIT was Rs 14.09 crore in Q2 FY27, below Rs 14.69 crore a year earlier, despite EBITDA increasing from Rs 0.28 crore to Rs 21.55 crore. The source’s reported EBIT incorporates the materially different other-income contributions.
The year-earlier quarter also carried an exceptional loss of Rs 3.50 crore, while Q2 FY27 reported no exceptional loss. Profit before tax before exceptional items was Rs 5 crore in Q2 FY27, compared with Rs 7.70 crore in Q2 FY26. After the exceptional loss, profit before tax was Rs 5 crore versus Rs 4.18 crore, but tax expense increased to Rs 1.80 crore from Rs 98 lakh.
Earnings per share were Rs 3.74 in Q2 FY27 and Rs 3.73 in Q2 FY26, broadly matching the unchanged profit reported in the detailed statement. In Q1 FY27, earnings per share were Rs 8.49 alongside Rs 7.27 crore of profit for the year. The sequential comparison therefore shows a lower net-profit outcome even as quarterly revenue reached Rs 281.46 crore.
How does Mangalam Organics' Q2 FY27 compare with FY26?
Mangalam Organics reported FY26 revenue from operations of Rs 622.57 crore, up 17.46% from Rs 530.01 crore in FY25. FY26 EBITDA rose 49.91% to Rs 87.82 crore and profit for the year increased 103.04% to Rs 25.38 crore. Management attributed the annual improvement to a decrease in input costs and said it continued efforts to improve efficiencies and margins.
FY26 gross profit margin was 47.3%, compared with 48.4% in FY25, while EBITDA margin increased to 14.11% from 11.05% and PAT margin rose to 4.08% from 2.36%. Q2 FY27's 29.5% gross margin, 7.66% EBITDA margin and 1.14% PAT margin were below the FY26 figures. These are comparisons between a single quarter and a full year, rather than like-for-like periods.
At March 2026, Mangalam Organics had total borrowings of Rs 356 crore, comprising Rs 55 crore of non-current borrowings and Rs 301 crore of current borrowings. That was Rs 87 crore higher than Rs 269 crore at March 2025. FY26 finance costs increased to Rs 28.19 crore from Rs 21.48 crore, while net cash from operating activities was Rs 91 lakh after negative Rs 85.85 crore of working-capital changes.
Conclusion
Mangalam Organics delivered a large Q2 FY27 revenue increase and a substantial year-on-year rise in EBITDA, but gross profit did not keep pace with sales and detailed quarterly profit remained unchanged. The lower gross margin, sharply reduced other income, higher depreciation and higher finance costs resulted in PAT margin falling to 1.14% despite revenue of Rs 281.46 crore.
The next disclosures should show whether management’s stated focus on operational efficiencies and margins changes the Q2 FY27 profile of 29.5% gross margin, 7.66% EBITDA margin and 1.14% PAT margin. Investors can also watch finance costs after March 2026 borrowings reached Rs 356 crore and the FY26 operating cash flow outcome of Rs 91 lakh.