










Manipal Sahyadri margin reaches 19.5% as digital share rises
Key highlights
- Sahyadri’s EBITDA margin reached 19.5% in Q2 FY27, versus 17.5% in Q1 FY27 and 15.5% in FY26.
- Sahyadri reported Rs 375 crore of Q2 FY27 revenue and Rs 73 crore of EBITDA, up 13% and 26% sequentially respectively.
- Digital channels generated 11% of Sahyadri revenue in Q2 FY27, compared with about 1% before the cited integration work.
- Manipal plans to add around 50 beds at Sahyadri’s Hadapsar facility in Q3 FY27.
powered by IRIS
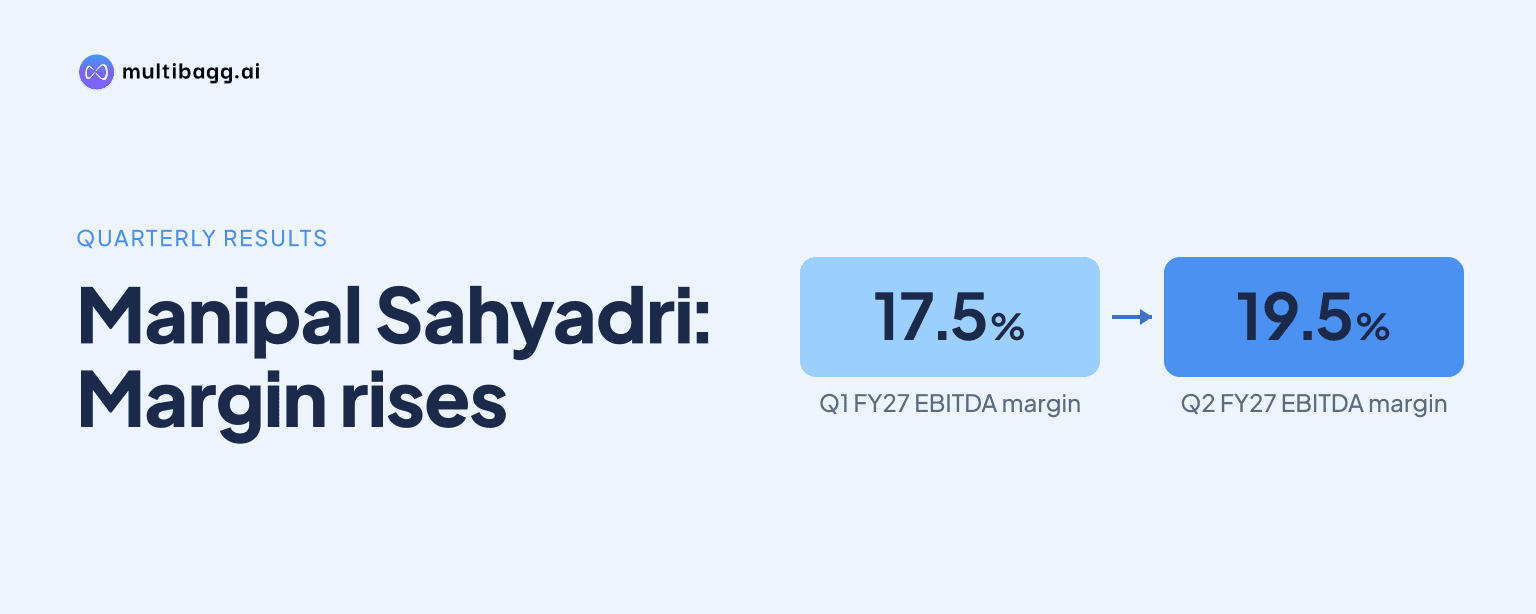
Manipal Health Enterprises Limited said Sahyadri’s EBITDA margin reached 19.5% in Q2 FY27, rising from 17.5% in Q1 FY27 and 15.5% in FY26, as revenue increased 13% sequentially to Rs 375 crore and digital channels accounted for 11% of revenue. EBITDA rose 26% sequentially to Rs 73 crore.
Know Manipal Health Enterprises inside out
Results, valuation, peers and who's buying, in one view.
How much did Manipal improve Sahyadri’s profitability?
Manipal improved Sahyadri’s EBITDA margin to 19.5% in Q2 FY27, more than 200 basis points above the 17.5% reported in Q1 FY27. The Q2 margin was also 4 percentage points above Sahyadri’s 15.5% margin for the full FY26, indicating a changed earnings outcome over successive reported periods.
Sahyadri reported Rs 375 crore of revenue and Rs 73 crore of EBITDA in Q2 FY27. Revenue increased 13% quarter on quarter, while EBITDA increased 26%, meaning EBITDA grew faster than sales during the quarter. Management did not provide a separate rupee breakdown of the contribution from each integration measure.
For H1 FY27, Sahyadri recorded revenue of Rs 707 crore, up 18% year on year, and EBITDA of Rs 131 crore, up 24%. Thus, first-half EBITDA growth exceeded revenue growth by 6 percentage points. Manipal described the Q2 result as evidence that its integration approach was beginning to produce results.
What drove Manipal’s Sahyadri margin increase?
Manipal attributed the Q2 FY27 margin increase to procurement synergies, higher-complexity work, clinician hiring, digital revenue and operating efficiencies. Management said Sahyadri had been an under-leveraged asset with multiple opportunities rather than a business with a single identified cost-saving lever.
Digital revenue represented 11% of Sahyadri revenue in Q2 FY27, compared with about 1% before the integration work management described. Manipal said it created 300 doctor profiles online, seeking to improve discovery as healthcare decisions increasingly move to web-based channels. The company did not disclose digital revenue in rupees or the conversion rate from those profiles.
Manipal also said a senior liver-transplant team, including 42 clinicians, joined Sahyadri from November 1. Management expects hepatobiliary and transplant activity to rise after the team’s arrival, but did not give a revenue target, capital expenditure figure or timetable for the programme’s financial contribution.
Why did Sahyadri’s ARPOB decline in Q2 FY27?
Sahyadri’s average revenue per occupied bed per day, or ARPOB, fell 2% sequentially to Rs 44,100 in Q2 FY27 from Rs 45,000 in Q1 FY27. Management attributed the movement to a higher medical-case mix during a febrile period in Pune and elsewhere, rather than to a specific pricing issue.
Management said the medical-case mix increased average length of stay slightly, which affected ARPOB. Sahyadri’s occupancy nevertheless reached 67% in Q2 FY27, while quarterly revenue rose 13% sequentially to Rs 375 crore. The call did not disclose Sahyadri’s exact length of stay, specialty-wise revenue or patient-volume count.
Sahyadri’s 19.5% Q2 FY27 margin remained below Manipal’s wider network EBITDA margin of 26%, including Sahyadri, and 27%, excluding Sahyadri. This comparison shows that Sahyadri’s profitability improved from FY26 and Q1 FY27, but was still below the margin reported for the broader hospital network.
Got a follow-up? Ask IRIS
Is Manipal adding capacity at Sahyadri?
Manipal plans to add around 50 beds at Sahyadri’s Hadapsar facility in Q3 FY27, after adding no Sahyadri beds in Q2 FY27. Management said the Nashik Lenad block had been added in March, making Hadapsar the next specifically disclosed capacity expansion for the Pune cluster.
The planned 50-bed Hadapsar addition comes alongside the liver-transplant team’s November 1 arrival and management’s effort to expand higher-acuity programmes. Management also said it was seeking to bring Sahyadri real-estate spaces up to Manipal standards, but did not specify the capital spending, opening date or capacity associated with those projects.
Insurance rate revisions continue under Sahyadri’s existing contracts and in line with contractual inflation, management said. Sahyadri Hospitals Private Limited remains the legal entity, so management said a Manipal-brand benefit in insurance negotiations would more likely be considered in a later cycle after rebranding and legal-entity changes are completed.
How does Sahyadri fit into Manipal’s FY27 performance?
Manipal’s network reported Q2 FY27 revenue of about Rs 3,400 crore, up more than 37% year on year, and EBITDA of Rs 882 crore, up about 30%. Network occupancy increased to 70% in Q2 FY27 from 65% in Q1 FY27, while Sahyadri delivered its 19.5% margin on 67% occupancy.
For H1 FY27, Manipal reported Rs 6,490 crore of revenue, up about 38% year on year, and Rs 1,631 crore of network EBITDA, up 28%. Digital revenue contributed nearly 23% of group revenue in H1 FY27, above Sahyadri’s 11% Q2 share, although the disclosed periods are not directly identical.
Manipal said its centres of excellence contributed 64.2% of H1 FY27 revenue, with oncology, neurology and orthopaedics among specialties growing about 43%. The company did not provide a Sahyadri-specific split for these specialties, but cited higher-complexity programmes as one mechanism in the acquired chain’s margin improvement.
Conclusion
Sahyadri’s Q2 FY27 results show a measurable early change in profitability: revenue rose 13% sequentially, EBITDA rose 26% and margin reached 19.5%, compared with 17.5% in Q1 FY27 and 15.5% in FY26. Management linked the outcome to procurement, digital conversion, clinician additions, complex-care programmes and operating efficiency rather than revenue growth alone.
The next disclosed milestones are the addition of around 50 beds at Hadapsar in Q3 FY27 and the ramp-up of the transplant programme after the November 1 joining of 42 clinicians. Management also said rebranding and legal-entity changes remain unresolved steps before any potential change in the cycle for insurance-contract negotiations.