










MobiKwik Q2 PAT reaches Rs 11.8 crore as margins expand
Key highlights
- MobiKwik reported Q2 FY27 PAT of Rs 11.8 crore, versus a Rs 28.6 crore loss in Q2 FY26.
- Contribution profit increased 50% year on year to Rs 143.9 crore and contribution margin reached 48%.
- Platform GMV, including Zaakpay, rose 35% year on year to Rs 59,700 crore.
- Lending disbursals increased 47% quarter on quarter to Rs 1,082.6 crore.
powered by IRIS
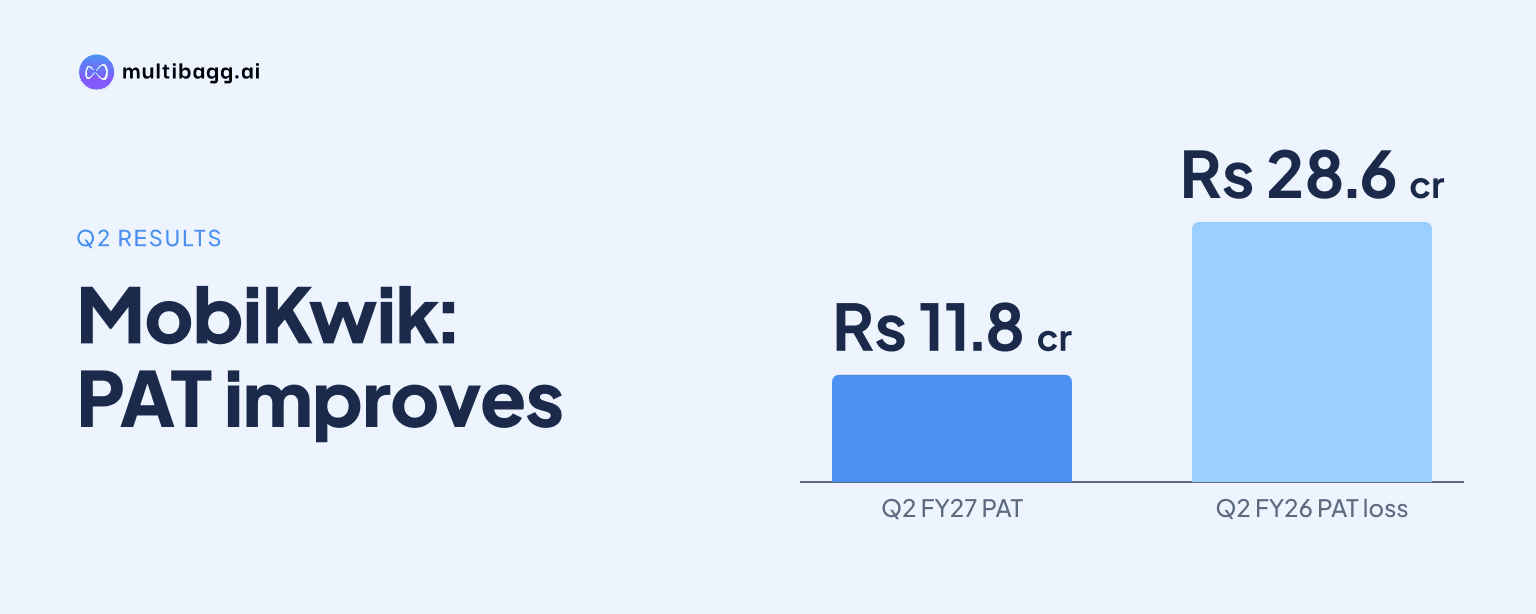
One MobiKwik Systems Limited reported profit after tax (PAT) of Rs 11.8 crore in Q2 FY27, its fourth consecutive PAT-positive quarter, versus a Rs 28.6 crore loss a year earlier. MobiKwik’s July-September 2026 result was supported by a 50% year-on-year rise in contribution profit to Rs 143.9 crore and a contribution margin of 48%.
Know One Mobikwik Systems inside out
Results, valuation, peers and who's buying, in one view.
How did MobiKwik return to profit in Q2 FY27?
MobiKwik returned to profit through higher contribution profit and operating leverage, with Q2 FY27 PAT reaching Rs 11.8 crore against a loss of Rs 28.6 crore in Q2 FY26. That represents a reported year-on-year swing of Rs 40.4 crore, while PAT rose 55% quarter on quarter and carried a 3.9% margin in the September 2026 quarter.
MobiKwik’s earnings before interest, taxes, depreciation and amortisation (EBITDA) was Rs 22.7 crore, equal to a 7.5% margin, compared with an EBITDA margin of negative 2.3% in Q2 FY26. EBITDA also increased 44% from Q1 FY27, when the company said higher contribution profit exceeded the increase in fixed costs.
MobiKwik said its Q2 PAT had no exceptional item, making the result a measure of reported operating performance rather than a one-off gain. It also corrected basic and diluted earnings per share for the quarter ended September 30, 2026 to Rs 1.50 from the Rs 0.75 figure previously uploaded in error, and said the correction did not affect its financial position or performance.
Which margins drove MobiKwik’s earnings improvement?
MobiKwik’s contribution margin rose to 48% in Q2 FY27 from 34% in Q2 FY26, a reported expansion of 1,314 basis points, where one basis point is one-hundredth of a percentage point. Contribution profit consequently increased Rs 47.8 crore year on year to Rs 143.9 crore, faster than total revenue growth of 8% to Rs 302.8 crore.
Payments gross profit rose 30% year on year to Rs 79.8 crore, while the payments gross margin increased to 38.2% from 29.4%, an 884-basis-point change. MobiKwik attributed the improvement to a 13% year-on-year reduction in payment-related direct costs, even as platform gross merchandise value (GMV), including Zaakpay payment-gateway volumes, grew 35%.
Financial services produced the sharper margin change. Its gross profit grew 123% year on year to Rs 57.1 crore and gross margin reached 65.7%, compared with 41.8% a year earlier and 59% in Q1 FY27. Lending-related expenses fell 16% year on year to Rs 29.8 crore, or 2.76% of disbursals, from Rs 35.7 crore and 4.42% of disbursals in Q2 FY26.
MobiKwik said direct costs fell 13% year on year while platform GMV rose 35% and lending disbursals increased 34%. Fixed costs were Rs 121.2 crore, or 40.0% of income, within management’s stated 38% to 40% range while it expands merchant businesses; research and development cost rose 4% to Rs 10.8 crore, including device deployments and working-capital spending.
Got a follow-up? Ask IRIS
How did MobiKwik’s payments and lending businesses perform?
MobiKwik’s payments business recorded platform GMV of Rs 59,700 crore in Q2 FY27, up from Rs 44,100 crore a year earlier, marking its 15th consecutive record quarter. Merchant GMV grew 76% year on year and 18% quarter on quarter to Rs 13,300 crore, increasing its share of platform GMV to 22% from 17% a year earlier.
Consumer GMV grew 27% to Rs 46,400 crore, while Unified Payments Interface (UPI) GMV increased 42% year on year to Rs 24,700 crore. UPI value declined from Rs 26,900 crore in Q1 FY27, which MobiKwik attributed to seasonally softer industry activity in Q2 and its focus on higher-quality users and merchant-facing flows. Payments revenue was flat year on year at Rs 208.8 crore, but merchant revenue rose 150% year on year and 29% quarter on quarter.
Lending GMV, representing ZIP EMI disbursals, rose 34% year on year and 47% quarter on quarter to Rs 1,082.6 crore after a temporary Q1 decline linked to a technology migration. MobiKwik completed the transfer of its digital lending business to wholly owned subsidiary MDSPL in August 2026. Financial-services revenue rose 42% year on year and 18% quarter on quarter to Rs 86.9 crore.
AI-led pre-approved offers to segments of 96 million engaged users generated about Rs 200 crore of Q2 disbursals, or around 18% of the total. MobiKwik had 11 lending partners after adding two during the quarter, and partners added in H1 FY27 supplied 20% to 25% of Q2 disbursals. The top-three lender concentration declined to 71% from 91% a year earlier.
What does MobiKwik expect for FY27 and beyond?
MobiKwik reiterated its FY27 guidance for PAT of Rs 40 crore and EBITDA of Rs 75 crore after reporting H1 FY27 PAT of Rs 19.5 crore and EBITDA of Rs 38.5 crore. Those first-half figures represent about half of each full-year target, while Q2 PAT rose 55% from Q1 FY27.
Management said it may use any headroom within those targets for planned growth investments rather than raising guidance. It also cautioned that quarterly profitability may not be linear because of continued merchant-payments investment, although it expects GMV and revenue in both businesses to grow while fixed costs remain anchored.
In lending, the Reserve Bank of India issued MobiKwik a final certificate of registration for its non-banking financial company on November 6, 2026. Management expects to launch the operation within three to six months, capitalising it in stages and using co-lending with banks and larger non-banking financial companies to limit on-book exposure. In merchant payments, management continues to expect the business to break even by FY28.
Conclusion
MobiKwik’s Q2 FY27 PAT of Rs 11.8 crore coincided with a 14-percentage-point increase in contribution margin to 48%, rather than being driven solely by the 8% increase in revenue. Payments contributed Rs 79.8 crore of gross profit and financial services contributed Rs 57.1 crore, with both businesses reporting higher gross margins and lower direct-cost intensity.
The next measures to watch are progress toward management’s FY27 targets of Rs 40 crore in PAT and Rs 75 crore in EBITDA, alongside the planned non-banking financial company launch within three to six months of November 6, 2026. Management’s expected transition toward more distribution-led lending and its FY28 merchant break-even objective will also affect the mix between growth, capital use and margins.