










NHPC says internal accruals can fund Rs 1.11 lakh crore capex
Key highlights
- NHPC estimated Rs 40,000 crore of equity needs within its Rs 1.11 lakh crore capex plan for the next 10 years.
- Management said internal resources of about Rs 4,000 crore a year can cover the average annual equity requirement.
- NHPC has a Rs 14,300 crore capex target for the current year and had achieved about Rs 6,500 crore at the time of the call.
- NHPC expects EBITDA to rise from about Rs 6,000 crore to Rs 7,000 crore currently to about Rs 10,000 crore after commissioning.
powered by IRIS
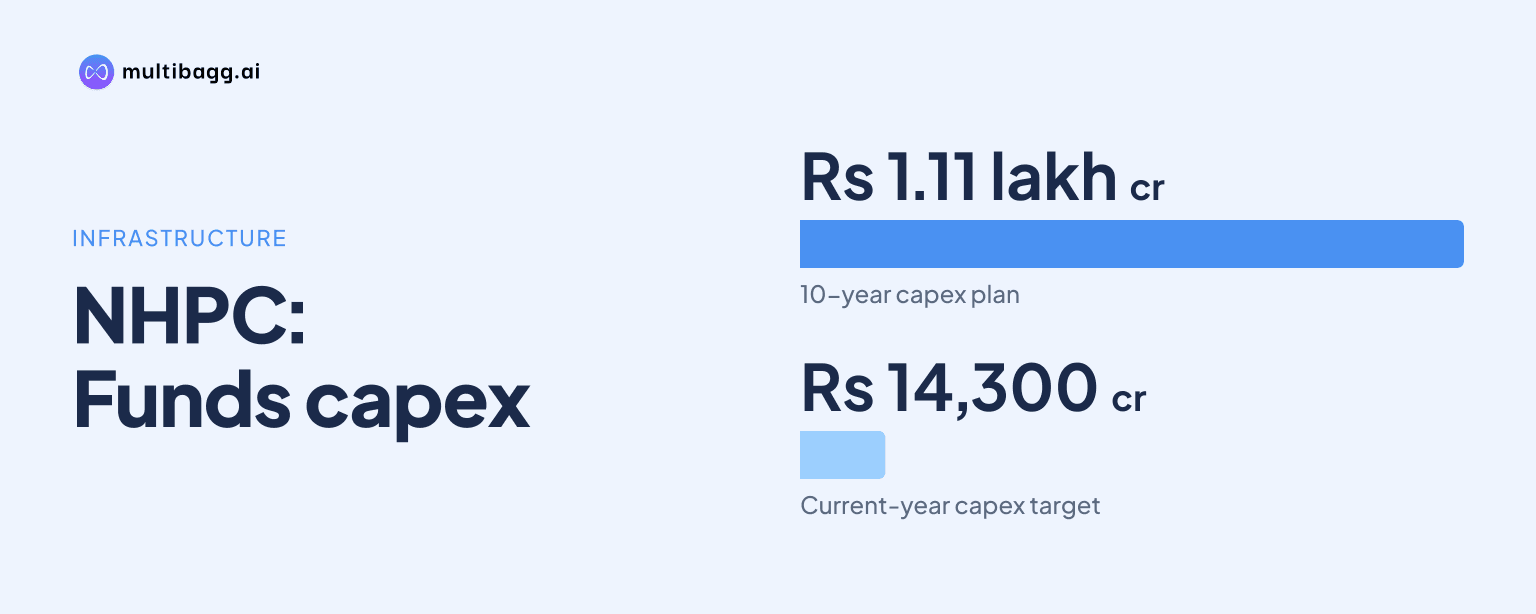
NHPC said internal accruals can fund the roughly Rs 4,000 crore average annual equity requirement within its Rs 1.11 lakh crore consolidated capital-expenditure plan for the next 10 years, without fresh equity, based on management’s FY28 illustration of about Rs 10,000 crore in cash generation.
Know NHPC inside out
Results, valuation, peers and who's buying, in one view.
How will NHPC fund its Rs 1.11 lakh crore capex plan?
NHPC plans to meet the equity component of its 10-year capital-expenditure plan through internal resources rather than a fresh equity issue. Management put consolidated capex at about Rs 1.11 lakh crore for the next 10 years and estimated the required equity at about Rs 40,000 crore, equal to roughly Rs 4,000 crore annually.
Management based that assessment on an FY28 cash-generation illustration. It is targeting profit after tax, or PAT, of Rs 6,000 crore to Rs 6,400 crore by FY28, alongside depreciation of Rs 3,000 crore to Rs 3,500 crore. Using the lower PAT assumption of Rs 6,000 crore, management said total cash generation would be about Rs 10,000 crore.
From that illustrative cash pool, management allocated about Rs 1,800 crore for dividends and Rs 2,800 crore to Rs 3,000 crore for debt repayment. It said about Rs 4,000 crore or more would remain for capex after those obligations, matching its average annual equity requirement. This is management’s projection rather than a disclosed financing commitment.
What capex level is NHPC targeting each year?
NHPC has set a consolidated capex target of Rs 14,300 crore for the current financial year and expects about Rs 14,000 crore to Rs 15,000 crore annually from next year. Management said it had achieved about Rs 6,500 crore at the time of the call and expected better capex utilisation in the second half.
The current target follows a higher-than-target outcome in the prior year. NHPC said it had targeted Rs 13,000 crore of capex last year and achieved about Rs 13,700 crore, compared with the current Rs 14,300 crore target. The Rs 14,000 crore to Rs 15,000 crore projected annual range is therefore broadly aligned with the current target.
The planned annual capex is larger than the estimated Rs 4,000 crore annual equity contribution because management described the Rs 4,000 crore as only the equity portion. NHPC said its construction activity is financed through its balance sheet, with debt also supporting the overall project outlay.
Why does NHPC expect cash generation to increase by FY28?
NHPC expects commissioning of hydro projects to lift earnings before interest, taxes, depreciation and amortisation, or EBITDA, from about Rs 6,000 crore to Rs 7,000 crore currently to about Rs 10,000 crore. Management linked that increase to a full-year contribution from Subansiri Lower and to commissioning of projects including Pakal Dul.
For the current year, management said 1,744 megawatts, or MW, of capacity would be commissioned. It cited 500 MW already commissioned at Subansiri, 624 MW at Kiru and 120 MW at Rangit, while the listed projects total 1,244 MW and the transcript did not explain the remaining 500 MW within the stated 1,744 MW total.
Management’s later schedule includes 250 MW at Subansiri and 1,000 MW at Pakal Dul in FY28, followed by 1,390 MW in FY29 and 1,000 MW in FY30. It said these additions would contribute to EBITDA, revenue and profit, although it did not provide project-level EBITDA or cash-flow targets.
The quarterly profitability commentary showed the earnings effect of commissioned assets. Parbati-II moved from a Rs 164 crore loss in the comparable prior-year quarter to Rs 215 crore profit before tax, or PBT, in the quarter discussed. Management said Parbati-II added about Rs 380 crore year on year, while Parbati-II and Parbati-III together added Rs 460 crore of incremental PBT.
Got a follow-up? Ask IRIS
How does NHPC assess its Rs 59,000 crore debt balance?
NHPC said group-level debt was about Rs 59,000 crore, with about Rs 29,000 crore deployed in operational projects and about Rs 20,000 crore in projects under construction. Management said debt servicing should be assessed by separating the operating-project debt from borrowing used for assets that are still being built.
The stated Rs 29,000 crore operational allocation and Rs 20,000 crore construction allocation add to about Rs 49,000 crore, leaving about Rs 10,000 crore unclassified against the cited group debt of Rs 59,000 crore. The transcript does not reconcile that difference or identify its accounting classification.
Management said NHPC uses balance-sheet financing rather than project financing. It said construction debt is refinanced as repayments fall due, while operating cash flow services debt deployed in operational projects. Management did not provide borrowing costs, maturities or the sources of future refinancing in this discussion.
Are receivables supporting NHPC’s internal-funding plan?
NHPC said billed receivables were Rs 1,159 crore as of 3 November, of which only Rs 6 crore had been outstanding for more than 45 days. This compared with approximately Rs 4,300 crore reported as of 30 September 2026 during the call discussion.
Management attributed collections to the Electricity Late Payment Surcharge Rules introduced in 2023. It said beneficiaries may face power regulation after 75 days and cannot approach power exchanges, adding that no billed dues were pending beyond 75 days at the time of the call.
Subansiri Lower revenue was not included in the reported approximately Rs 4,300 crore receivables because it was recorded as unbilled debtors, or contract assets, management said. Parbati-II had an interim order allowing 75% billing, meaning the billed-receivables figure does not by itself show the cash conversion of Subansiri Lower revenue.
Conclusion
NHPC’s funding case combines a Rs 1.11 lakh crore, 10-year capex projection with management’s expectation that internal resources can supply about Rs 4,000 crore of annual equity. The plan depends on its FY28 cash-generation illustration, the projected increase in EBITDA to about Rs 10,000 crore, and the distinction management draws between operating-project debt service and refinancing for construction projects.
The next measures to watch are progress against the Rs 14,300 crore current-year capex target, commissioning of 250 MW at Subansiri and 1,000 MW at Pakal Dul in FY28, and movement toward the FY28 PAT target of Rs 6,000 crore to Rs 6,400 crore. Clarification of the difference between the Rs 59,000 crore group debt figure and the Rs 49,000 crore operational and construction split would also add detail to the financing explanation.