










Orient Green Power Company Limited H1 comparable profit rises
Key highlights
- OGPL reported H1 FY27 PAT of Rs 105.51 crore, compared with Rs 109.56 crore in the prior-year period.
- H1 FY27 total income rose 2% to Rs 232.81 crore and EBITDA increased 4% to Rs 176.56 crore.
- The prior-year H1 result included a Rs 16 crore exceptional refund of excess interest paid in earlier years.
- OGPL commissioned 17.6 megawatts of solar capacity on September 26, 2026, taking total solar capacity to 24.6 megawatts.
powered by IRIS
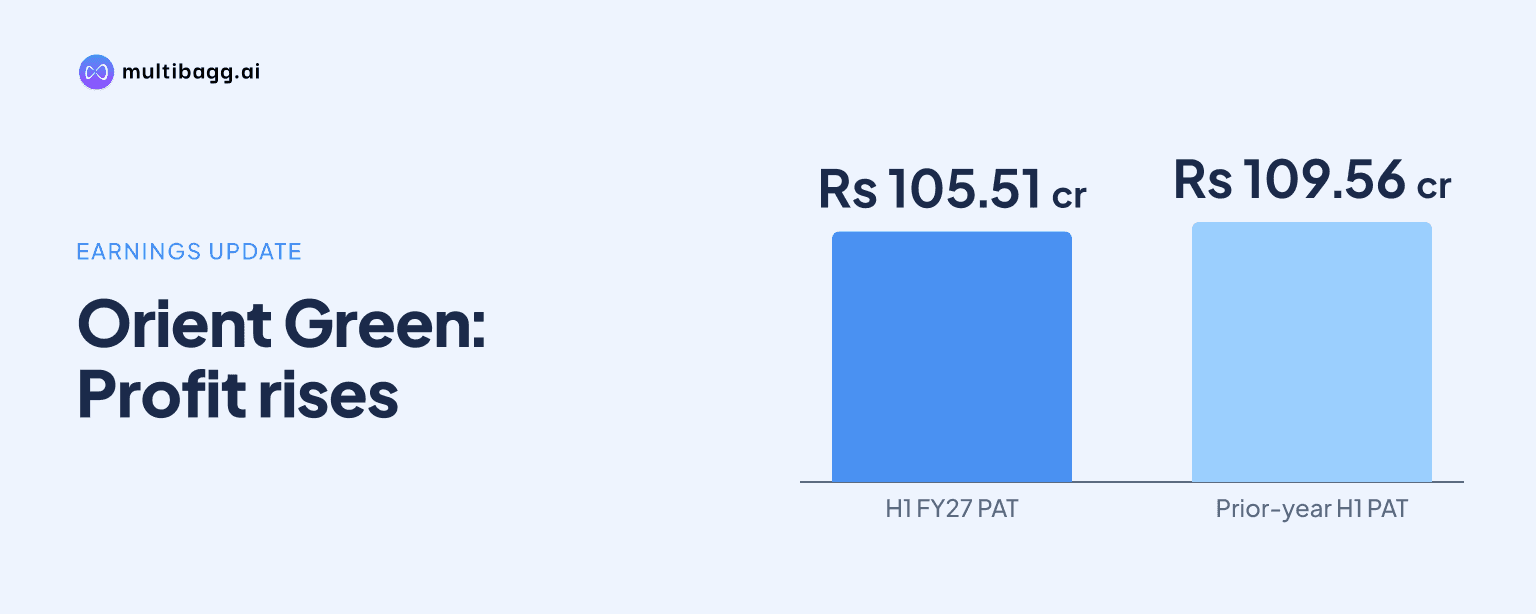
Orient Green Power Company Limited reported Rs 105.51 crore profit after tax (PAT) in H1 FY27, versus Rs 109.56 crore a year earlier, but management said the prior figure included a Rs 16 crore interest-refund gain. Excluding that item, management said H1 FY27 profit was about Rs 12 crore higher on a comparable basis.
Know Orient Green Power Company inside out
Results, valuation, peers and who's buying, in one view.
Why did OGPL's reported H1 profit fall?
OGPL's reported H1 FY27 PAT fell Rs 4.05 crore because the Rs 109.56 crore profit in the corresponding prior-year period included a Rs 16 crore exceptional gain. Management said that gain was a refund of excess interest paid in earlier years, while the Rs 105.51 crore PAT recorded in H1 FY27 contained no extraordinary income.
On management's like-for-like comparison, excluding the earlier Rs 16 crore refund leaves a lower prior-year base than the current Rs 105.51 crore PAT. Management said H1 FY27 PAT was therefore about Rs 12 crore higher on a comparable basis. Q2 FY27 PAT also rose to Rs 81.57 crore from Rs 80.94 crore in the corresponding prior-year quarter, an increase of Rs 0.63 crore.
How did OGPL's operations perform in H1 FY27?
OGPL reported higher income and earnings before interest, tax, depreciation and amortisation (EBITDA) in H1 FY27 despite lower wind availability over the six-month period. H1 total income increased 2% to Rs 232.81 crore and EBITDA rose 4% to Rs 176.56 crore, while Q2 income grew 8% to Rs 146.57 crore and Q2 EBITDA increased 12% to Rs 116.55 crore.
Management said Q2 wind conditions improved from Q1 FY27 after a substantially delayed southwest monsoon began to progress satisfactorily. Although H1 wind availability was below the previous year, OGPL said added capacity and better machine availability maintained and increased generation in both Q2 and H1. Its major subsidiary, Beta, recorded a plant load factor (PLF) of 26.82% in H1 FY27 and 33.11% in Q2 FY27.
What capacity additions will affect OGPL after H1 FY27?
OGPL expects its 17.6-megawatt solar plant, commissioned on September 26, 2026, to contribute generation from Q3 FY27. The project used proceeds from the August 2024 rights issue. Combined with a 7-megawatt solar plant commissioned in December 2025, OGPL's solar capacity reached 24.6 megawatts.
Management said the new solar plant should generate significant revenue in Q3 and Q4 FY27, without providing a revenue estimate. The 17.6-megawatt project completed the stated rights-issue objectives. Solar PLF was about 25% in the period discussed on the November 12, 2026 earnings call, compared with quarterly PLFs of 32% to 36% at smaller older wind subsidiaries that also include newer turbines.
OGPL has nearly completed repowering 7.8 megawatts of old wind turbines but is awaiting statutory approvals for commissioning. It has also signed an engineering, procurement and construction contract for 6.6 megawatts of new wind capacity, partly funded by debt already tied up. Management said wind assets may be commissioned in Q3 FY27, but their full generation contribution should come in the next financial year.
Got a follow-up? Ask IRIS
What are OGPL's debt and repowering plans?
OGPL reported approximately Rs 562.9 crore of outstanding debt and a weighted average cost of debt of about 9.09%. Project borrowing rates ranged from 8.2% to 9.25%. Management said the one-notch upgrade to BBB for Beta, and a BBB rating for its solar subsidiary, supported access to financing for expansion projects.
Management is seeking to reduce Beta's borrowing cost following the rating upgrade, although it said lender IREDA requires time to process a rate revision. Its stated objective is to maintain funding costs even if the Reserve Bank of India raises rates by 25 basis points. This was a management target, not a disclosed change in borrowing rates.
OGPL identified 30 to 40 megawatts that could benefit from repowering, including machines that management said were not performing adequately. A potential second phase covers about 10 megawatts at one subsidiary and 20 megawatts at another. Management said formal approval of Tamil Nadu's repowering policy remains pending, despite alignment with the Electricity Board on the policy.
What did OGPL say about future expansion?
OGPL said future growth is likely to be more wind-focused because management sees surplus solar generation capacity in parts of India and grid absorption constraints during afternoon hours. The company had added about 17 megawatts of new wind capacity, of which roughly 10 megawatts was operational and 6.6 megawatts was under construction.
Management said one 3.3-megawatt wind unit was ready for commissioning, while another was expected to be ready within a few weeks of the November 12, 2026 call. Subject to government approvals, it expected the work to be completed by the end of December 2026. It also said a step change towards its previously discussed 1-gigawatt ambition would require inorganic activity, while organic growth and repowering continue.
Conclusion
OGPL's reported H1 FY27 PAT of Rs 105.51 crore was lower than the Rs 109.56 crore reported a year earlier, but the comparison includes a Rs 16 crore exceptional interest refund in the prior period. Income rose 2% to Rs 232.81 crore and EBITDA rose 4% to Rs 176.56 crore despite weaker H1 wind availability, which management attributed to capacity additions and improved machine availability.
The next milestones are Q3 FY27 generation from the 17.6-megawatt solar plant, statutory approval for the 7.8-megawatt wind repowering project, and possible wind commissioning by the end of December 2026. Management also plans a potential further 30 megawatts of repowering after Tamil Nadu formalises its policy and said it expects significant action before the end of FY27.