










PI Industries Q2 profit falls 70% as margin reaches 14%
Key highlights
- PI Industries reported Q2FY27 consolidated PAT of Rs 122.2 crore, down 70.1% year on year.
- PI Industries’ Q2FY27 EBITDA margin fell to 14% from 29% in Q2FY26.
- PI Industries’ Q2FY27 export revenue declined 16.7% to Rs 1,227.7 crore, while domestic revenue rose 19.0% to Rs 474.1 crore.
- PI Industries reduced net working-capital days by 18 to 121 at September 2026, releasing Rs 298.1 crore of cash.
powered by IRIS
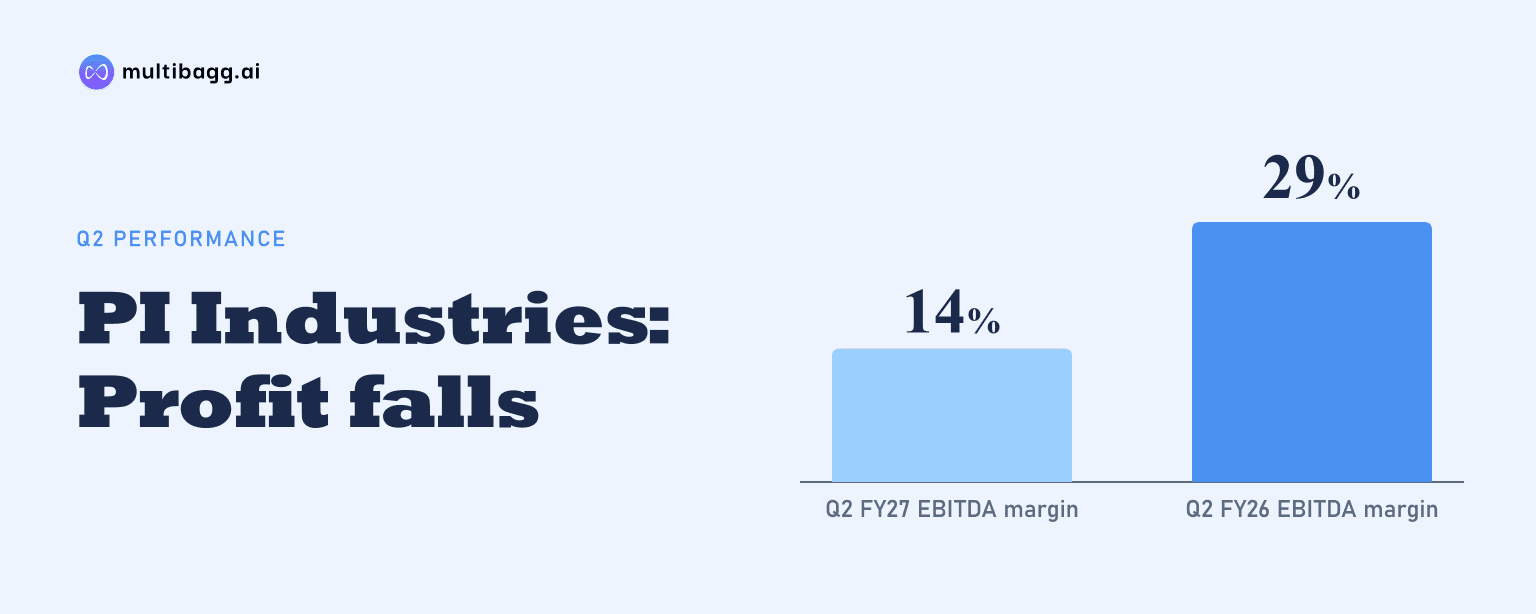
PI Industries Limited reported consolidated Q2FY27 net profit of Rs 122.2 crore, down 70.1% year on year, after EBITDA margin fell to 14% from 29% and revenue declined 9% to Rs 1,701.8 crore. PI Industries attributed the pressure to lower agrochemical export demand, genericisation-led pricing pressure, higher input costs and investment spending.
Know P I Industries inside out
Results, valuation, peers and who's buying, in one view.
What happened to PI Industries in Q2FY27?
PI Industries reported a substantially larger earnings decline than its revenue decline in Q2FY27. Consolidated revenue was Rs 1,701.8 crore, compared with Rs 1,872.3 crore in Q2FY26, while earnings before interest, tax, depreciation and amortisation, or EBITDA, fell 56.5% to Rs 236.2 crore from Rs 543.4 crore. Net profit declined to Rs 122.2 crore from Rs 409.3 crore.
The sequential comparison shows that revenue was broadly unchanged from Rs 1,702.3 crore in Q1FY27, but profitability declined further. EBITDA fell from Rs 369.3 crore in Q1FY27 and net profit fell from Rs 244.2 crore. EBITDA margin consequently narrowed from 22% in Q1FY27 to 14% in Q2FY27.
PI Industries also reported lower standalone results in Q2FY27, with revenue down 12%, EBITDA down 51% and profit after tax, or PAT, down 58%. The presentation identifies agrochemical export conditions as the principal area of pressure, while domestic operations, biologicals and health sciences recorded growth measures during the quarter.
Why did PI Industries’ EBITDA margin fall to 14%?
PI Industries’ EBITDA margin fell because gross margin contracted while overheads increased despite lower revenue. Gross margin declined by 8 percentage points to 49% in Q2FY27 from 57% in Q2FY26. PI Industries cited a 5% impact from higher input costs and pricing pressure associated with El Nino and genericisation.
PI Industries said cost escalation was not actively passed through under current market conditions, limiting price recovery in exports. Overheads increased to Rs 609.1 crore from Rs 530.6 crore a year earlier, even though revenue declined by Rs 170.5 crore. The presentation cited investment in new-business development, R&D, new-molecule launch expenses and higher energy costs.
The company identified new-business development as a 6% overhead factor, R&D as 2%, new-molecule launch expenses as 1% and higher energy costs as 3%. For H1FY27, gross margin declined to 53% from 57%, while EBITDA margin fell to 18% from 28%. That half-year comparison indicates that the Q2 margin decline followed pressure seen through the first six months.
Got a follow-up? Ask IRIS
Which PI Industries businesses grew despite export weakness?
PI Industries’ export revenue declined 16.7% to Rs 1,227.7 crore in Q2FY27 from Rs 1,473.9 crore in Q2FY26. The company linked the approximately 18% agrochemical export decline to lower demand, genericisation and pricing pressure. Management said its response after genericisation is to focus on volume growth through price optimisation.
Domestic revenue rose 19.0% to Rs 474.1 crore from Rs 398.4 crore, partly offsetting the export decline. PI Industries said domestic biologicals grew more than 45% in Q2FY27, supported by expanded crop reach and product portfolio. Global biologicals grew more than 250%, with channels and portfolios expanding in the United States, Brazil and Mexico.
Health sciences revenue grew 20% in Q2FY27, and PI Industries said it commenced commercial good manufacturing practice, or GMP, manufacturing of Galidesivir active pharmaceutical ingredient, or API. In H1FY27, however, health sciences revenue declined 4%; the company also reported three molecules commercialised and two domestic products launched during the half year.
What do PI Industries’ H1FY27 figures and cash position show?
PI Industries reported H1FY27 revenue of Rs 3,404.1 crore, down 10% from Rs 3,772.8 crore in H1FY26, while EBITDA declined 43.2% to Rs 605.5 crore and PAT fell 54.7% to Rs 366.4 crore. Export revenue decreased 15.0% to Rs 2,581.9 crore, whereas domestic revenue increased 11.6% to Rs 822.2 crore.
The H1FY27 mix shows domestic growth did not fully offset the larger export business decline. PI Industries said domestic biologicals grew more than 55% in the half year, while global biologicals grew 96%. It also reported two product launches in domestic operations and three molecules commercialised despite continuing global agrochemical pricing pressure.
PI Industries reduced net working-capital days to 121 at September 2026 from 139 days at March 2026, releasing Rs 298.1 crore of cash. Trade receivable days declined to 117 from 126, payable days increased to 62 from 53 and inventory days remained at 66. The company reported surplus cash net of debt of Rs 3,573.7 crore at September 2026.
H1FY27 capital expenditure was Rs 567.4 crore for efficiencies, capacities, new initiatives and R&D. Fixed assets including goodwill increased to Rs 6,014.5 crore at September 2026 from Rs 5,649.6 crore at March 2026, while cash, bank balances and investments were Rs 3,747.8 crore. Short-term debt stood at Rs 69.6 crore and the debt-to-equity ratio was 0.02.
Conclusion
PI Industries’ Q2FY27 results show that a 9% revenue decline produced a 70.1% fall in net profit as export pricing pressure, higher input costs and increased overheads reduced EBITDA margin to 14%. Domestic revenue growth of 19.0%, biologicals growth of more than 45% domestically and more than 250% globally, and 20% health-sciences growth did not offset the 16.7% export revenue decline.
The next markers are management’s stated price-optimisation strategy to pursue volumes after genericisation, the expansion of biological channels in the United States, Brazil and Mexico, and investment in new businesses, R&D and launches. PI Industries had also scheduled its earnings conference call for November 5, 2026, following the presentation issued on November 4, 2026.