










Popular Vehicles targets 4.2% FY27 EBITDA margin after Q2 gain
Key highlights
- Q2 FY27 EBITDA rose 57% year on year to Rs 77.7 crore, and EBITDA margin improved to 3.7% from 3.2%.
- Management targets an EBITDA margin of about 4.2% in FY27 and 4.5% to 4.6% next year.
- Q2 FY27 revenue from operations increased 36% to Rs 2,088 crore, while profit after tax was Rs 2.2 crore.
- H1 FY27 EBITDA rose 70% to Rs 149.8 crore and profit after tax improved from a Rs 8.2 crore loss to Rs 3.6 crore.
powered by IRIS
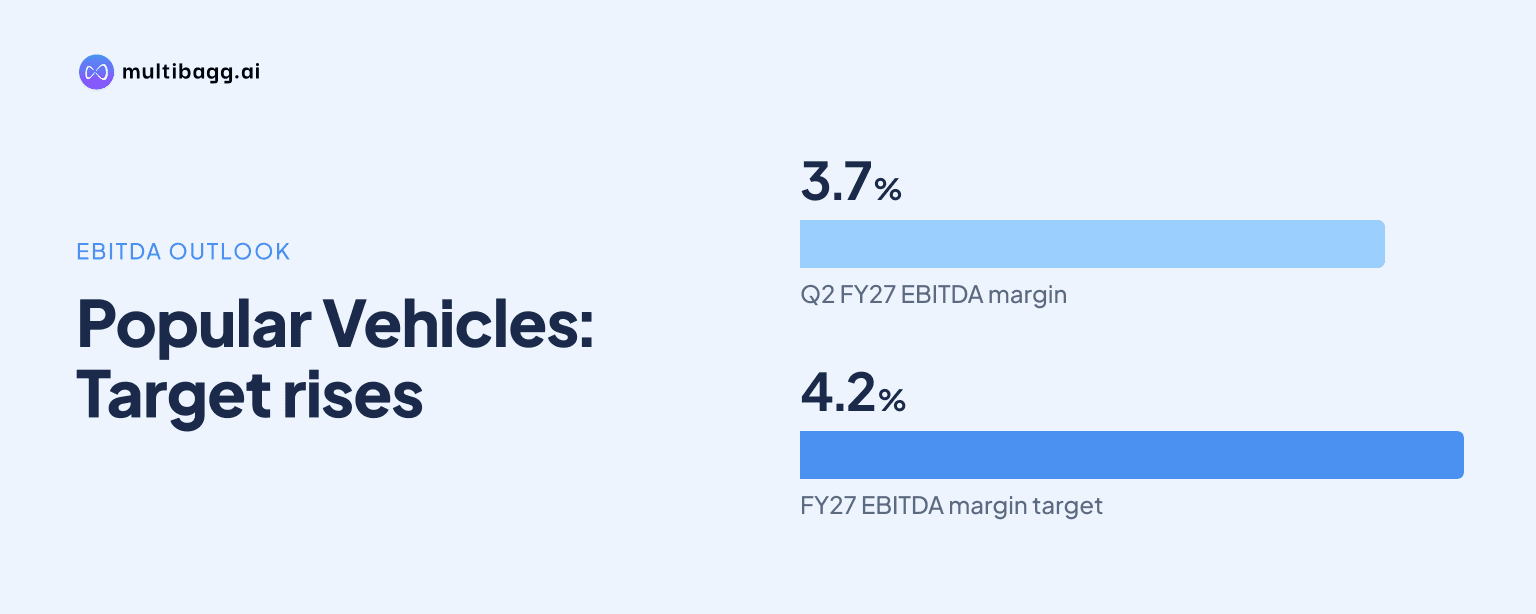
Popular Vehicles and Services Limited is targeting an EBITDA margin of about 4.2% in FY27 after Q2 FY27 EBITDA rose 57% year on year to Rs 77.7 crore and margin improved to 3.7% from 3.2%. Management is looking for a 4.5% to 4.6% margin next year through service growth, acquired-dealership utilisation and recurring aftermarket income.
Know Popular Vehicles & Services inside out
Results, valuation, peers and who's buying, in one view.
What is Popular Vehicles’ EBITDA margin target for FY27 and next year?
Popular Vehicles expects to end FY27 with an EBITDA margin of about 4.2% and is targeting 4.5% to 4.6% next year. The target follows a reported consolidated margin of 3.7% in Q2 FY27, compared with 3.2% in Q2 FY26, while EBITDA, or earnings before interest, tax, depreciation and amortisation, increased to Rs 77.7 crore from Rs 49.5 crore.
Management said EBITDA margins rose by about 1 percentage point across most segments in Q2 FY27, including commercial vehicles. Commercial vehicles have an increasing contribution to the business and influence the consolidated margin profile, but management said it is pursuing higher absolute earnings and profitability across all segments rather than relying on a single business line.
The reported Q2 EBITDA was also 8% above Rs 72.1 crore in Q1 FY27. However, Q1 included a one-off Rs 5.4 crore benefit from a lease modification related to Telangana operations; excluding it, management calculated Q1 EBITDA at Rs 66.7 crore, implying underlying sequential EBITDA growth of about 16% in Q2.
How did Popular Vehicles’ profitability change in Q2 and H1 FY27?
Popular Vehicles reported profit after tax of Rs 2.2 crore in Q2 FY27, compared with Rs 0.6 crore in Q2 FY26. Profit before tax and exceptional items moved to Rs 4.3 crore from a Rs 3.6 crore loss, although management said depreciation and finance costs associated with acquired operations continued to affect earnings below EBITDA.
For H1 FY27, Popular Vehicles’ revenue from operations increased 40% to Rs 3,983.9 crore from Rs 2,851.2 crore in H1 FY26. EBITDA rose 70% to Rs 149.8 crore from Rs 87.9 crore, and EBITDA margin increased to 3.7% from 3.1%; excluding the Q1 lease-modification benefit, H1 EBITDA was Rs 144.4 crore, or about 64% higher year on year.
H1 FY27 profit after tax was Rs 3.6 crore, compared with a Rs 8.2 crore loss in the prior-year period, while cash profit after tax increased 84% to Rs 84.5 crore from Rs 46 crore. Management also presented adjusted H1 profit before tax before exceptional items of Rs 29.8 crore, compared with reported profit before tax of Rs 6.1 crore, to reflect acquisition and divestment effects.
The prior-year comparison includes a separate exceptional item: Q2 FY26 included an approximately Rs 15.3 crore gain from the divestment of two subsidiaries. That gain affected reported profit-before-tax comparisons, while the Q2 FY27 improvement to Rs 4.3 crore before exceptional items reflects the operating result without such a disclosed prior-year divestment gain.
Got a follow-up? Ask IRIS
Which businesses are expected to lift Popular Vehicles’ margin?
Popular Vehicles expects after-sales revenue and greater workshop utilisation to help lift margin from 3.7% in Q2 FY27 toward the 4.2% FY27 target. Passenger-vehicle service income grew 22% to Rs 181 crore in Q2 while service volume increased 5% to 196,652 units, meaning service income grew faster than workshop visits during the quarter.
Commercial-vehicle service income increased 15% to Rs 100 crore in Q2 FY27 as service volume rose 9% to 54,906 units. In H1 FY27, commercial-vehicle service income grew 29% to Rs 207 crore, ahead of 12% volume growth to 107,553 units; management cited increasing vehicle complexity and sophistication as drivers of service intensity and workshop revenue.
Electric-vehicle service volume rose 59% to 15,792 units in Q2 FY27 and service income increased 64% to about Rs 4 crore. Management linked the increase to the expanding Ather vehicle base, while new electric-vehicle sales rose 115% to 3,685 units and income grew 124% to Rs 63 crore, creating a larger potential service base over time.
Management also plans to raise productivity at the BharatBenz dealership operations in Punjab and Maruti Suzuki dealership operations in Telangana, acquired about a year before the call. New-vehicle sales have scaled faster than service in these businesses, and management identified higher service throughput and workshop utilisation as the next steps in translating the expanded network into profitability.
What could affect Popular Vehicles’ FY27 margin delivery?
Popular Vehicles’ margin plan depends partly on acquired operations reaching optimal scale and festive-season inventory normalising over the coming months. The company built inventory to meet expected demand and offset vehicle-price increases, which raised borrowing sequentially, but new-vehicle inventory days were about 41 days in Q2 FY27, lower than 44 days in the corresponding prior-year period.
An unresolved insurance-commission regulatory matter could also affect the earnings mix. An analyst said Popular Vehicles earned around Rs 80 crore from insurance commission in FY26; management said original equipment manufacturers, the Federation of Automobile Dealers Associations and the Insurance Regulatory and Development Authority of India were discussing the draft rules, but it was too early to assess the final impact or compensation mechanism.
Management told the analyst that it did not expect the issue to threaten the 4.5% to 4.6% margin outlook for next year, citing its expectation that dealers could be compensated through vehicle margins or other revenue streams. This is management’s assessment, not a disclosed regulatory decision, and the outcome of the rules remains unresolved.
Yanik and BKT tyre distribution are not expected to contribute profit in FY27 because both initiatives have only recently started. Yanik, Popular Vehicles’ business-to-business spare-parts marketplace operated through Zparex Digisolutions Private Limited, had onboarded about three to four sellers and around 600 workshops and mechanics, with onboarding planned through Q3 and Q4 FY27; its platform offers more than 13,000 verified spare parts.
Conclusion
Popular Vehicles has paired 36% Q2 FY27 revenue growth to Rs 2,088 crore with a 57% increase in EBITDA to Rs 77.7 crore, setting out a path from the reported 3.7% margin to about 4.2% for FY27. The plan relies on service income, better workshop utilisation, integration of Punjab and Telangana acquisitions, and a higher share of recurring after-sales activity.
The next measures to watch are management’s FY27 revenue-growth guidance of 20% to 25%, service throughput at acquired dealerships and inventory normalisation after the festive period. Investors will also await the final insurance-commission rules, while management expects Yanik and BKT tyre distribution to have no FY27 profit contribution and sees scope for BKT to contribute more next year as production scales.