










Power Mech Q2 revenue rose 30% as EBITDA margin declined
Key highlights
- Power Mech reported Q2 FY27 revenue of Rs 1,609 crore, up 30% from Rs 1,238 crore.
- Power Mech’s Q2 FY27 EBITDA margin was 11.55%, versus 12.65% in Q2 FY26 and 10.78% in Q1 FY27.
- Infrastructure construction revenue rose 75% year on year to Rs 582 crore in Q2 FY27.
- Power Mech had secured Rs 4,801 crore of FY27 order inflow against management’s Rs 12,000 crore target.
powered by IRIS
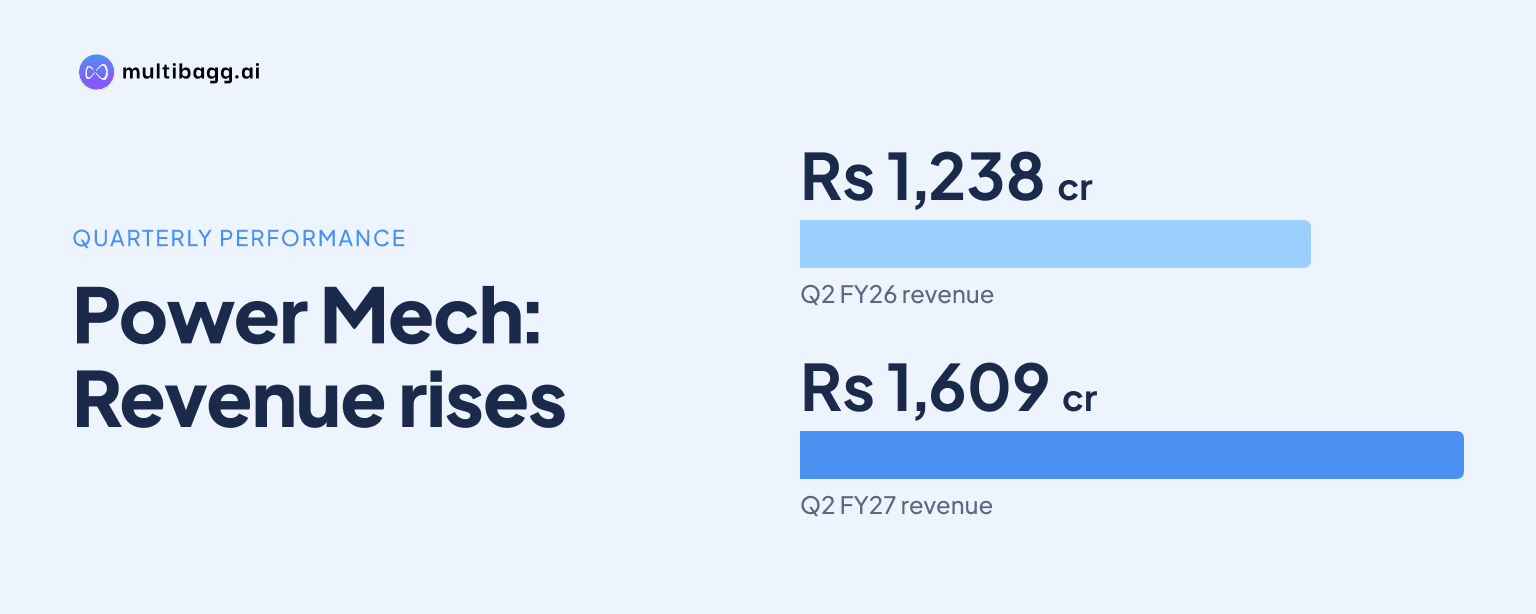
Power Mech Projects Limited reported Q2 FY27 revenue from operations of Rs 1,609 crore, up 30% year on year, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin fell to 11.55% from 12.65% because Q2 FY26 included exceptional additional revenue from Uttarakhand riverbed minerals, management said on November 13, 2026.
Know Power Mech Projects inside out
Results, valuation, peers and who's buying, in one view.
How did Power Mech perform in Q2 FY27?
Power Mech increased Q2 FY27 revenue by Rs 371 crore to Rs 1,609 crore from Rs 1,238 crore in Q2 FY26. EBITDA rose Rs 29 crore to Rs 187 crore from Rs 158 crore, while profit after tax (PAT) increased Rs 10 crore to Rs 88 crore from Rs 78 crore. Management attributed the revenue gain to higher execution in industrial services, infrastructure construction and mine developer and operator (MDO) projects.
The first half showed revenue growing faster than EBITDA. H1 FY27 revenue reached Rs 3,233 crore, up 28% from Rs 2,531 crore in H1 FY26, whereas EBITDA rose 7% to Rs 363 crore from Rs 340 crore. PAT increased 12% to Rs 177 crore from Rs 159 crore over the same six-month comparison.
Industrial construction restrained part of the quarter’s growth. Revenue in that segment declined about 14% to Rs 372 crore from Rs 435 crore, following completion of certain earlier projects and slower progress in flue-gas desulphurisation (FGD) work. Management said gains in the other operating segments more than offset that decline.
Why did Power Mech’s EBITDA margin fall year on year?
Power Mech’s Q2 FY27 EBITDA margin fell 110 basis points year on year to 11.55% because the Q2 FY26 comparison included exceptional additional revenue from Uttarakhand riverbed minerals, management said. The H1 FY27 margin was 11.17%, compared with 13.33% in H1 FY26, a 216-basis-point difference.
The quarterly trend was different from the year-on-year comparison. EBITDA increased by about Rs 11 crore from Rs 176 crore in Q1 FY27 to Rs 187 crore in Q2 FY27, and the margin rose from 10.78% to 11.55%. Management attributed the sequential improvement to better operating-cost management and improved execution.
PAT moved lower sequentially despite the EBITDA increase. Management said Q2 FY27 PAT was about Rs 2 crore below Q1 FY27 because finance cost and depreciation were higher, while Q2 PAT margin was 5.45% versus 6.31% a year earlier. Management expects a larger contribution from MDO work, execution efficiencies and cost optimisation to improve the margin trajectory in coming quarters.
Which Power Mech segments drove Q2 FY27 growth?
Power Mech’s infrastructure construction and MDO operations recorded the largest percentage gains in Q2 FY27. Infrastructure construction revenue rose 75% to Rs 582 crore from Rs 322 crore, supported by civil-infrastructure execution and new ongoing projects. MDO revenue increased to Rs 85 crore from Rs 31 crore as production ramped up at the KBP mine.
Industrial services added Rs 130 crore of revenue year on year, reaching Rs 570 crore from Rs 440 crore. Management linked the increase to improved execution and the ramp-up of projects secured through new orders. Together, infrastructure construction and industrial services generated Rs 1,152 crore in Q2 FY27, compared with Rs 762 crore a year earlier.
MDO remained smaller than infrastructure construction in current-quarter revenue, at Rs 85 crore versus Rs 582 crore, but management identified it as a future profitability contributor as its operations scale. That makes the current mix important: industrial services and infrastructure drove the immediate revenue increase, while MDO is part of management’s stated margin-improvement plan.
Got a follow-up? Ask IRIS
Can Power Mech meet its FY27 order-inflow target and convert its backlog?
Power Mech had secured Rs 4,801 crore of FY27 order inflow by the reporting period, equal to about 40% of management’s Rs 12,000 crore annual target. Fresh Q2 FY27 orders were about Rs 1,890 crore. Management said the target is being pursued through selective opportunities in thermal power, industrial services, civil infrastructure, operation and maintenance (O&M), and mining.
Management identified Rs 3,650 crore of installation opportunities with Adani and JSW, and about Rs 1,850 crore of O&M opportunities it expected to pursue over the following four months. These were prospective opportunities, rather than secured orders. Management also cited projects under pursuit at Durgapur of around Rs 2,500 crore, JSW coal handling of about Rs 1,000 crore, and BHEL Amarkantak of about Rs 2,000 crore.
The O&M business provides part of the order base. Power Mech said it was working across about 38,500 megawatts at 32 plants, including 9,000 megawatts of comprehensive O&M and 15,400 megawatts of semi-comprehensive work. O&M backlog increased 56% to about Rs 4,642 crore from Rs 2,972 crore last year, according to management.
Power Mech reported consolidated order backlog of Rs 56,729 crore as of the November 13 call date, up about 3% year on year. MDO projects represented Rs 39,243 crore, while the executable order book excluding MDO was about Rs 17,486 crore, which management said provided more than two years of revenue visibility across the core business. Q2 additions included five-year O&M contracts for Vedanta’s Athena Power Plant and Adani Tuticorin’s Moxie Power Thermal Plant, each with 2 x 600 megawatts of capacity.
Conclusion
Power Mech combined 30% Q2 FY27 revenue growth with an EBITDA-margin decline caused, according to management, by the exceptional Uttarakhand riverbed-mineral revenue in the prior-year comparison. Infrastructure construction rose 75% to Rs 582 crore, industrial services reached Rs 570 crore, and MDO revenue climbed to Rs 85 crore as KBP mine production ramped up.
The next items to watch are execution against the Rs 12,000 crore FY27 order-inflow target, after Rs 4,801 crore had been secured by the reporting date, and management’s planned increase in O&M and MDO contribution. Management also cited timely project certification, collections and working-capital management as priorities for the coming quarter, alongside the expected pursuit of about Rs 1,850 crore in O&M opportunities.