










Pritika Auto Industries H1 Revenue Rises 28.9% to ₹299.37 Crore
Key highlights
- Pritika Auto Industries reported H1 FY27 consolidated revenue of ₹299.37 crore, up 28.9% year on year.
- H1 FY27 consolidated PAT rose 11.8% to ₹12.80 crore from ₹11.45 crore.
- Q2 FY27 consolidated revenue grew 31.6% year on year to ₹153.19 crore.
- Q2 FY27 standalone material consumption increased 37.8% year on year, above revenue growth of 29.7%.
powered by IRIS
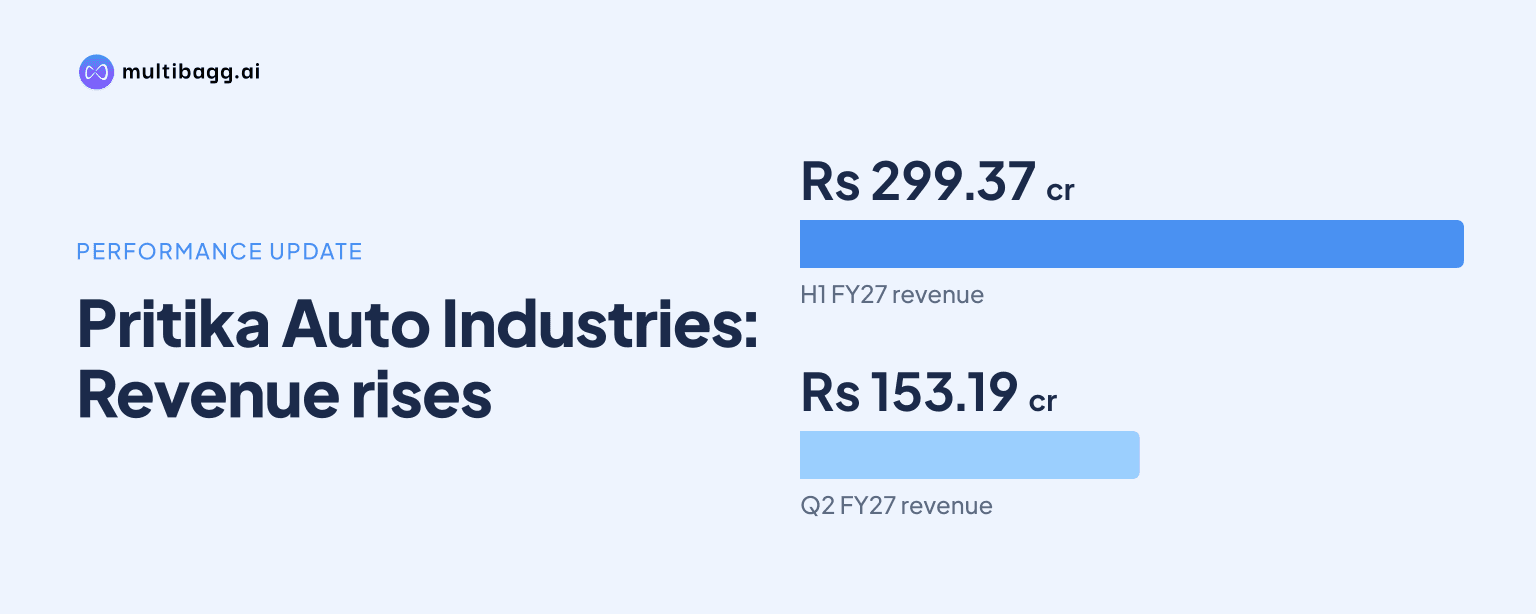
Pritika Auto Industries Ltd reported consolidated revenue of ₹299.37 crore for the half year ended September 30, 2026, a 28.9% increase from ₹232.10 crore a year earlier, while profit after tax rose 11.8% to ₹12.80 crore. The result shows continued sales growth, although quarterly profitability expanded more slowly than revenue.
Know Pritika Auto Industries inside out
Results, valuation, peers and who's buying, in one view.
What were Pritika Auto's H1 FY27 financial results?
Pritika Auto reported consolidated revenue from operations of ₹299.37 crore in H1 FY27, compared with ₹232.10 crore in H1 FY26. The ₹67.28 crore increase reflected year-on-year growth of 28.9%. Consolidated profit after tax rose to ₹12.80 crore from ₹11.45 crore, an increase of 11.8%.
For the September quarter, consolidated revenue from operations was ₹153.19 crore, up 31.6% from ₹116.45 crore in Q2 FY26. Quarterly consolidated PAT increased 12.5% year on year to ₹7.43 crore. The difference between sales and profit growth indicates that costs absorbed part of the operating benefit from higher revenue.
The Board of Directors approved the consolidated financial results for the quarter and half year ended September 30, 2026 on November 5, 2026. The company said the standalone and consolidated statements were accompanied by limited review reports from its statutory auditors, with no material misstatement reported in the financial disclosures.
How did the September quarter contribute to the half-year growth?
Pritika Auto's Q2 sales growth built on the momentum visible in the June quarter. Consolidated net sales for the June 2026 quarter were reported at ₹144.97 crore, up 26.49% year on year. The September-quarter consolidated revenue of ₹153.19 crore was also higher than the June-quarter level.
On a standalone basis, revenue rose to ₹149.81 crore in Q2 FY27 from ₹115.63 crore in the corresponding quarter of FY26. Standalone PAT was ₹4.43 crore, only modestly above ₹4.36 crore a year earlier. This limited 1.7% rise in standalone profit, despite a 29.7% rise in revenue, was the key feature of the quarterly performance.
The consolidated result includes operating contributions from subsidiaries Pritika Engineering Components Limited and Meeta Castings Limited. The company attributed consolidated PAT growth in the quarter to improved operational efficiency across its subsidiaries. No quarterly earnings-call transcript had been published at the time of the reported results, so the stated figures represent the financial disclosures and investor presentation rather than additional management guidance.
Got a follow-up? Ask IRIS
Why did profit grow slower than revenue in Q2 FY27?
Pritika Auto's reported cost trends point to pressure on margins during the September quarter. Standalone material consumption increased 37.8% year on year, exceeding the 29.7% increase in standalone revenue. As a result, profit before tax was described as virtually flat, rising 0.5% despite the stronger sales base.
Finance costs also increased to ₹0.47 crore in Q2 FY27 from ₹0.43 crore in Q2 FY26. Higher material costs and finance costs limited the conversion of revenue growth into profit. The available disclosures do not specify a revised margin target or a quantified recovery plan for these costs.
The cost issue follows conditions cited after FY26, when Pritika Auto said Q4 margins had faced pressure from higher raw-material and energy costs. At that time, management expected cost recovery through pass-through mechanisms and improved capacity utilisation in subsequent periods. The Q2 FY27 financial figures show that revenue continued to rise, while margin pressure remained relevant to the profit trend.
What does the result mean for investors and industry operations?
The half-year result confirms that Pritika Auto is growing faster than its FY26 revenue target range of 15% to 20%, at least on the reported H1 FY27 comparison. The company's FY26 strategy included demand from existing clients, entry into railway and defence sectors, and a move toward higher-value products. The H1 release, however, does not provide a revenue split by customer, sector or product category.
For investors, the central data point is the gap between consolidated revenue growth of 28.9% in H1 FY27 and PAT growth of 11.8%. The September-quarter standalone figures show a similar pattern more sharply, with revenue up 29.7% and PAT up 1.7%. Material-cost movement, finance costs and any improvement in operating efficiency are therefore relevant measures in assessing subsequent results.
Pritika Auto has scheduled an earnings conference call for November 11, 2026, at 11:30 AM IST to discuss its Q2 and H1 FY27 performance and outlook. The company is listed on the National Stock Exchange of India and is subject to SEBI's periodic disclosure requirements. The call gives shareholders and analysts a scheduled forum to seek details on volumes, costs, capacity utilisation and the progress of its growth plans.
Conclusion
Pritika Auto delivered a strong increase in consolidated revenue in H1 FY27, reaching ₹299.37 crore and exceeding the prior-year period by 28.9%. Profit growth was positive but slower at 11.8%, while the quarterly standalone numbers showed that material and finance costs constrained earnings conversion.
The next disclosed event is the November 11, 2026 earnings call. Investors will watch for management's comments on raw-material costs, borrowing costs, subsidiary operations and the company's stated medium-term objective of reaching ₹600 crore in revenue by FY28.