










Pritika Auto Q2 revenue rose 31.55% as EBITDA margin fell
Key highlights
- Pritika Auto’s Q2 FY27 consolidated revenue rose 31.55% to Rs 153.19 crore.
- Pritika Auto’s Q2 FY27 EBITDA margin fell 214 bps year on year to 13.85%.
- Pritika Auto’s Q2 FY27 total expenditure increased 34.90% to Rs 131.98 crore.
- Pritika Auto’s H1 FY27 net revenue rose 29.04% to Rs 298.16 crore.
powered by IRIS
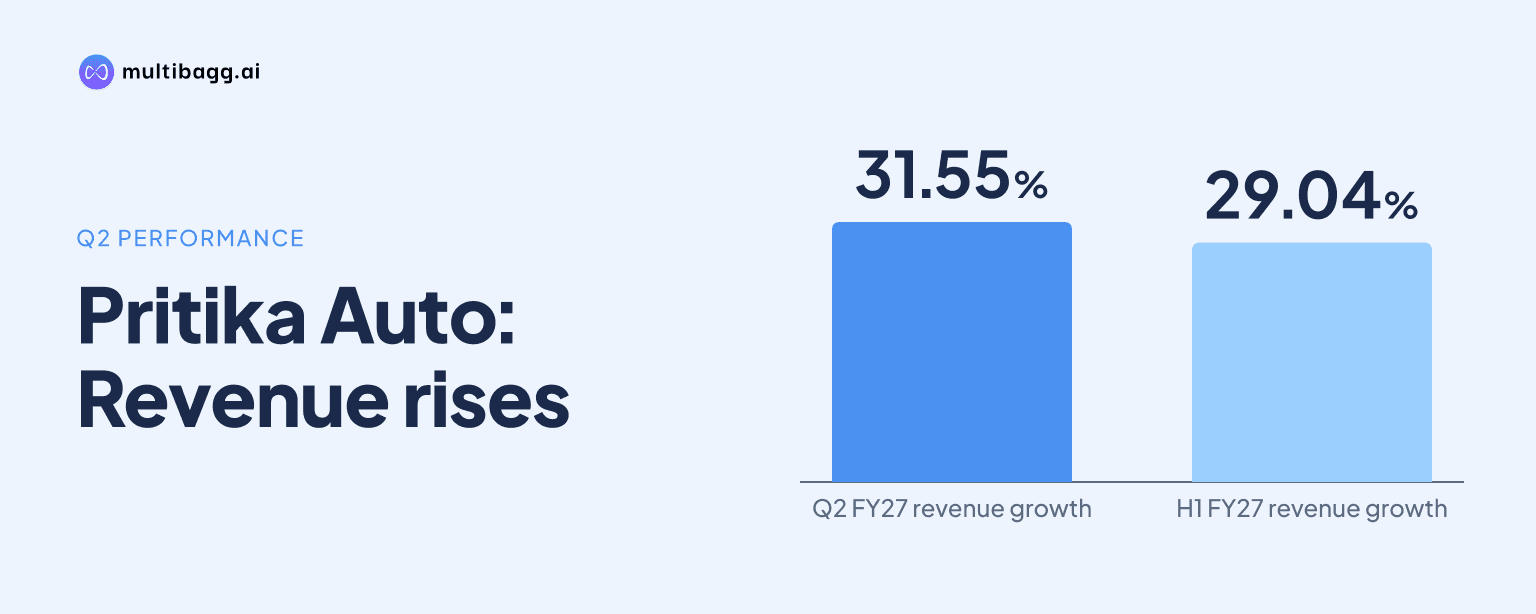
Pritika Auto Industries Limited reported Q2 FY27 consolidated revenue of Rs 153.19 crore, up 31.55% year on year, while EBITDA margin fell 214 basis points to 13.85% as total expenditure rose 34.90%, faster than sales. EBITDA increased 13.97% to Rs 21.21 crore despite the higher cost growth.
Know Pritika Auto Industries inside out
Results, valuation, peers and who's buying, in one view.
How did Pritika Auto perform in Q2 FY27?
Pritika Auto delivered higher sales and profit in Q2 FY27, although operating profit grew more slowly than revenue. Consolidated net revenue increased from Rs 116.45 crore in Q2 FY26 to Rs 153.19 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA) rose from Rs 18.61 crore to Rs 21.21 crore. Revenue growth was 31.55%, compared with EBITDA growth of 13.97%.
Profit after tax (PAT) increased 12.41% to Rs 7.43 crore from Rs 6.61 crore a year earlier. However, PAT margin declined to 4.85% from 5.67%, a reduction of 82 basis points, or bps. Basic earnings per share (EPS) rose to Rs 0.39 from Rs 0.36, a year-on-year increase of 8.33%.
Pritika Auto’s Q2 revenue was also higher sequentially, rising from Rs 144.97 crore in Q1 FY27 to Rs 153.19 crore in Q2 FY27. EBITDA increased from Rs 19.50 crore to Rs 21.21 crore over the same period, and the EBITDA margin improved from 13.45% to 13.85%, although it remained below the 15.99% reported in Q2 FY26.
Pritika Auto’s standalone Q2 FY27 revenue from operations was Rs 149.81 crore, compared with consolidated revenue of Rs 153.19 crore. Standalone EBITDA was Rs 13.36 crore with an 8.92% margin, while standalone PAT was Rs 4.43 crore with a 2.96% margin.
Why did Pritika Auto’s EBITDA margin decline?
Pritika Auto’s EBITDA margin declined because total expenditure increased faster than revenue on a year-on-year basis. Total expenditure rose 34.90% to Rs 131.98 crore in Q2 FY27, exceeding the 31.55% increase in net revenue to Rs 153.19 crore. EBITDA was Rs 21.21 crore, compared with Rs 18.61 crore in Q2 FY26.
Raw-material cost was the biggest expense category and increased to Rs 84.93 crore from Rs 58.80 crore. Employee cost rose to Rs 12.92 crore from Rs 10.45 crore, while other costs increased to Rs 34.12 crore from Rs 28.58 crore. These three cost lines together rose by Rs 34.14 crore, against a Rs 36.74 crore increase in revenue.
Management attributed the margin movement to elevated input costs and an evolving product mix. It said Pritika Auto was pursuing cost optimisation, operational efficiencies and improved realisations to support a gradual improvement in profitability, while reporting a sequential EBITDA-margin improvement of 40 bps from Q1 FY27’s 13.45% to Q2 FY27’s 13.85%.
Got a follow-up? Ask IRIS
What does Pritika Auto’s first-half result show?
Pritika Auto’s H1 FY27 figures show the same gap between revenue growth and operating-profit growth seen in the second quarter. Net revenue increased 29.04% to Rs 298.16 crore from Rs 231.06 crore in H1 FY26, whereas EBITDA increased 12.93% to Rs 40.72 crore from Rs 36.05 crore. EBITDA margin therefore declined 194 bps to 13.66% from 15.60%.
Total expenditure for H1 FY27 rose to Rs 257.44 crore from Rs 195 crore in H1 FY26. Raw-material cost increased to Rs 165.33 crore from Rs 118.70 crore, employee cost reached Rs 25.05 crore from Rs 20 crore, and other cost was Rs 67.07 crore against Rs 56.30 crore. These reported cost lines accompanied expenditure growth that exceeded the 29.04% revenue increase.
PAT nevertheless increased 14.52% to Rs 14.55 crore in H1 FY27 from Rs 12.70 crore a year earlier. The H1 PAT margin fell 62 bps to 4.88% from 5.50%, while basic EPS increased 11.59% to Rs 0.77 from Rs 0.69. Both operating and net margins were lower year on year despite higher absolute EBITDA and PAT.
What changed sequentially and what is Pritika Auto planning?
Pritika Auto recorded a sequential recovery in operating margin during Q2 FY27. Revenue rose by Rs 8.22 crore from Q1 FY27’s Rs 144.97 crore, while total expenditure rose by Rs 6.51 crore from Rs 125.47 crore. This left EBITDA Rs 1.71 crore higher at Rs 21.21 crore and lifted the margin to 13.85% from 13.45%.
Pritika Auto reported Q2 FY27 production volume of 15,665 tonnes, up 21.61% year on year, and H1 FY27 volume of 30,033 tonnes, up 18.86%. Management said second-half priorities include sustaining volume growth, improving capacity utilisation, enhancing operating efficiencies, and maintaining discipline over costs and working capital.
Pritika Auto also disclosed that subsidiary Pritika Engineering Components Limited secured an export order from an Italian precision-engineering manufacturer for specialised engineering components. Separately, management said product supplied under the earlier KION USA order had received customer approval and regular production is expected in 2027-28. The presentation did not disclose an order value for either international development.
Conclusion
Pritika Auto’s Q2 FY27 result combined revenue growth of 31.55% and EBITDA growth of 13.97%, but the difference between those rates reduced EBITDA margin by 214 bps to 13.85%. The H1 FY27 pattern was similar: revenue rose 29.04% to Rs 298.16 crore, while EBITDA margin fell 194 bps to 13.66%, with raw-material costs increasing from Rs 118.70 crore to Rs 165.33 crore.
The next reported periods will show whether management’s stated actions on cost optimisation, operational efficiency, capacity utilisation and realisations can extend the Q2 sequential margin improvement from 13.45% to 13.85%. Progress on the Italian export order and the KION USA programme, for which management expects regular production in 2027-28, will also be relevant, while order values remain undisclosed.