










Prospect H1 FY27 profit fell 30% as revenue rose 5% year on year
Key highlights
- Prospect reported H1 FY27 PAT of Rs 1.45 crore, down 29.83% year on year.
- Prospect reported H1 FY27 total income of Rs 31.10 crore, up 4.75% year on year.
- Prospect’s reported H1 FY27 EBITDA margin was 10.93%, down 262 basis points from H1 FY26.
- Prospect’s inventory was Rs 20.73 crore in H1 FY27, versus Rs 18.30 crore at FY26-end.
powered by IRIS
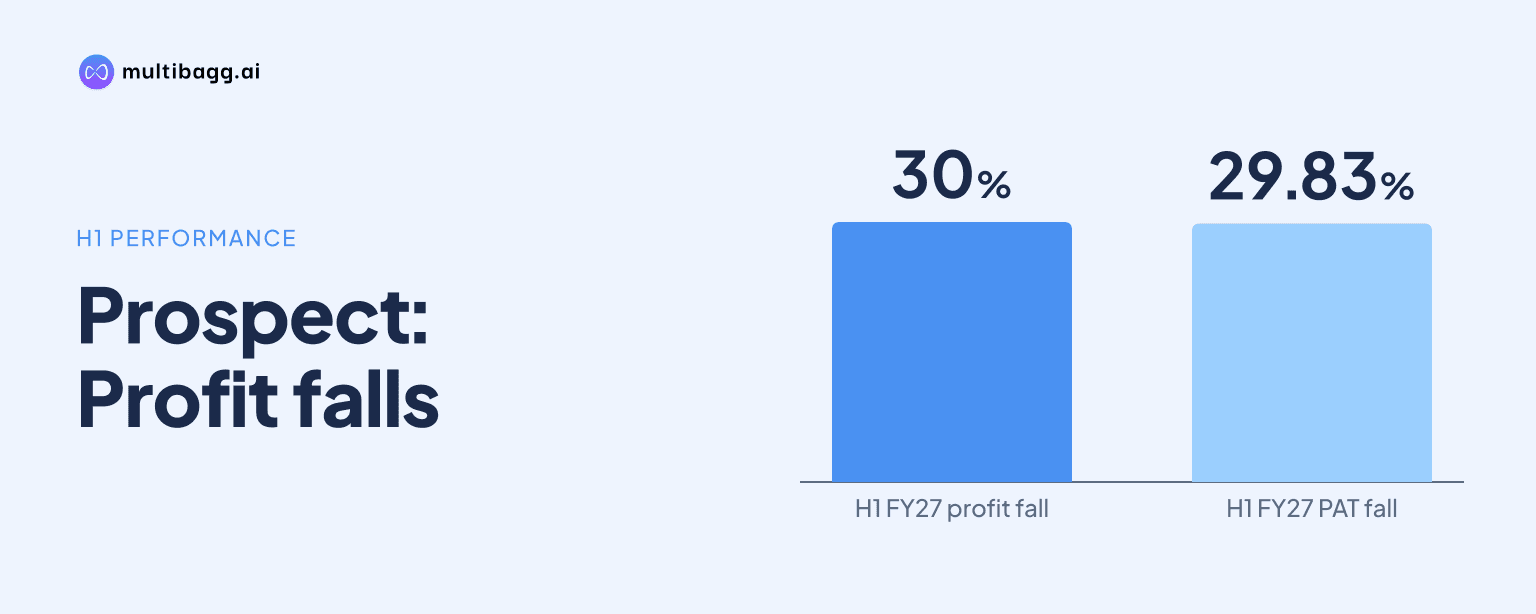
Prospect Consumer Products Limited reported profit after tax of Rs 1.45 crore in H1 FY27, down 29.83% year on year, while total income rose 4.75% to Rs 31.10 crore. Prospect’s financial-highlights table reported EBITDA of Rs 3.40 crore, a 15.53% decline, and an EBITDA margin of 10.93%, versus 13.42% in H1 FY26.
Know Prospect Consumer Products inside out
Results, valuation, peers and who's buying, in one view.
Why did Prospect’s H1 FY27 profit fall despite higher revenue?
Prospect’s reported profit fell because its financial-highlights table showed total expenses rising 8.16%, faster than the 4.75% increase in total income. Net sales rose 4.86% to Rs 31.07 crore from Rs 29.63 crore in H1 FY26, but profit before tax fell 28.51% to Rs 1.98 crore from Rs 2.77 crore.
Prospect reported tax expense, including deferred tax, of Rs 0.53 crore in H1 FY27, compared with Rs 0.70 crore a year earlier. Earnings per share were Rs 2.36, down 31.20% from Rs 3.43 in H1 FY26. The presentation does not provide management commentary assigning a specific cause to the reported increase in expenses.
The financial-highlights table contains figures that do not fully reconcile with the profit-and-loss statement. The highlights table reports total expenses of Rs 29.12 crore and other income of Rs 2.40 crore, while the profit-and-loss statement lists total expenditure of Rs 26.76 crore for H1 FY27. Prospect provides no reconciliation between those two expense figures.
How much did Prospect’s margins contract in H1 FY27?
Prospect’s reported EBITDA margin contracted by 262 basis points to 10.93% in H1 FY27 from 13.42% in H1 FY26. EBITDA, meaning earnings before interest, tax, depreciation and amortisation, was reported at Rs 3.40 crore, compared with Rs 3.97 crore in the prior-year half.
Prospect’s PAT margin was 4.65% in the H1 FY27 financial-highlights table, down from 6.95% in H1 FY26. The profit-and-loss statement shows the H1 FY27 margin at 4.66%, a rounding difference, and the full-year FY26 margin at 4.27%.
The profit-and-loss statement lists raw-material expenses of Rs 25.32 crore in H1 FY27, employee costs of Rs 0.47 crore and other expenses of Rs 0.97 crore. These three items total Rs 26.76 crore, the expenditure figure in that statement, while the separate highlights table states total expenses of Rs 29.12 crore.
Over longer periods, Prospect’s EBITDA margin was 13.33% in FY25, 10.95% in FY26 and 10.71% in FY24. Its PAT margin was 6.88% in FY25 and 7.01% in FY24, compared with 4.66% in H1 FY27, based on the profit-and-loss statement.
Got a follow-up? Ask IRIS
What changed in Prospect’s borrowings and working capital?
Prospect’s total liabilities increased to Rs 55.30 crore in H1 FY27 from Rs 48.22 crore in FY26. Current liabilities rose to Rs 18.05 crore from Rs 14.32 crore, led by current borrowings of Rs 11.85 crore, compared with Rs 10.33 crore at the FY26 year-end.
Non-current borrowings rose to Rs 3.75 crore in H1 FY27 from Rs 1.85 crore in FY26. The debt-to-equity ratio increased to 0.47 times from 0.38 times in FY26 and 0.22 times in both FY25 and FY24. Finance costs were Rs 0.84 crore in H1 FY27, 60.36% above Rs 0.53 crore in H1 FY26.
Inventory rose by Rs 2.43 crore to Rs 20.73 crore from Rs 18.30 crore at FY26-end. Trade receivables increased to Rs 15.91 crore from Rs 15.16 crore, while other current assets rose to Rs 12.12 crore from Rs 8.58 crore.
Cash and bank balances increased to Rs 2.49 crore from Rs 0.08 crore, but total current assets also increased to Rs 51.33 crore from Rs 44.16 crore. Prospect reported interest coverage of 3.67 times for FY26 and 3.36 times for H1 FY26, but the presentation does not provide an H1 FY27 interest-coverage figure.
What does Prospect plan to do after H1 FY27?
Prospect’s management has projected a 45% to 50% compound annual growth rate for the next three years and an EBITDA margin between 11% and 14%. Management also targets an additional 10% contribution from the business-to-consumer segment over the next two years; these are targets rather than reported H1 FY27 results.
Prospect says it has partnered with Amazon, Jio-Mart and the Open Network for Digital Commerce, or ONDC, and plans to expand to Flipkart, Big Basket, Blinkit and quick-commerce applications. The company is targeting the Rs 20,000 crore-plus health-snack market and has launched six premium flavours under its DriFrutz brand.
Prospect plans to increase production capacity from more than 2,500 metric tonnes per annum, or MTPA, to more than 4,800 MTPA within 12 to 18 months. Management expects full automation to reduce labour costs, although the presentation does not quantify the expected reduction.
Management says weekly shipments from Africa are intended to improve working-capital cycles and that direct procurement could reduce costs by 20%. The presentation does not disclose a cost base, implementation date or progress measure for the stated procurement-cost reduction.
Conclusion
Prospect’s H1 FY27 presentation shows sales growth did not translate into higher reported earnings: total income increased 4.75% to Rs 31.10 crore, while PAT declined 29.83% to Rs 1.45 crore. Reported EBITDA margin fell to 10.93%, finance costs increased to Rs 0.84 crore, and inventory, receivables and borrowings were higher than at FY26-end.
The next disclosures will indicate whether Prospect progresses toward management’s 11% to 14% EBITDA-margin target and capacity of more than 4,800 MTPA within 12 to 18 months. Investors can also watch changes in inventory, trade receivables and current borrowings, as well as any reconciliation of the differing H1 FY27 expense figures in the presentation.