










Rajshree Polypack profit rises 41% in H1 to Rs 12.27 crore
Key highlights
- Rajshree Polypack’s H1 FY27 revenue rose 21.82% year on year to Rs 205.81 crore.
- H1 FY27 PAT increased 40.87% to Rs 12.27 crore from Rs 8.71 crore.
- Operating EBITDA margin increased 89 basis points to 13.35% in H1 FY27.
- Net debt was Rs 101.27 crore in H1 FY27, down from Rs 101.44 crore at FY26.
powered by IRIS
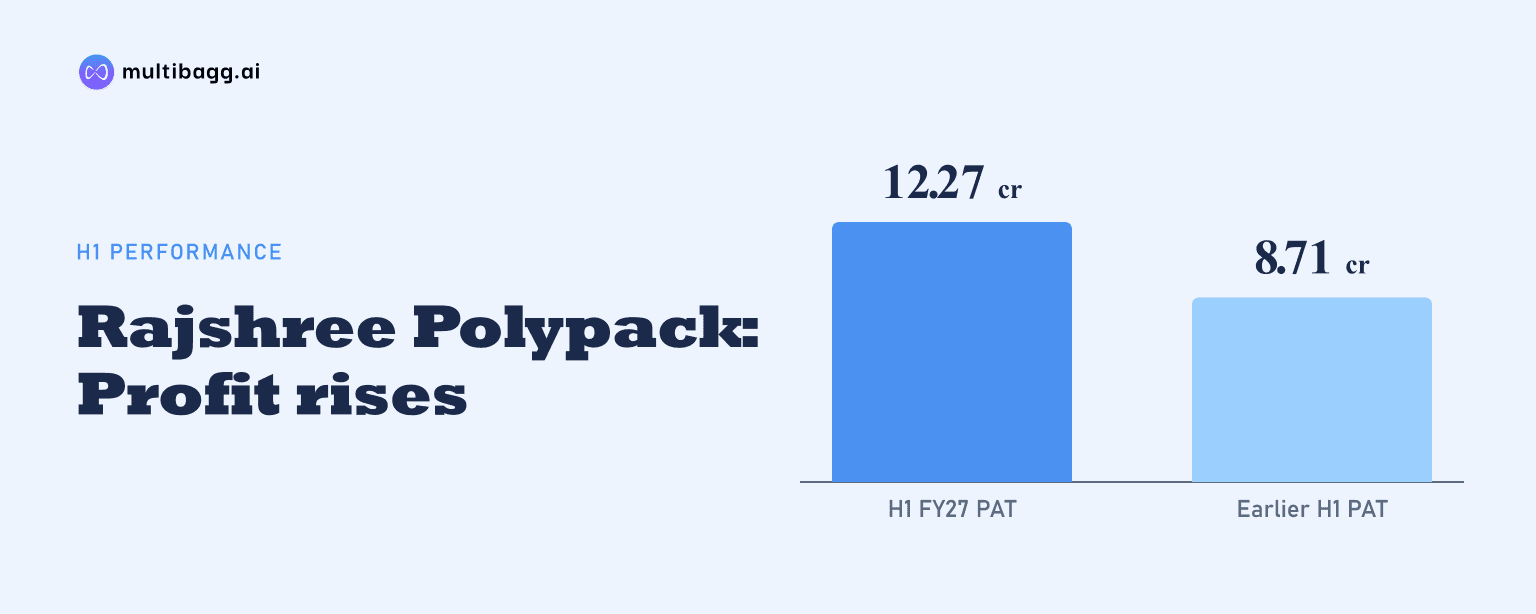
Rajshree Polypack Limited increased standalone profit after tax by 41% year on year to Rs 12.27 crore in the first half (H1) of financial year (FY) 2027, while operating earnings before interest, tax, depreciation and amortisation (operating EBITDA) margin rose 89 basis points, where 100 basis points equal one percentage point, to 13.35%.
Know Rajshree Polypack inside out
Results, valuation, peers and who's buying, in one view.
How did Rajshree Polypack perform in H1 FY27?
Rajshree Polypack reported H1 FY27 revenue from operations of Rs 205.81 crore, up Rs 36.86 crore from Rs 168.95 crore in H1 FY26. This followed revenue of Rs 166.98 crore in H1 FY25, meaning the latest first-half revenue was Rs 38.83 crore above the level two years earlier. The figures are standalone, covering the company’s own operations rather than a consolidated group result.
Profit after tax, or PAT, increased to Rs 12.27 crore in H1 FY27 from Rs 8.71 crore a year earlier, an increase of Rs 3.56 crore or 40.87%. PAT margin also rose to 5.96% from 5.15%, a gain of 81 basis points. In H1 FY25, PAT was Rs 9.13 crore and the margin was 5.47%, so both absolute profit and the ratio were above the two preceding first-half periods.
What changed in Rajshree Polypack’s operating profitability?
Rajshree Polypack’s operating EBITDA increased by Rs 6.42 crore to Rs 27.47 crore in H1 FY27. That 30.50% increase outpaced the 21.82% rise in revenue, lifting operating EBITDA margin to 13.35%. The margin remained 20 basis points below H1 FY25’s 13.55%, but recovered 89 basis points from H1 FY26’s 12.46%.
Reported EBITDA was Rs 30.11 crore in H1 FY27 versus Rs 24.96 crore in H1 FY26, a 20.63% increase in rupee terms. However, its reported margin declined by 15 basis points to 14.63% from 14.78%. The first-half results therefore show expansion in operating EBITDA margin while the reported EBITDA margin moved modestly lower, although both measures increased in absolute rupees.
Management said sharp raw-material price increases and softer export demand amid geopolitical uncertainty affected the period, while robust domestic demand more than offset lower exports. It also said Rajshree Polypack is increasing the share of value-added products and expanding its injection moulding range for the domestic market, measures intended to give it flexibility to rebalance sales when export markets are disrupted.
How did Rajshree Polypack’s second quarter (Q2) FY27 compare?
Rajshree Polypack recorded Q2 FY27 revenue of Rs 102.90 crore, nearly unchanged from Rs 102.91 crore in Q1 FY27 and 19.06% above Rs 86.43 crore in Q2 FY26. Q2 therefore accounted for almost half of the Rs 205.81 crore reported for H1 FY27. The year-on-year quarterly revenue increase shows that the first-half expansion included a larger second quarter than the comparable prior-year quarter.
Quarterly profitability was lower than in Q1 FY27 but higher than in Q2 FY26 in rupee terms. Q2 FY27 operating EBITDA was Rs 13.05 crore, compared with Rs 14.42 crore in Q1 FY27 and Rs 10.94 crore in Q2 FY26; its margin was 12.69%, against 14.01% and 12.66%, respectively. PAT was Rs 5.02 crore in Q2 FY27, below Rs 7.26 crore in Q1 but above Rs 4.60 crore a year earlier.
Reported Q2 EBITDA was Rs 13.60 crore and its margin was 13.21%, compared with Rs 16.52 crore and 16.05% in Q1 FY27. Against Q2 FY26, reported EBITDA increased from Rs 12.89 crore, although the margin fell from 14.91%. This sequential movement helps explain why H1 operating margin improved from the prior year while the reported EBITDA margin for the half year edged down.
Got a follow-up? Ask IRIS
What capacity and balance-sheet measures support Rajshree Polypack’s results?
Rajshree Polypack expanded extrusion capacity to 25,600 metric tonnes, or MT, in Q2 FY27 from 24,000 MT in Q2 FY26. Injection moulding capacity rose to 5,800 MT from 4,800 MT, while sleeving capacity increased to 1,675 lakh pieces from 1,275 lakh pieces. Thermoforming capacity stayed at 12,120 MT and printing capacity at 11,000 lakh pieces over the same comparison.
Production metrics show differing trends across processes in Q2 FY27. Extrusion production rose to 5,743 MT from 5,052 MT in Q2 FY26, and thermoforming increased to 2,212 MT from 1,996 MT. Printing increased to 1,718 lakh pieces from 1,342 lakh pieces and sleeving rose to 347 lakh pieces from 185 lakh pieces, whereas injection moulding production declined to 511 MT from 1,178 MT despite the higher installed capacity.
Rajshree Polypack’s total debt was broadly unchanged at Rs 106.56 crore at H1 FY27 versus Rs 106.47 crore at FY26, while cash and cash equivalents rose to Rs 5.30 crore from Rs 5.03 crore. Net debt consequently fell by Rs 17 lakh to Rs 101.27 crore and total equity rose by Rs 12.28 crore to Rs 200.33 crore. Debt excludes lease liabilities of Rs 14.89 crore at September 2026.
Debt-to-equity declined to 0.53 times in H1 FY27 from 0.57 times at FY26. Receivables days reduced to 58.81 from 62.62, while inventory days declined to 127.30 from 161.07 and payables days increased to 45.16 from 35.31. Cash flow from operations was Rs 17.72 crore in H1 FY27, compared with Rs 18.80 crore for the full FY26.
Conclusion
Rajshree Polypack converted a 21.82% increase in H1 FY27 revenue into faster growth in operating EBITDA and PAT. The central contrast is that operating EBITDA margin improved by 89 basis points to 13.35%, while reported EBITDA margin declined by 15 basis points to 14.63%; PAT margin nevertheless rose by 81 basis points to 5.96%. Higher extrusion, thermoforming, printing and sleeving production accompanied the first-half revenue and earnings gains.
The next items to watch are management’s stated expansion of domestic injection moulding and value-added products, and the newly commissioned group captive wind-solar plant, which management said will make a meaningful profitability contribution from next year. Management also said Olive Ecopak was profitable at the profit-before-tax level before an exceptional flood-loss item, with its insurance claim still under process, leaving that resolution as a disclosed outstanding matter.