










Raymond Realty says non-Thane projects supplied 57% bookings
Key highlights
- Raymond Realty’s H1 FY27 booking value rose 111% year on year to Rs 1,602 crore.
- Non-Thane projects contributed 57% of booking value, compared with 43% from Thane projects.
- Q2 FY27 customer collections increased 67% to Rs 682 crore, while EBITDA reached Rs 115 crore.
- Raymond Realty ended Q2 FY27 with net debt of Rs 912 crore and a debt-to-equity ratio of 0.8 times.
powered by IRIS
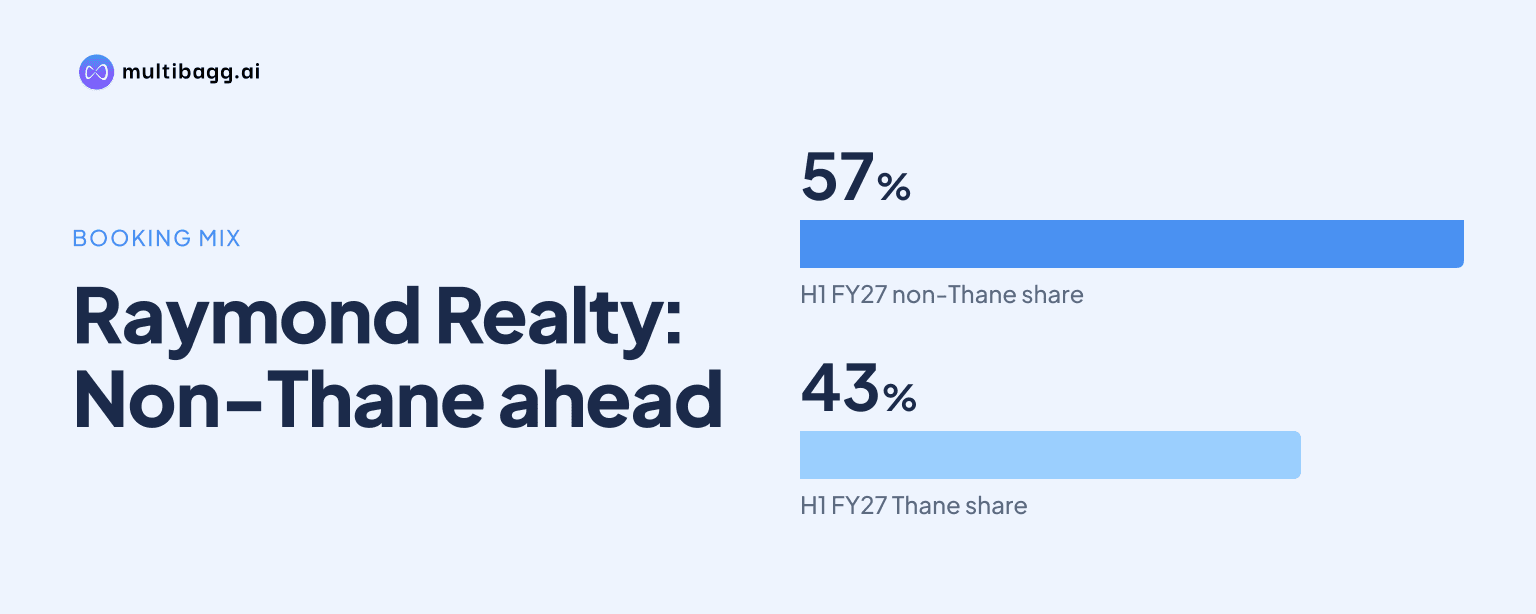
Raymond Realty Limited nearly doubled Q2 FY27 pre-sales without new launches, management said, as existing projects saw faster absorption at steady prices. The sales mix shifted beyond its original Thane land bank: non-Thane projects produced 57% of booking value, while H1 FY27 booking value increased 111% year on year to Rs 1,602 crore.
Know Raymond Realty inside out
Results, valuation, peers and who's buying, in one view.
Why did Raymond Realty’s Q2 FY27 pre-sales rise without launches?
Raymond Realty said Q2 FY27 pre-sales nearly doubled because of robust sales velocity and steady price realisations in its existing portfolio, not fresh launches. For the quarter ended September 30, 2026, total income rose 7% year on year to Rs 757 crore.
The company did not disclose an absolute Q2 booking value or a percentage growth rate for that quarter in the call. It reported H1 FY27 booking value of Rs 1,602 crore, up 111% year on year, indicating that the stated sales momentum came from projects already available for sale.
Management separately identified two Mahim launches planned for H2 FY27, with combined gross development value, or GDV, of about Rs 4,100 crore. Those projects were not part of the Q2 result, because Raymond Realty said it made no new launches during the quarter.
How much of Raymond Realty’s bookings came from outside Thane?
Raymond Realty said non-Thane projects contributed 57% of pre-sale value during the reported period, compared with 43% from the Thane owned-land portfolio. Management expects the mix to tilt further toward non-Thane projects because it expects most growth outside Thane.
The booking split was slightly more weighted to non-Thane projects than the group’s GDV allocation. Thane has revenue potential of Rs 25,000 crore, while joint-development-agreement, or JDA, projects represent Rs 27,000 crore, or about 52%, of total portfolio GDV of approximately Rs 52,000 crore.
Management said the larger booking contribution from JDAs reflects their presence across several micro-markets, compared with one Thane land parcel. It named Bandra, BKC, Wadala and Sion as four launched JDA projects that have generated sales value of Rs 3,432 crore and collections of Rs 857 crore over the 2.5 to three years since the model began.
What does the booking mix show about Raymond Realty’s strategy?
Raymond Realty’s 57% non-Thane booking contribution shows that its JDA expansion is already supplying current sales as well as future GDV. Management said JDA projects span multiple micro-markets and offer a larger growth opportunity than the original Thane platform.
Thane remains a substantial operating base. About 65 acres of the 100-acre parcel are under development, representing about 6.7 million square feet of Real Estate Regulatory Authority, or RERA, carpet area and revenue potential of Rs 16,500 crore; Raymond Realty has sold Rs 9,770 crore and collected Rs 7,977 crore from this under-development potential since the business began.
The model carries a different cash-flow profile by project stage. Management said a new JDA is normally cash-flow negative for its first two years because of upfront investment, and becomes cash-flow positive from the third year or the middle of that year; it estimated a steadier position within two years, with eight to 10 non-Thane projects under execution.
Got a follow-up? Ask IRIS
Did bookings translate into collections and earnings in Q2 FY27?
Yes. Raymond Realty reported Q2 FY27 customer collections of Rs 682 crore, up 67%, while H1 FY27 collections reached Rs 1,233 crore. The difference between 111% H1 booking growth and the 67% quarterly collection increase reflects the different timing of sales bookings and customer receipts.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, reached Rs 115 crore in Q2 FY27, and the EBITDA margin increased to 15% from 14% in the corresponding quarter. Management attributed the result to product mix and cost management, while saying margins can vary by project phase because marketing and construction setup costs occur early.
Management maintained its FY27 EBITDA margin guidance of 17% to 19%, minimum pre-sales growth guidance of 20%, return on capital employed target of 20%, and profit-after-tax margin guidance of 9% to 10%. It did not provide FY27 revenue-growth guidance, citing the moving parts in percentage-completion accounting across a larger project base.
What operational and funding milestones support Raymond Realty’s plans?
Raymond Realty received an occupation certificate in Q2 FY27 for Address by GS 1 Tower B in Thane, comprising 270 units and almost 3.5 lakh square feet. Management said the tower was delivered ahead of its RERA completion timeline.
The company added a Parel project with approximately Rs 8,500 crore of GDV in H1 FY27, taking the portfolio to about Rs 52,000 crore. The planned Mahim launches in H2 FY27, carrying about Rs 4,100 crore of combined GDV, are the next disclosed additions to the sales pipeline.
Raymond Realty closed Q2 FY27 with net debt of Rs 912 crore, gross debt of about Rs 1,200 crore, and debt-to-equity of 0.8 times. It also reported a Rs 308 crore liquidity buffer and 9.6% cost of debt, while a subsidiary raised Rs 210 crore from an alternative investment fund promoted by ICICI Prudential AMC Limited.
Conclusion
Raymond Realty’s Q2 sales momentum came from absorption in its existing portfolio rather than new supply. The 57% booking contribution from non-Thane projects, versus 43% from Thane, indicates that JDA-led projects have become the larger current source of bookings, alongside H1 booking value of Rs 1,602 crore and collections of Rs 1,233 crore.
The next measures to watch are the two Mahim launches planned in H2 FY27 and whether the non-Thane booking mix continues to rise as management expects. Management also retained its FY27 targets for at least 20% pre-sales growth and a 17% to 19% EBITDA margin, while estimating that JDA cash flows could stabilise within two years as projects mature.