










Relaxo Q2 revenue rises 12% as pairs sold decline 10%
Key highlights
- Relaxo's Q2 FY27 revenue rose to Rs 702 crore from Rs 629 crore in Q2 FY26.
- Q2 FY27 pairs sold fell to 3.7 crore from 4.1 crore, while average realisation rose to Rs 186 from Rs 151.
- Q2 FY27 EBITDA margin was 12.2%, down from 12.9% a year earlier and 15.4% in Q1 FY27.
- H1 FY27 PAT increased to Rs 92 crore from Rs 85 crore, while PAT margin edged down to 6.5% from 6.6%.
powered by IRIS
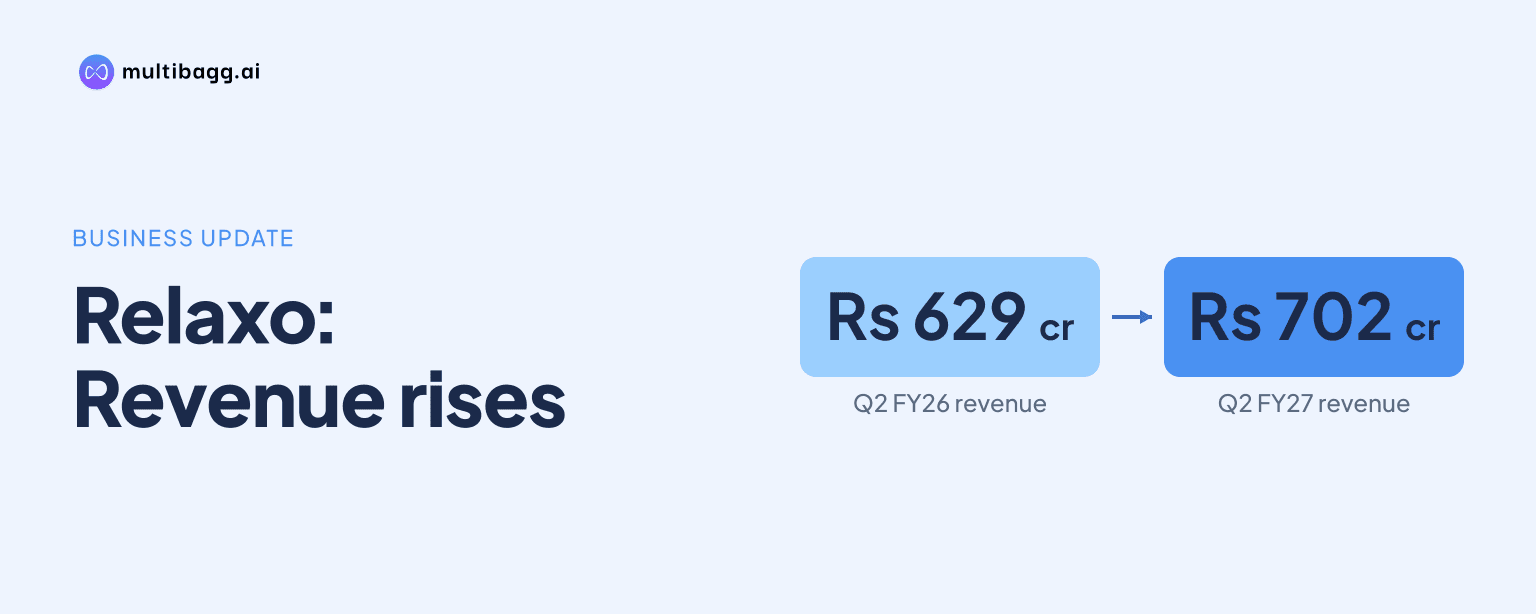
Relaxo’s Q2 FY27 revenue rose 12% year on year to Rs 702 crore, as average realisation per pair increased to Rs 186 despite pairs sold declining 10% to 3.7 crore. The quarter therefore delivered higher reported sales through revenue per pair, while profitability margins were lower than both Q2 FY26 and Q1 FY27.
Know Relaxo Footwears inside out
Results, valuation, peers and who's buying, in one view.
Why did Relaxo's Q2 FY27 revenue rise?
Relaxo’s Q2 FY27 revenue increased because the Rs 35 rise in average realisation per pair more than offset the 0.4 crore fall in pairs sold. Revenue was Rs 702 crore against Rs 629 crore in Q2 FY26, while average realisation rose from Rs 151 to Rs 186 and volume decreased from 4.1 crore pairs to 3.7 crore pairs.
The comparison shows that revenue growth was led by realisation rather than unit sales. At Rs 186, Q2 FY27 average realisation was Rs 35 above Q2 FY26 and Rs 20 above Q1 FY27’s Rs 166. Meanwhile, Q2 FY27 pairs sold were 0.5 crore below Q1 FY27’s 4.2 crore as well as 0.4 crore below the year-earlier quarter.
The presentation does not separate the Rs 35 increase in average realisation into price changes and product-mix changes. It therefore supports the conclusion that sales growth was realisation-led, but it does not establish how much came from pricing, a change in products sold, or another factor within the sales mix.
How did Relaxo's Q2 FY27 margins change?
Relaxo’s Q2 FY27 operating and profit margins declined from Q2 FY26 and Q1 FY27 even though absolute earnings were higher than a year earlier. Earnings before interest, tax, depreciation and amortisation (EBITDA) were Rs 85 crore, up from Rs 81 crore in Q2 FY26, but the EBITDA margin fell to 12.2% from 12.9%.
Earnings before interest and tax (EBIT) increased to Rs 56 crore from Rs 54 crore year on year, while its margin declined by 0.6 percentage points to 8.0%. Profit before tax (PBT) rose by Rs 1 crore to Rs 50 crore, but the PBT margin decreased to 7.1% from 7.8%. Profit after tax (PAT) increased to Rs 37 crore from Rs 36 crore, while the PAT margin fell to 5.3% from 5.8%.
The sequential comparison was more pronounced for absolute profits. Q2 FY27 EBITDA of Rs 85 crore was below Rs 108 crore in Q1 FY27, with the margin down from 15.4% to 12.2%. PAT declined from Rs 55 crore in Q1 FY27 to Rs 37 crore in Q2 FY27, and the PAT margin decreased from 7.8% to 5.3%.
Cash PAT, which the presentation reports separately, was Rs 76 crore in Q2 FY27 compared with Rs 73 crore in Q2 FY26. Its margin moved down to 10.8% from 11.6%, and it was also below Q1 FY27 cash PAT of Rs 93 crore and its 13.2% margin. The disclosed figures show lower conversion of revenue into these reported profit measures during the quarter.
Got a follow-up? Ask IRIS
What do Relaxo's first-half FY27 figures show?
Relaxo’s H1 FY27 results show revenue and earnings growth in absolute terms, alongside lower sales volume and narrower EBITDA and cash PAT margins. H1 FY27 revenue was Rs 1,407 crore, Rs 124 crore above Rs 1,283 crore in H1 FY26, while pairs sold decreased from 8.4 crore to 7.9 crore.
Average realisation in H1 FY27 rose to Rs 176 per pair from Rs 151 in H1 FY26, a Rs 25 increase. This period-level change aligns with the Q2 pattern: higher revenue per pair compensated for lower pairs sold. Q2 FY27’s Rs 186 realisation was also Rs 10 higher than the H1 FY27 average, indicating that the second quarter had the higher realisation of the two reported FY27 quarters.
H1 FY27 EBITDA rose to Rs 193 crore from Rs 181 crore, although the margin declined to 13.8% from 14.1%. EBIT increased from Rs 125 crore to Rs 137 crore and retained a 9.8% margin. PBT rose from Rs 115 crore to Rs 125 crore with an unchanged 8.9% margin, while PAT increased from Rs 85 crore to Rs 92 crore and its margin edged down from 6.6% to 6.5%.
Cash PAT for H1 FY27 was Rs 169 crore against Rs 160 crore in H1 FY26, but its margin declined by 0.5 percentage points to 12.0%. Thus, the half-year figures differ from Q2 in one respect: EBIT and PBT margins were stable year on year in H1, whereas both declined in Q2.
How does Relaxo's Q2 FY27 compare with recent quarters?
Relaxo’s Q2 FY27 revenue was broadly flat sequentially but lower than the preceding two reported quarters in FY26. Revenue of Rs 702 crore was Rs 3 crore below Q1 FY27’s Rs 705 crore, Rs 49 crore below Q4 FY26’s Rs 751 crore, and Rs 34 crore above Q3 FY26’s Rs 668 crore.
Volume declined across the two FY27 quarters shown. Pairs sold moved from 4.2 crore in Q1 FY27 to 3.7 crore in Q2 FY27, while average realisation increased from Rs 166 to Rs 186. Q2 FY27 realisation was the highest of the five-quarter series, exceeding the Rs 164 reported in Q3 FY26 and the Rs 150 reported in Q4 FY26.
Profitability in Q2 FY27 was below Q1 FY27 but above Q3 FY26 on several measures. EBITDA margin was 12.2% in Q2 FY27, compared with 15.4% in Q1 FY27 and 10.4% in Q3 FY26; PAT margin was 5.3%, compared with 7.8% and 4.0%, respectively. Q4 FY26 remains the high point in the displayed series, with Rs 124 crore EBITDA and a 16.5% EBITDA margin.
Conclusion
Relaxo’s Q2 FY27 outcome was higher revenue with fewer pairs sold, driven by average realisation rising to Rs 186 per pair. The same pattern is visible in H1 FY27, where revenue increased to Rs 1,407 crore while volume fell to 7.9 crore pairs. However, Q2 EBITDA, PBT, PAT and cash PAT margins all declined from both the year-earlier and immediately preceding quarters.
The next reported quarter will show whether sales volume recovers from Q2 FY27’s 3.7 crore pairs and whether the Rs 186 realisation level persists. The presentation provides no FY27 revenue, volume, realisation or margin target, leaving the durability of the realisation-led growth pattern unresolved in the disclosed information.