










Rishabh Instruments Limited revenue rises 29.6%, margin falls
Key highlights
- Rishabh standalone H1FY27 revenue rose 29.6% to Rs 165.6 crore.
- Rishabh reported standalone EBITDA margin declined 190 basis points to 22.7% in H1FY27.
- Rishabh standalone gross margin fell 450 basis points to 51.4%, which management attributed to product mix.
- Rishabh Electrical and Electronic Instruments revenue grew 29.3% to Rs 325.5 crore in H1FY27.
powered by IRIS
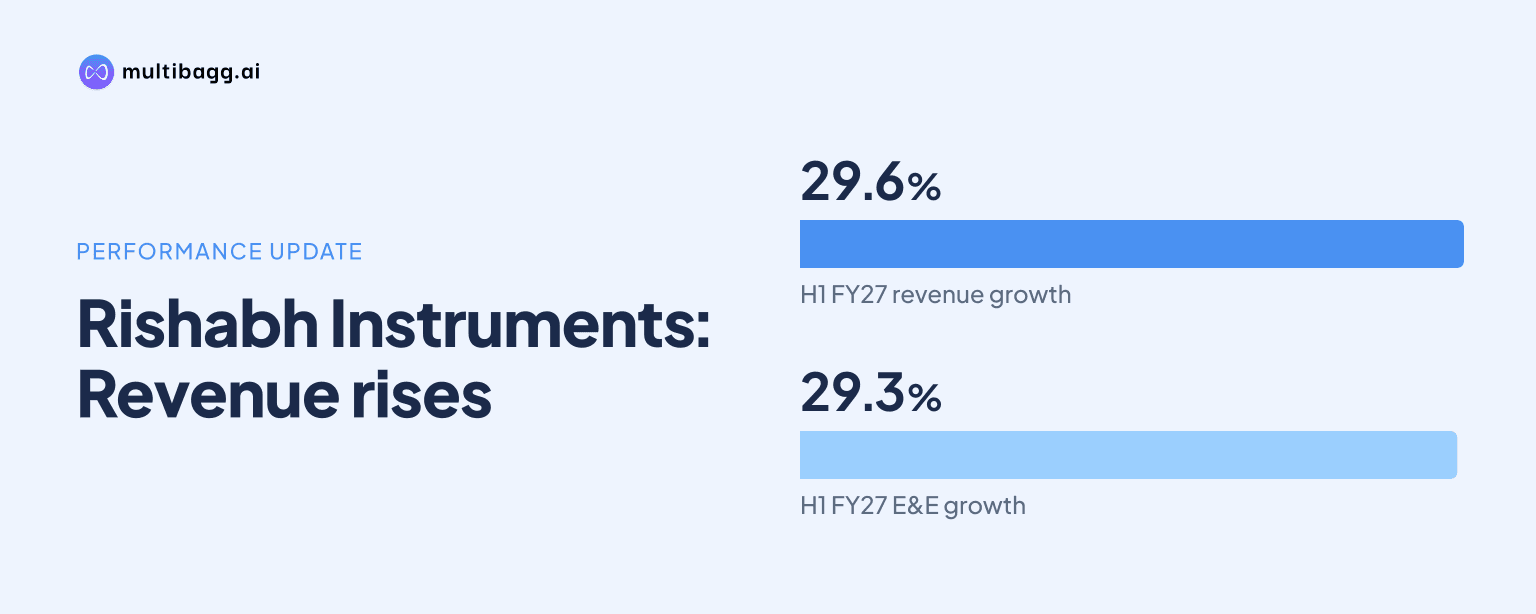
Rishabh Instruments Limited reported standalone revenue of Rs 165.6 crore in H1FY27, up 29.6% year on year, while reported EBITDA margin fell 190 basis points to 22.7% as management attributed the gross-margin decline to a changed product mix. Profit after tax rose 12.8% to Rs 25.4 crore.
Know Rishabh Instruments inside out
Results, valuation, peers and who's buying, in one view.
How fast did Rishabh’s standalone revenue grow?
Rishabh’s standalone revenue from operations increased to Rs 165.6 crore in H1FY27 from Rs 127.8 crore in H1FY26, adding Rs 37.8 crore. Growth accelerated in Q2FY27, when revenue rose 33.3% year on year to Rs 88 crore from Rs 66 crore, compared with the 29.6% increase for the first half.
Reported earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 19.6% to Rs 37.6 crore in H1FY27 from Rs 31.5 crore. Profit after tax, or PAT, grew 12.8% to Rs 25.4 crore from Rs 22.5 crore. Both rates were below revenue growth, indicating that the additional sales generated less profit at successive levels of the income statement.
The Q2 comparison shows the same pattern. Revenue rose by Rs 22 crore, but reported EBITDA rose 15.5% to Rs 19.9 crore and PAT increased 7.0% to Rs 13.5 crore. Gross profit increased 17.6% to Rs 44.3 crore, below quarterly revenue growth of 33.3%.
Why did Rishabh’s standalone margins decline?
Rishabh said its gross-margin decline resulted from a change in product mix. Gross margin fell 450 basis points to 51.4% in H1FY27 from 55.9% in H1FY26, as cost of goods sold increased to Rs 80.5 crore from Rs 56.3 crore. Gross profit therefore grew 19.1% to Rs 85.1 crore, slower than the 29.6% rise in revenue.
The margin movement was larger in Q2FY27, when gross margin fell 670 basis points to 50.3% from 57.1%. Quarterly cost of goods sold increased to Rs 43.7 crore from Rs 28.3 crore, while gross profit rose to Rs 44.3 crore from Rs 37.7 crore.
Reported EBITDA margin declined to 22.7% in H1FY27 from 24.6%, a 190-basis-point reduction. Adjusted EBITDA, excluding employee stock option plan costs and Stock Appreciation Rights, or SAR, was Rs 38.5 crore and its margin was 23.3%, down 280 basis points from 26.0%. Employee stock option plan and SAR costs declined to Rs 0.9 crore from Rs 1.8 crore.
In Q2FY27, reported EBITDA margin declined 350 basis points to 22.6%, while adjusted EBITDA margin fell 430 basis points to 23.1%. The wider adjusted-margin reduction reflects the lower employee stock option plan and SAR costs in the current quarter, which partly narrowed the decline in reported EBITDA margin.
Got a follow-up? Ask IRIS
How did costs affect Rishabh’s standalone profit?
Rishabh’s employee cost increased to Rs 24.6 crore in H1FY27 from Rs 20.7 crore, and other expenses rose to Rs 22 crore from Rs 17.5 crore. Together, these two expense lines rose by Rs 8.4 crore, compared with a Rs 13.6 crore increase in gross profit, leaving reported EBITDA growth below revenue growth.
Depreciation increased to Rs 9.1 crore from Rs 8.2 crore, while other income declined to Rs 5.6 crore from Rs 7.1 crore. Earnings before interest and tax rose 12.4% to Rs 34.2 crore, but its margin fell 320 basis points to 20.6%. Finance cost remained Rs 0.2 crore, and profit before tax increased 12.6% to Rs 34 crore.
PAT margin declined to 15.3% in H1FY27 from 17.6% in H1FY26, a reduction of 230 basis points in the profit and loss statement. Tax rose to Rs 8.6 crore from Rs 7.7 crore. In Q2FY27, PAT margin was 15.4%, down 380 basis points, as PAT rose 7.0% to Rs 13.5 crore.
How did Rishabh’s standalone result compare with consolidated and segment performance?
Rishabh’s standalone revenue growth of 29.6% exceeded consolidated revenue growth of 6.3% in H1FY27. Consolidated revenue reached Rs 411.1 crore from Rs 386.7 crore, while reported EBITDA increased 6.4% to Rs 65.7 crore. Consolidated reported EBITDA margin was unchanged at 16.0%, compared with the standalone margin decline to 22.7%.
Consolidated PAT declined 10.1% to Rs 37.5 crore from Rs 41.7 crore, unlike the 12.8% rise in standalone PAT. Consolidated gross margin fell 250 basis points to 60.4%, and PAT margin declined 170 basis points to 9.1%. The consolidated statement included a Rs 2.5 crore one-time provision for withholding tax in H1FY27, as well as Rs 3.6 crore of employee stock option plan and SAR costs.
The Electrical and Electronic Instruments segment, which contributed about 79% of consolidated revenue, grew 29.3% to Rs 325.5 crore in H1FY27. Its adjusted EBITDA rose 29.9% to Rs 75 crore and adjusted EBITDA margin increased 10 basis points to 23.1%. In contrast, High Pressure Die Casting revenue declined 36.6% to Rs 85.5 crore and adjusted EBITDA moved to a loss of Rs 3.2 crore from a profit of Rs 7.8 crore.
Management said High Pressure Die Casting had reached operating-level breakeven and expects the segment to remain breakeven on an adjusted EBITDA basis for full FY27. Management also said it continues to prioritise sustainable profitability over volume in that business, making the segment’s delivery against the stated target material to the consolidated result.
Conclusion
Rishabh’s H1FY27 standalone result paired revenue growth of Rs 37.8 crore with slower increases in gross profit, reported EBITDA and PAT. Management attributed the 450-basis-point gross-margin reduction to product mix, while reported EBITDA margin declined 190 basis points and PAT margin declined 230 basis points.
For the remainder of FY27, management has identified improved product mix, new products in energy meters, medium-voltage products, automation and solar inverters, and geographic expansion across the US, Africa and Southeast Asia as priorities. The disclosed target to watch is High Pressure Die Casting adjusted EBITDA breakeven for full FY27 after its Rs 3.2 crore H1FY27 loss.