










Rubicon lifts FY27 operating EBITDA margin outlook to 24% plus
Key highlights
- Rubicon lifted FY27 operating EBITDA margin guidance to 24% plus from about 23% plus previously.
- Q2 FY27 revenue from operations rose 40% year on year to Rs 576 crore.
- Q2 FY27 operating EBITDA increased 53% year on year to Rs 144 crore.
- First-half FY27 profit after tax rose 80% year on year to Rs 175 crore.
powered by IRIS
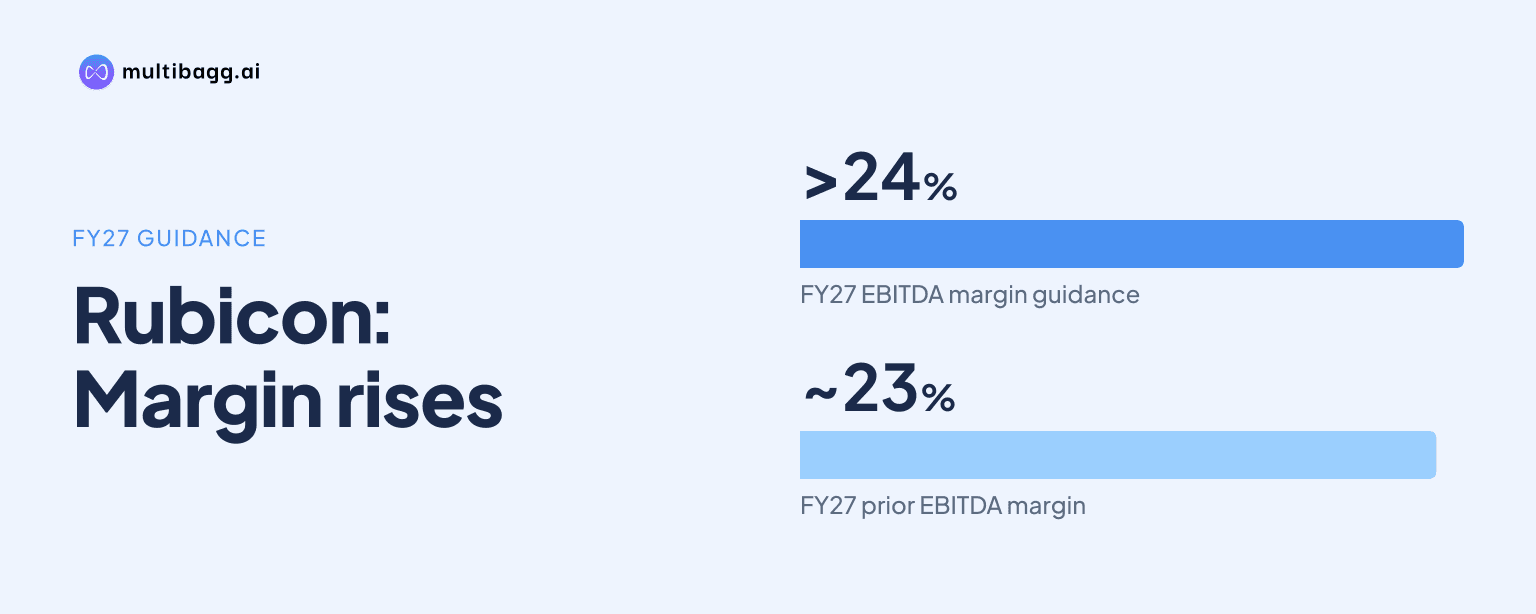
Rubicon Research Limited lifted its FY27 operating earnings before interest, tax, depreciation and amortisation (EBITDA) margin guidance to 24% plus after reporting Q2 FY27 operating EBITDA of Rs 144 crore, up 53% year on year, on revenue from operations of Rs 576 crore. Management reported a 25% operating EBITDA margin for the quarter despite geopolitical conditions.
Know Rubicon Research inside out
Results, valuation, peers and who's buying, in one view.
Why did Rubicon lift its FY27 operating EBITDA margin outlook?
Rubicon raised its FY27 operating EBITDA margin guidance to 24% plus from the about-23%-plus outlook it gave in the prior quarter. Management said Q2 FY27 operating EBITDA margin was 25%, above the revised full-year threshold.
The guidance revision followed Q2 FY27 operating EBITDA of Rs 144 crore, compared with Rs 94 crore in Q2 FY26, while revenue from operations rose to Rs 576 crore from Rs 412 crore. Management said it had delivered EBITDA growth despite difficult geopolitical situations, but did not quantify the financial impact of those conditions.
Rubicon distinguishes operating EBITDA from EBITDA including other income. EBITDA including other income was Rs 146 crore in Q2 FY27, up from Rs 95 crore a year earlier, while the margin guidance refers to operating EBITDA of Rs 144 crore.
How did Rubicon's Q2 FY27 results compare with earlier periods?
Rubicon's Q2 FY27 revenue from operations increased 40% year on year to Rs 576 crore, while profit after tax rose to Rs 90 crore from Rs 54 crore. Sequentially, revenue increased from Rs 534 crore in Q1 FY27 and profit after tax rose from Rs 85 crore, which included a one-time insurance claim of Rs 3.6 crore.
Operating pre-research and development (R&D) EBITDA rose to Rs 206 crore from Rs 141 crore, and its margin increased to 35.8% from 34.1%. R&D expense was Rs 62 crore, or 10.8% of quarterly revenue, which management said was in line with Q2 FY26 and Q1 FY27.
For the first half ended September, Rubicon reported revenue of Rs 1,111 crore, up 45% year on year. First-half operating EBITDA rose 57.5% to Rs 273 crore and profit after tax increased 80% to Rs 175 crore, meaning both measures grew faster than revenue over the six-month period.
What supported Rubicon's Q2 margin delivery?
Rubicon attributed Q2 FY27 growth to broad-based product performance, stable pricing and its specialty or differentiated portfolio. Specialty products contributed 36% of gross profit, while management said the top five and top 10 products stayed within a narrow range across four sequential quarters.
Sequential United States dollar revenue grew 5% in Q2 FY27 after tactical measures had paused sequential growth in Q1 FY27. Management said it had strong visibility in coming quarters, although it gave no US revenue target or product-level sales forecast.
Arinna Lifesciences was consolidated in FY27 figures and contributed Rs 19.4 crore of revenue, but management said its EBITDA contribution was not material. The source therefore does not provide an organic Q2 FY27 revenue growth measure excluding Arinna.
Got a follow-up? Ask IRIS
What could affect Rubicon's FY27 revenue and margin delivery?
Rubicon said revised Indian export-licensing procedures could move launches of some approved products into coming quarters. The company received three approvals in Q2 FY27 and reported an 84% commercialization rate, but said it can now seek an export licence only after United States Food and Drug Administration approval.
Before the licensing revision, Rubicon said it could prepare licences and manufactured inventory ahead of an expected approval. The changed process affects controlled as well as other products, though management did not identify the products whose launches could be deferred.
Manufacturing-site regulatory follow-through is another disclosed factor. Ambernath received five observations in October, comprising three systems-improvement observations and two linked to product applications under review; management said none concerned data integrity. Satara received one procedural observation in October, with its response submitted, while Pithampur received two observations in July and submitted its response that month.
Net working capital was 117 days at September 30, compared with 126 days in March 2026, although management expects it to normalise within 125 to 130 days. First-half operating cash flow was Rs 99 crore, while investing cash flow of Rs 172 crore reflected the Arinna acquisition, the New Jersey manufacturing-facility acquisition and capital expenditure.
How does Rubicon's R&D plan support later growth?
Rubicon spent Rs 120 crore on R&D in the first half ended September, equal to 10.8% of consolidated operating revenue. Management said annual R&D expenditure rose from about Rs 107 crore in FY24 to nearly Rs 194 crore in FY26, while the ratio had normalised to 10% to 11% of operating revenue after reaching about 40% in FY22.
Management's rolling analysis connected Rs 218.7 crore of reference-period R&D spending with an annualised FY27 product-sales figure of Rs 2,105 crore excluding Arinna, producing a stated 5.8-times productivity measure. It said the FY27 product-sales figure was an arithmetic annualisation of first-half revenue, not guidance for full-year revenue.
For the FY26, FY27 and Q1 FY28 spending cycle, Rubicon has guided for cumulative R&D expenditure of Rs 500 crore. Management said it had spent Rs 313 crore over six quarters and had visibility to complete the programme over the remaining three quarters, with revenue effects assessed over later three-year periods.
Conclusion
Rubicon's revised 24%-plus FY27 operating EBITDA margin outlook is supported by a Q2 operating margin of 25%, 53% growth in operating EBITDA to Rs 144 crore and 40% revenue growth to Rs 576 crore. First-half figures also showed operating EBITDA and profit after tax increasing faster than revenue, while specialty products supplied 36% of gross profit.
The next disclosures to watch are the timing of launches affected by the revised export-licensing process, the outcomes of observations at Ambernath, Satara and Pithampur, and completion of the Rs 500 crore R&D cycle over three remaining quarters. Management also expects net working capital to return to a range of 125 to 130 days from 117 days at September 30.