










Sanghvi has ₹401 crore FY27 capex left after H1 deployment
Key highlights
- Sanghvi had ₹401 crore, or 69% of its ₹583 crore FY27 capex pool, pending after H1 FY27.
- Sanghvi capitalised ₹182 crore in H1 FY27, including ₹112 crore in India and ₹70 crore in Saudi Arabia.
- Sanghvi’s consolidated gross debt rose to ₹805 crore in H1 FY27 from ₹674 crore in FY26.
- Sanghvi’s consolidated free cash flow to firm turned positive at ₹16 crore in H1 FY27 from negative ₹98 crore in FY26.
powered by IRIS
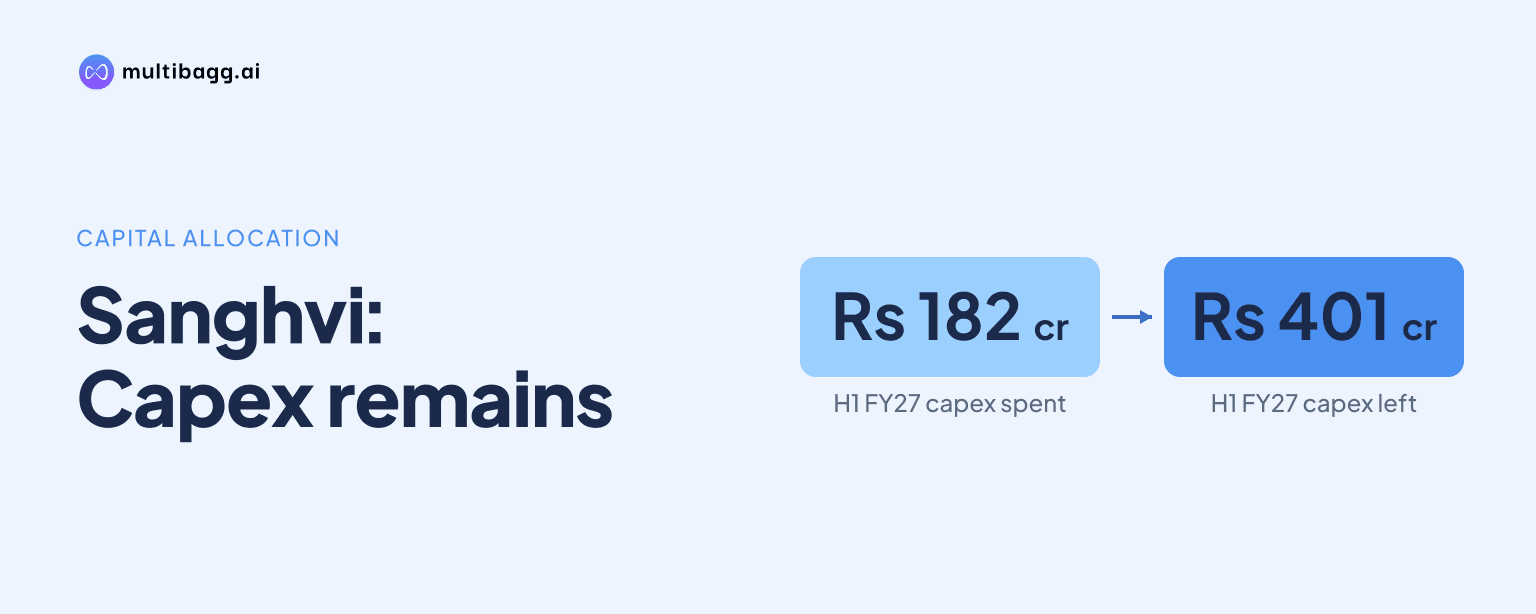
In H1 FY27, Sanghvi Movers Limited had ₹401 crore, or 69% of its ₹583 crore capital-expenditure pool, still pending after capitalising ₹182 crore, while consolidated gross debt rose 19.4% to ₹805 crore and free cash flow to firm turned positive at ₹16 crore.
Know Sanghvi Movers inside out
Results, valuation, peers and who's buying, in one view.
How much FY27 capex does Sanghvi still need to deploy?
Sanghvi had ₹401 crore of FY27 capex pending at the end of H1 FY27, after capitalising ₹90 crore in Q2 FY27 and ₹182 crore over the first half. The H1 capitalisation represented 31% of the ₹583 crore available pool, leaving 69% scheduled for H2 FY27.
The ₹583 crore pool combines ₹167 crore carried forward from FY26 with ₹416 crore approved by the Board of Directors on 02 November 2026. The carried-forward balance represented 29% of available capex, and Sanghvi classified ₹560 crore, or 96%, of the total pool as revenue-generating investment.
Sanghvi classified the remaining ₹23 crore as non-revenue-generating capex for buildings, information-technology infrastructure, browsers and other operational assets. Revenue-generating expenditure totalled ₹560 crore across the ₹583 crore pool, indicating that the programme was principally directed to operating assets rather than support infrastructure.
How is Sanghvi’s capex split between India and Saudi Arabia?
Sanghvi allocated ₹337 crore of available FY27 capex to India and ₹246 crore to Saudi Arabia, leaving ₹225 crore and ₹176 crore, respectively, pending after H1 FY27. India therefore had the larger absolute allocation and pending balance, although its H1 capitalisation rate was higher than Saudi Arabia’s.
India capitalised ₹112 crore, or 33% of its ₹337 crore pool, in H1 FY27, compared with ₹70 crore, or 28% of Saudi Arabia’s ₹246 crore pool. India’s available capex included ₹324 crore of revenue-generating expenditure and ₹13 crore of non-revenue-generating expenditure, while Saudi Arabia’s allocation comprised ₹236 crore and ₹10 crore, respectively.
Sanghvi said shipping disruptions and port congestion had shifted ₹80 crore of Sanghvi Movers Middle East Ltd. capital deployment from FY27 to FY28. Saudi Arabia accounted for ₹176 crore of the group’s stated FY27 pending capex, but the presentation did not separately reconcile the ₹80 crore moved to FY28 against the ₹176 crore balance.
How has Sanghvi’s balance sheet changed during capex deployment?
Sanghvi reported higher consolidated debt alongside positive free cash flow to firm in H1 FY27, with gross debt rising to ₹805 crore from ₹674 crore in FY26 and free cash flow to firm moving to ₹16 crore from negative ₹98 crore. Treasury holdings also increased to ₹414 crore from ₹342 crore over the same comparison.
Cash flow from operations was ₹231 crore in the six months to H1 FY27, equal to 83% of the ₹278 crore generated in the full FY26. Sanghvi’s cash-flow-from-operations-to-EBITDA ratio improved to 0.94 times from 0.65 times, with EBITDA meaning earnings before interest, tax, depreciation and amortisation.
The debt-to-equity ratio rose to 0.58 times from 0.51 times, while the debt-service coverage ratio remained 2.30 times. The interest-service coverage ratio declined to 8.92 times from 11.51 times, and the weighted average cost of borrowing increased to 8.28% in H1 FY27 from 8.12% in FY26.
Got a follow-up? Ask IRIS
What operating demand supports Sanghvi’s investment programme?
Sanghvi reported a 510-crane group fleet, a ₹1,582 crore order book as of 23 October 2025 and a ₹6,716 crore enquiry pipeline in H1 FY27. The order book comprised ₹683 crore for India crane rental, ₹45 crore for Gulf Cooperation Council crane rental and ₹854 crore for renewable engineering and construction.
India crane rental operated 456 cranes at 78% utilisation and a 2.24% yield, while Gulf Cooperation Council crane rental operated 54 cranes at 86% utilisation and a 3.80% yield. The Gulf business, comprising Sanghvi Movers Middle East Ltd. and the Qatar operation, reported ₹39 crore of total income and ₹1 crore of cash profit, compared with ₹406 crore and ₹144 crore, respectively, for India crane rental.
The renewable engineering and construction segment had the largest order book at ₹854 crore and enquiry pipeline at ₹4,837 crore. It generated ₹365 crore of total income and ₹37 crore of cash profit in H1 FY27, showing that Sanghvi’s group activity also includes an asset-light renewables business alongside crane-rental operations.
How did Sanghvi’s H1 FY27 earnings compare with prior periods?
Sanghvi’s consolidated revenue from operations increased to ₹657 crore in H1 FY27 from ₹483 crore in H1 FY26, while EBITDA before exceptional items rose to ₹245 crore from ₹195 crore. Profit after tax increased to ₹106 crore from ₹87 crore, and cash profit rose to ₹181 crore from ₹149 crore.
The quarterly comparison showed a lower Q2 FY27 run rate than Q1 FY27, with revenue from operations declining to ₹277 crore from ₹380 crore and EBITDA declining to ₹106 crore from ₹139 crore. Cash profit also fell to ₹78 crore from ₹104 crore between the two quarters, despite H1 FY27 remaining above H1 FY26 on each reported measure.
Crane rentals generated ₹175 crore of Q2 FY27 revenue and ₹81 crore of operational EBITDA, compared with ₹98 crore and ₹18 crore, respectively, from renewables engineering and construction. Q2 FY27 crane-rental results included a ₹9 crore insurance claim and ₹7 crore of related expenses reclassified within the segment for reporting purposes.
Conclusion
Sanghvi entered H2 FY27 with ₹401 crore of uncapitalised capex, including ₹225 crore in India and ₹176 crore in Saudi Arabia, from a ₹583 crore available pool. The programme is largely revenue-generating, while the balance-sheet comparison shows gross debt up by ₹131 crore from FY26 and free cash flow to firm turning positive at ₹16 crore in H1 FY27.
The next disclosed issue to watch is the timing of Saudi Arabian deployment, after shipping disruption and port congestion shifted ₹80 crore of Sanghvi Movers Middle East Ltd. capex from FY27 to FY28. Progress against the ₹401 crore pending balance, the ₹1,582 crore order book reported as of 23 October 2025 and the 86% Gulf utilisation rate will indicate how remaining operating-asset investment is deployed.