










Sanghvi Movers Limited targets Rs 1,900 crore FY28 income
Key highlights
- SML targets FY28 consolidated total income of Rs 1,800-1,900 crore.
- SML reported H1 FY27 total income of Rs 689 crore, up 38% from Rs 498 crore in H1 FY26.
- SML targets FY28 EBITDA of Rs 650-700 crore, compared with Rs 429 crore in FY26.
- SML targets a FY28 mix of 64% crane rental and 36% renewables E&C.
powered by IRIS
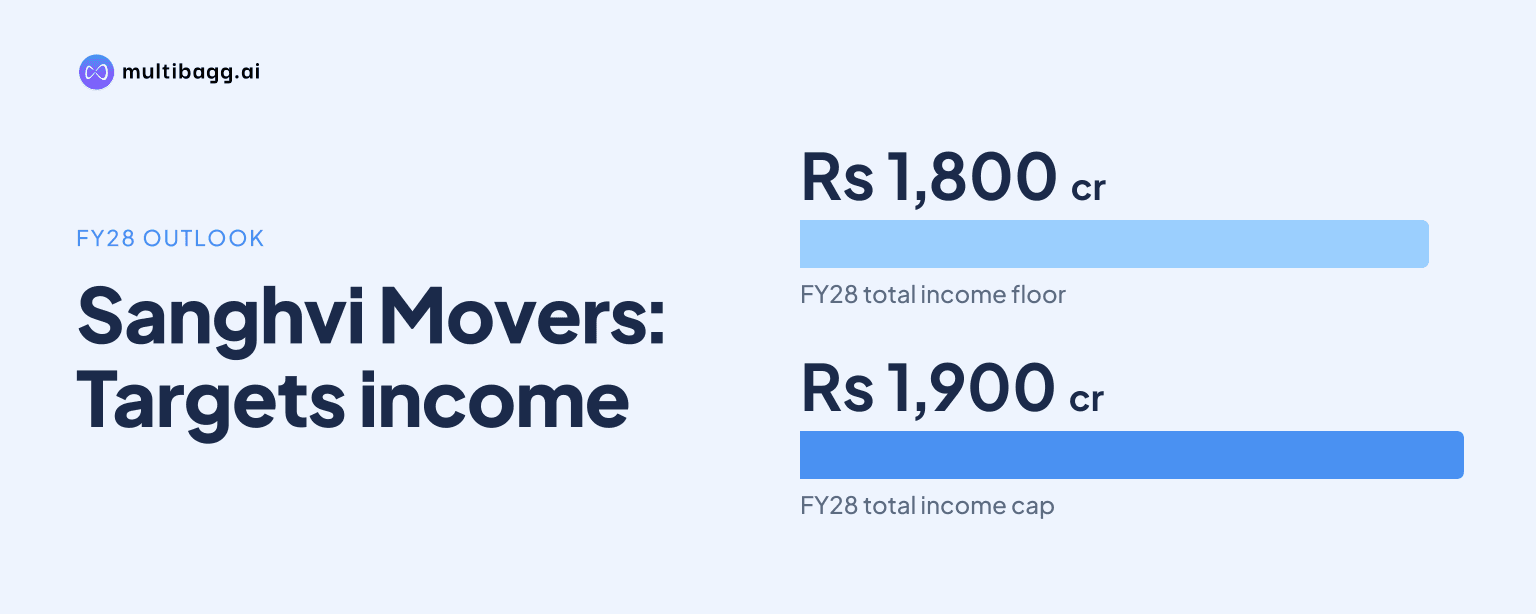
Sanghvi Movers Limited targets consolidated total income of Rs 1,800-1,900 crore and EBITDA of Rs 650-700 crore in FY28, after reporting Rs 689 crore of total income in H1 FY27, up 38% from Rs 498 crore a year earlier. SML’s FY28 segment mix target is 64% crane rental and 36% renewables engineering and construction.
Know Sanghvi Movers inside out
Results, valuation, peers and who's buying, in one view.
What are SML’s FY28 financial targets?
SML targets FY28 total income of Rs 1,800-1,900 crore, EBITDA of Rs 650-700 crore and blended return on capital employed, or ROCE, of 16.5-17.0%. These are consolidated targets under the ELEVATE 2030 roadmap and cover the group rather than only the India crane-rental operation.
The FY28 income range compares with actual total income of Rs 1,100 crore in FY26 and management’s FY27 projection of Rs 1,400-1,500 crore. The presentation gives a 25-35% compound annual growth rate, or CAGR, for FY28 income compared with FY26. It projects FY27 EBITDA of Rs 525-575 crore, after Rs 429 crore in FY26, before the FY28 target range.
H1 FY27 EBITDA was Rs 245 crore, 25% above Rs 195 crore in H1 FY26, alongside the 38% income increase. SML classified both H1 FY27 income and EBITDA performance as delivered against ELEVATE 2030 guidance. Blended ROCE was 16.25% on a trailing 12-month basis as of 30 September 2026, versus 18% on the same basis in H1 FY26.
How will SML’s revenue mix change by FY28?
SML targets a FY28 revenue mix of 64% crane rental and 36% renewables engineering and construction, or E&C. The target differs from FY26, when crane rental accounted for 65%, renewables E&C for 31%, and project engineering, procurement and construction, or EPC, for 4% of segment revenue.
Management revised the FY27 mix to 60% crane rental and 40% renewables E&C from an earlier 67:33 expectation. It attributed the change to higher renewables volumes, saying these would protect absolute EBITDA, while the asset-light mix would be ROCE accretive. The H1 FY27 mix was 61% crane rental, 36% renewables E&C and 2% project EPC, compared with 61%, 34% and 4%, respectively, in H1 FY26.
The plan therefore puts renewables at its highest share in FY27 before crane rental returns to 64% in FY28. The FY28 presentation specifies a two-business 64:36 mix and does not give a separate project EPC share, whereas FY26 and the two H1 periods report project EPC separately.
Which businesses support SML’s ELEVATE 2030 plan?
SML’s roadmap is based on its core crane-rental business, renewables platform Sangreen Logistics Private Limited, and international expansion through Sanghvi Movers Middle East Heavy Lift Limited. The group reported a FY26 footprint across India, KSA, Botswana and Qatar, while identifying new-country activation as a FY27 target.
For the core business, SML plans capital-efficient scale-up, customer focus and value-added products and services while seeking to maintain a healthy EBITDA margin. Its FY26 product progression was from cranes into spider cranes, and the FY27 target is an incremental product segment. SML also reported a 10% shift in India crane-rental revenue mix towards ancillary equipment.
For renewables, SML aims to provide a concept-to-commissioning offering and pursue wind E&C leadership, alongside higher-order work in wind, hybrid and other renewable-energy sectors. The roadmap identifies project-manager upskilling and subcontracting as scaling mechanisms for a high-ROCE business. This business is described as asset-light, complementing SML’s asset-heavy crane-rental model.
Got a follow-up? Ask IRIS
Why has SML re-phased KSA capital expenditure?
SML postponed KSA capital expenditure from FY27 to FY28 because shipping-route disruption and port congestion delayed deployment at Sanghvi Movers Middle East Heavy Lift Limited. Management said the delay also deferred Gulf Cooperation Council, or GCC, revenue that had been expected in FY27.
The company said it would prioritise the highest-return assets while monitoring the West Asia situation. Its KSA plan is to build a scalable, high-margin crane-rental platform through product-mix changes, depot expansion, and work on premium projects and clients. The presentation does not disclose KSA revenue or capex amounts for FY27 or FY28.
Management nevertheless reaffirmed total-income guidance because it expects a stronger renewables order book and execution to offset delayed GCC revenue. This mechanism also explains the FY27 rebalancing to a 60:40 crane-rental-to-renewables E&C mix, from the earlier 67:33 mix.
How does SML plan to manage returns and leverage?
SML targets blended ROCE of 16.25-16.5% in FY27 and 16.5-17.0% in FY28, with debt-to-equity ceilings of 0.72 times and 0.76-0.80 times, respectively. Actual debt-to-equity was 0.51 times in FY26 and 0.58 times in H1 FY27.
The planned capital-model shift is from asset-heavy operations to a hybrid model, with the asset-light renewables activity alongside the asset-heavy core business. By FY27, management says SML will pivot towards becoming a capital allocator. Its financial-growth pillar also calls for capital efficiency, profitability and risk control across business units.
SML reported a complete chief executive officer-level team, operational bots and ISO 27001 certification in FY26. Its FY27 technology plans include human-resources management software, Power BI, customer relationship management software and artificial-intelligence pilot implementation. These actions are roadmap items rather than separately quantified financial targets.
Conclusion
SML’s FY28 plan combines a consolidated income target of Rs 1,800-1,900 crore with EBITDA of Rs 650-700 crore and a 64:36 crane-rental-to-renewables E&C mix. The H1 FY27 results, including Rs 689 crore of income and Rs 245 crore of EBITDA, show growth against H1 FY26, while the revised FY27 mix assigns a larger role to renewables execution.
The next disclosed milestones are delivery of the FY27 income range of Rs 1,400-1,500 crore, execution of the renewables order book and re-phased KSA capex deployment in FY28. Management also identifies FY27 new-country activation, a capital-allocator pivot and technology implementation, while maintaining FY28 ROCE and debt-to-equity targets.