










Satia Industries posts Rs 27.5 crore Q2 FY27 loss as costs rise
Key highlights
- Satia Industries reported a Rs 27.5 crore net loss in Q2 FY27, versus a Rs 24.5 crore loss in Q2 FY26.
- Satia Industries' Q2 FY27 revenue fell 11% year on year to Rs 275.5 crore.
- Satia Industries recorded a Rs 6.1 crore operating loss in Q2 FY27, versus a Rs 6.6 crore operating profit a year earlier.
- Satia Industries' gross margin declined to 40.1% in Q2 FY27 from 50.9% in Q1 FY27.
powered by IRIS
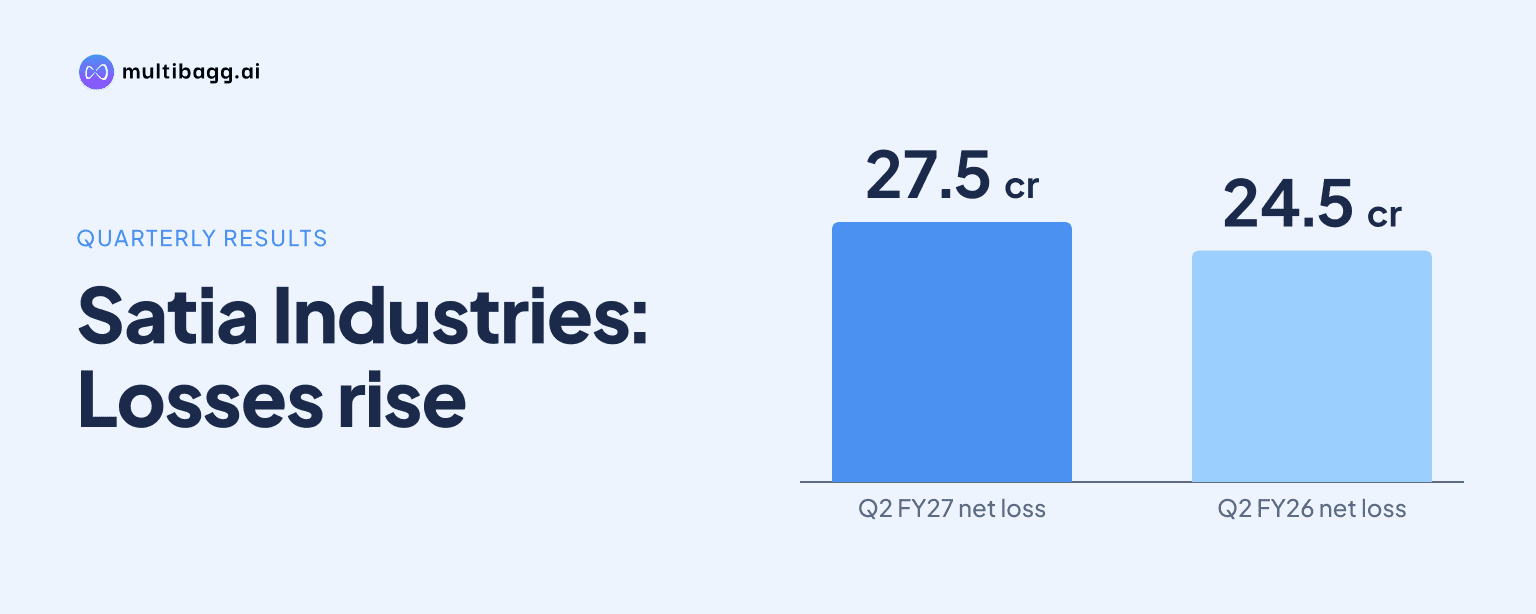
Satia Industries Limited posted a Rs 27.5 crore net loss in Q2 FY27 as revenue fell 11% to Rs 275.5 crore, with the planned PM3 shutdown reducing volumes and higher agro-based raw-material costs outweighing improved paper realisations. The loss widened from Rs 24.5 crore in Q2 FY26 and Rs 17.1 crore in Q1 FY27.
Know Satia Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did Satia Industries report a Q2 FY27 loss?
Satia Industries reported an operating loss of Rs 6.1 crore in Q2 FY27 because elevated input costs more than offset improved paper realisations, while the planned PM3 shutdown reduced volumes. The company had recorded an operating profit of Rs 6.6 crore in Q2 FY26 and Rs 50.8 crore in Q1 FY27, reversing profitability against both comparison periods.
The company identified agro-based raw materials, particularly wheat straw, as a key cost pressure in the quarter ended September 30, 2026. Gross margin declined to 40.1% in Q2 FY27 from 50.9% in Q1 FY27 and 44.9% in Q2 FY26, showing that the increase in input costs outweighed the benefit from higher year-on-year paper realisations.
The Q2 FY27 net loss widened by Rs 3 crore from Q2 FY26 and by Rs 10.4 crore from Q1 FY27. For H1 FY27, Satia Industries recorded a Rs 44.6 crore net loss, compared with a Rs 70 lakh profit in H1 FY26, while operating profit fell to Rs 44.7 crore from Rs 69.8 crore.
How did Satia Industries' revenue change in Q2 FY27?
Satia Industries' revenue from operations declined 11% year on year to Rs 275.5 crore in Q2 FY27 and fell 24% sequentially from Rs 361.8 crore in Q1 FY27. Revenue was Rs 311.1 crore in Q2 FY26, so the September-quarter total was Rs 35.6 crore lower despite the company reporting improved paper realisations.
The company attributed the volume impact to the planned shutdown of PM3 for renovation and modernisation. Management said demand remained steady during Q2 FY27 and import dumping had moderated, but the temporary production interruption limited the volume available to benefit from the improved pricing environment.
Revenue for H1 FY27 was Rs 637.3 crore, down 7% from Rs 682 crore in H1 FY26. The first-half decline was smaller than Q2 FY27's 11% fall because Q1 FY27 generated Rs 361.8 crore of revenue, although the PM3-related disruption in the September quarter pulled the six-month total below the prior-year level.
Got a follow-up? Ask IRIS
What did the PM3 renovation mean for Satia Industries?
The PM3 renovation reduced Q2 FY27 volumes because Satia Industries shut the machine for a planned modernisation project, completed towards the end of September 2026. Operations resumed after completion, but the timing affected production in the quarter in which revenue was Rs 275.5 crore.
Management said the upgraded machine is expected to enhance production capabilities, improve product quality and strengthen operating efficiencies. Those are management expectations rather than reported Q2 FY27 outcomes, as the disclosed result was an operating loss of Rs 6.1 crore after an operating profit of Rs 50.8 crore in Q1 FY27.
The company’s next stated task is to ramp up production and stabilise PM3 after commissioning. This focus follows a gross margin of 40.1% in Q2 FY27, which was 10.8 percentage points below Q1 FY27's 50.9%, alongside increased costs for wheat straw and other agro-based inputs.
What is Satia Industries expecting after Q2 FY27?
Management said demand had begun to pick up and paper prices had improved since the end of Q2 FY27, while the post-Diwali period typically has stronger seasonal demand. Satia Industries did not provide a revenue, margin or profit forecast, so its disclosed outlook consists of operational priorities rather than quantified guidance.
The company plans to progressively increase output, stabilise PM3, improve capacity utilisation and pursue operating efficiencies. Management also said it would maintain a disciplined approach to raw-material and other input costs after Q2 FY27's Rs 27.5 crore net loss and the gross-margin decline from 44.9% in Q2 FY26 to 40.1%.
Satia Industries said its moulded cutlery business remained steady in Q2 FY27, but did not disclose separate revenue or profit figures for that activity. Effective FY27, the company has opted for the concessional tax regime and no longer reports the Cogeneration Division as a separate segment, limiting direct segment comparison with earlier reporting.
Conclusion
Satia Industries' Q2 FY27 result shows that improved paper realisations did not offset a Rs 35.6 crore year-on-year revenue reduction, lower PM3 volumes and elevated agro-based raw-material costs. Together, these factors resulted in a Rs 6.1 crore operating loss and a Rs 27.5 crore net loss, compared with a Rs 6.6 crore operating profit and a Rs 24.5 crore net loss in Q2 FY26.
The next development to watch is PM3's production ramp-up following completion towards the end of September 2026, alongside management's plan to improve utilisation and control wheat-straw and other input costs. Management also cited improved paper prices and post-Diwali demand as factors affecting operations after Q2 FY27, without disclosing a numerical financial target.