










Scoda Tubes Limited Q2 Revenue Rises 2.5%, Keeps FY27 View
Key highlights
- Scoda Tubes reported Q2 FY27 revenue of Rs 148.9 crore, up 2.5% year-on-year.
- Q2 FY27 operating EBITDA margin declined 479 basis points year-on-year to 10.6%.
- H1 FY27 revenue reached Rs 273.3 crore, up 12.6%, while EBITDA was Rs 31.8 crore.
- Scoda Tubes reported an order book of about Rs 185 crore and retained FY27 revenue-growth guidance of 20% to 25%.
powered by IRIS
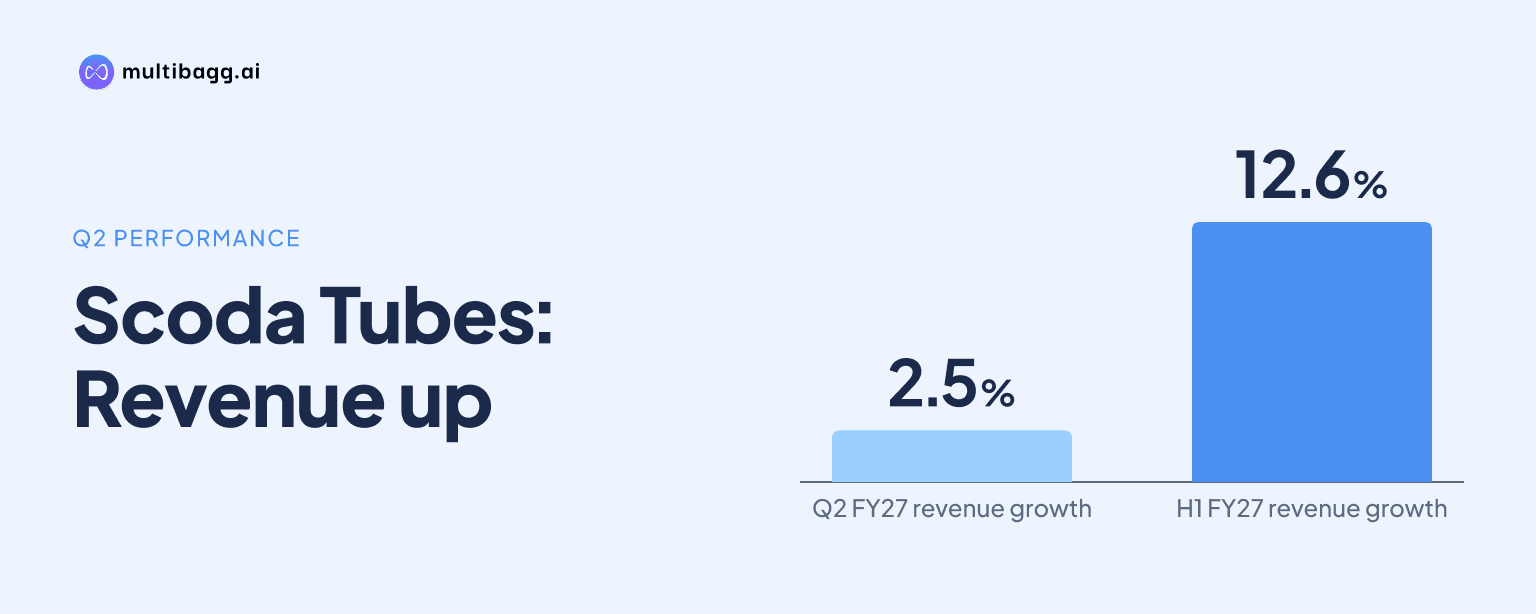
Scoda Tubes Limited reported Q2 FY27 revenue of Rs 148.9 crore, a 2.5% year-on-year increase, while its operating EBITDA margin fell 479 basis points to 10.6% amid higher power, fuel and freight costs. The company nevertheless reiterated its FY27 revenue-growth guidance of 20% to 25%.
Know Scoda Tubes inside out
Results, valuation, peers and who's buying, in one view.
What did Scoda Tubes report for Q2 FY27?
Scoda Tubes reported revenue from operations of Rs 148.9 crore for the quarter ended September 30, 2026, compared with Rs 145.3 crore in Q2 FY26. The increase was modest after a stronger first quarter, taking first-half revenue to Rs 273.3 crore, up 12.6% from Rs 242.7 crore a year earlier.
Quarterly EBITDA stood at Rs 15.8 crore, against Rs 22.3 crore in the corresponding quarter of FY26. Operating EBITDA margin declined to 10.6% from 15.38%, a contraction of 479 basis points. For H1 FY27, EBITDA was Rs 31.8 crore and the EBITDA margin was 11.6%.
The company reported H1 FY27 profit after tax of Rs 10 crore, representing a PAT margin of 3.7%. Reported Q2 PAT was Rs 4.8 crore, down 65.7% year-on-year, according to the results summary. The earnings performance shows that revenue growth during the period did not translate into comparable profit growth.
Why did Scoda Tubes' margin decline?
Scoda Tubes attributed the Q2 margin contraction primarily to higher power and fuel expenses and increased freight costs. Management commentary also referred to competitive conditions, which added pressure during a quarter when revenue increased only marginally.
The margin movement was more pronounced than the change in revenue. EBITDA declined by Rs 6.5 crore year-on-year even as revenue increased by Rs 3.6 crore. This resulted in the operating EBITDA margin falling below the 11.6% recorded for the first half.
No margin guidance was provided for FY27 in the earnings-call summary. That leaves cost trends, freight expenses and the pace of revenue conversion as important operating factors for investors assessing the second half of the year.
How did domestic sales and exports contribute to revenue?
Scoda Tubes generated 63% of Q2 revenue from domestic sales and 37% from exports. Domestic sales were Rs 93.8 crore, while export sales were Rs 55.1 crore, reflecting the company's presence in both Indian and overseas markets.
The earnings-call summary noted that exports were growing while domestic business was declining. Management also cited weak demand visibility in oil and gas, while referring to demand from the power sector and Bharat Heavy Electricals Limited. The available commentary did not quantify the revenue contribution from these end-markets.
The company reported an order book of about Rs 185 crore, with an estimated execution period of four to five months. Around 40% of this order book was linked to exports. This order visibility provides a near-term operating reference point, though management flagged uneven demand conditions in some sectors.
Got a follow-up? Ask IRIS
What is Scoda Tubes' capacity expansion plan?
Scoda Tubes incurred capital expenditure of about Rs 40 crore during H1 FY27. The spending was primarily directed towards machinery settlement for its welded facility and a solar power plant. Its net block of fixed assets stood at Rs 217.2 crore as of September 30, while capital work-in-progress was Rs 45.4 crore.
Management indicated that trial production at the welded facility is expected in Q4 FY27, with revenue-generating production expected from January. An additional 8,000-tonne line is expected in H1 FY28. The call summary also referred to 21,000 tonnes of capacity by H1 FY28.
The expansion is relevant because the company has linked its second-half outlook partly to welded capacity that had not yet been commissioned at the end of Q2. Execution of the commissioning schedule will therefore be important for assessing whether the additional capacity becomes available as indicated.
What does the FY27 guidance mean for investors?
Scoda Tubes reiterated its FY27 revenue-growth guidance of 20% to 25% despite Q2 revenue growth of 2.5% and H1 growth of 12.6%. Management maintained the growth outlook without providing a corresponding EBITDA-margin target.
The guidance puts focus on second-half execution, including order-book conversion, demand in key end-markets and the planned welded-facility ramp-up. The company had gross borrowings of Rs 229.2 crore as of September 30, 2026, while continuing to invest in new manufacturing assets and solar infrastructure.
For investors, the quarter presents two contrasting developments. Revenue and the order book support management's stated growth objective, but lower profitability highlights the effect of operating costs and competitive conditions. Further disclosures on production commissioning, costs and margin trends will help clarify how the company is progressing against its full-year plan.
Conclusion
Scoda Tubes delivered modest Q2 revenue growth and stronger H1 revenue growth, but its earnings were affected by a substantial reduction in operating margin. The company continues to target 20% to 25% revenue growth for FY27, supported by its order book, export business and planned capacity additions.
The next areas to watch are the Q4 FY27 trial production at the welded facility, the expected start of revenue-generating production from January, and the additional 8,000-tonne line targeted for H1 FY28. Updates on power, fuel and freight costs will also be relevant because management did not issue margin guidance for the full year.