










Shyam Metalics expects internal accruals to fund Rs 8,864 crore
Key highlights
- Shyam Metalics expects to deploy Rs 8,864 crore of remaining planned capex through internal accruals over the next two to three years.
- H1 FY27 operating cash flow was Rs 1,544 crore, compared with Rs 1,291 crore of capital expenditure.
- Net debt was Rs 192 crore and working capital was negative 16 days as of September 2026.
- Q2 FY27 operating EBITDA rose 52.6% year on year to Rs 823 crore, with a 13.8% margin.
powered by IRIS
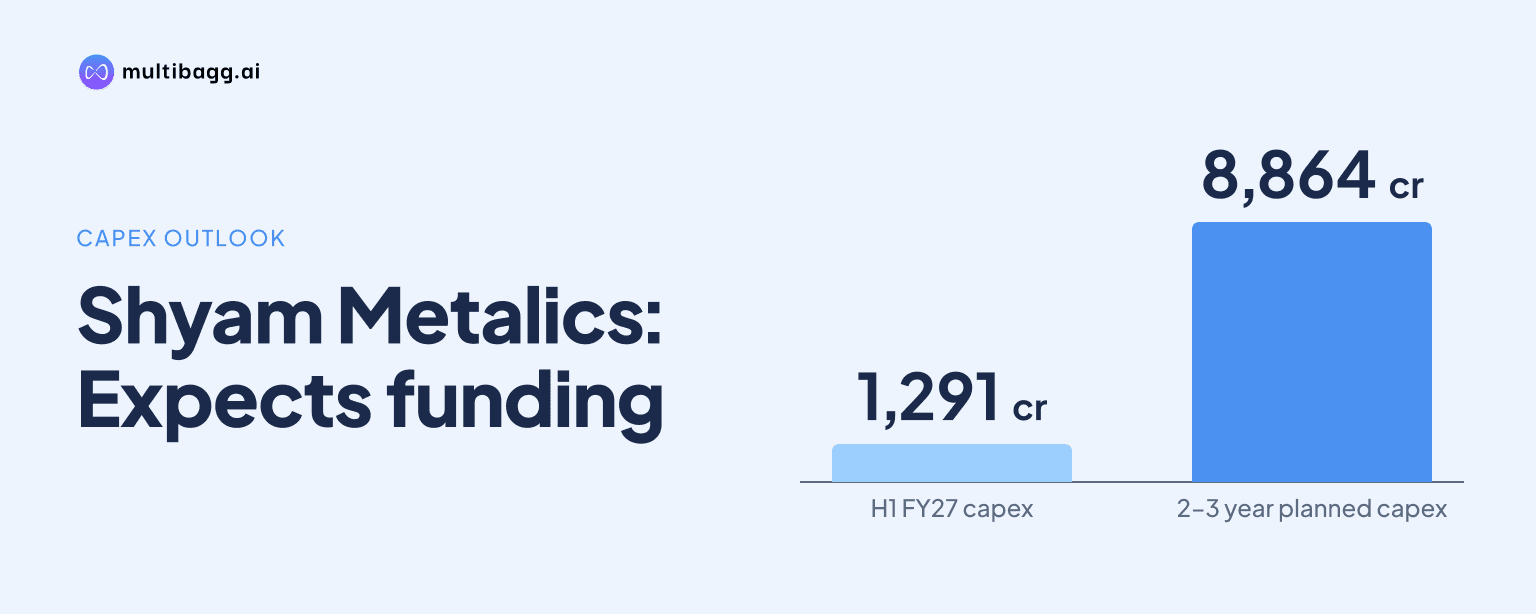
Shyam Metalics and Energy Limited expects to fund Rs 8,864 crore of remaining planned capital expenditure through internal accruals over the next two to three years, after generating Rs 1,544 crore of operating cash flow in H1 FY27 against Rs 1,291 crore of capex. Net debt was Rs 192 crore at September 2026.
Know Shyam Metalics & Energy inside out
Results, valuation, peers and who's buying, in one view.
Can Shyam Metalics fund its remaining capex internally?
Yes. Shyam Metalics said it expects the Rs 8,864 crore balance of its Rs 18,785 crore planned capital-expenditure programme to be funded through internal accruals over the next two to three years, in line with project-execution timelines.
The H1 FY27 cash-flow result provides the reported basis for that expectation. Operating cash flow of Rs 1,544 crore exceeded the Rs 1,291 crore spent on capital expenditure during the six months by Rs 253 crore. The company did not give a forecast for future annual operating cash flow or set out project-wise financing allocations.
Since listing, Shyam Metalics has incurred Rs 9,921 crore of capex, equivalent to about 53% of its total planned programme. Of this amount, Rs 6,671 crore had been capitalized by Q2 FY27, while management said about Rs 3,000 crore of capital work in progress, or CWIP, was yet to contribute earnings.
What financial measures support Shyam Metalics' plan?
Shyam Metalics reported negative working capital of 16 days and net debt of Rs 192 crore as of September 2026, which management said supports liquidity and flexibility for investment while retaining prudent leverage.
Quarterly earnings also rose as the expansion programme progressed. Q2 FY27 revenue was Rs 5,960 crore, up 33.4% year on year and 9.3% quarter on quarter, while reported earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 40.9% year on year to Rs 857 crore.
Operating EBITDA, excluding other income, increased 52.6% year on year to Rs 823 crore in Q2 FY27. Its margin rose 170 basis points to 13.8%, while H1 FY27 operating EBITDA increased 41.9% year on year to Rs 1,588 crore on revenue of Rs 11,415 crore.
Profit after tax reached Rs 511 crore in Q2 FY27, up 96.2% year on year and 45.7% quarter on quarter. Management said the quarter also benefited from lower depreciation after shifting its depreciation methodology from the written-down-value method to the straight-line method.
Which projects will Shyam Metalics fund with capex?
Shyam Metalics' stated programme includes a planned 1.6 million-tonne hot-rolled mill and a Rs 900 crore, 0.8 million-tonne specialty-bar and auto-steel project at Kharagpur, expanding its carbon-steel downstream capacity.
Its stainless-steel expansion at Odisha carries an investment of Rs 2,700 crore and includes downstream processing capability and a specialty-bar-quality, or SBQ, plant. Management targets commissioning both by March 2029 and expects the stainless-steel and SBQ businesses to contribute about Rs 1,100 crore and Rs 1,000 crore of EBITDA, respectively, by FY31.
In aluminium, Shyam Metalics commissioned an 18,000-tonnes-per-year foil facility at Sambalpur in July, taking total foil capacity to about 42,000 tonnes per year. The company's Rs 800 crore downstream aluminium programme also includes a planned 60,000-tonnes-per-year flat-rolled-products facility to increase in-house foil-stock availability.
Raw-material integration is another component of the programme. Shyam Metalics commissioned a 1.5 million-tonne beneficiation plant at Sambalpur with Rs 150 crore of investment, while its proposed 51% stake acquisition in Alom Solar Private Limited would involve an estimated share of about Rs 185 crore for the Phutamura coal-block project.
Got a follow-up? Ask IRIS
How are downstream businesses affecting Shyam Metalics' performance?
Shyam Metalics reported a 26% year-on-year increase in total sales volume to 15.49 lakh tonnes in Q2 FY27, while H1 FY27 volume reached 29.32 lakh tonnes, up 20% from the comparable prior-year period.
Carbon-steel flat-product sales more than doubled year on year to about 81,500 tonnes in Q2 FY27. Stainless-steel volume rose 20.7% to about 29,850 tonnes, and stainless-steel realization increased 35.2% year on year.
Other product lines showed different growth rates. Specialty-alloy volume grew 4.7% year on year, with realization up 18.4%, while aluminium volume increased 3% and aluminium realization rose 27.7%. Carbon-steel long-product volume grew modestly year on year but increased 6.8% sequentially.
Management said it does not expect a major change in the current revenue drivers in the next 12 months. The chairman said that, within two years, about 70% to 80% of business could come from value-added products, compared with about 20% from basic supplies, as planned plants consume internally produced inputs.
What returns does Shyam Metalics target from its investments?
Shyam Metalics reported return on equity, or RoE, of 14% and return on capital employed, or RoCE, of 20% as of September 2026. Management said these measures do not include the potential earnings from about Rs 3,000 crore of CWIP.
Management targets RoE of 16% and RoCE of 24% by 2031. It said higher utilization, greater downstream integration and disciplined capital allocation would be important as newly commissioned assets begin contributing to operations.
The July commissioning of the 18,000-tonnes-per-year foil facility and the 1.5 million-tonne beneficiation plant adds assets that require ramp-up. Management identified stabilization of newly commissioned facilities, profitability volumes and cash conversion as priorities for the coming quarter.
Conclusion
Shyam Metalics' internal-accrual funding plan is supported by H1 FY27 operating cash flow of Rs 1,544 crore covering Rs 1,291 crore of capex, alongside negative 16-day working capital and Rs 192 crore of net debt. The company is pairing that funding approach with investments in downstream steel, stainless steel, aluminium and raw-material integration.
The next measures to watch are deployment of the remaining Rs 8,864 crore over the stated two-to-three-year period, the March 2029 target for the Odisha stainless-steel and SBQ projects, and progress toward management's 2031 RoE target of 16% and RoCE target of 24%.