










Shyam Metalics targets Rs 2,100 crore FY31 EBITDA in stainless and SBQ
Key highlights
- Shyam Metalics targets Rs 1,100 crore of FY31 EBITDA from stainless steel and Rs 1,000 crore from SBQ.
- The Rs 2,700 crore Odisha stainless steel expansion, including SBQ, is targeted for commissioning by March 2029.
- Shyam Metalics reported Q2 FY27 EBITDA of Rs 857 crore and revenue of Rs 5,960 crore.
- Management expects the proposed Phutamura coal-block project to add close to Rs 400 crore of EBITDA by FY31.
powered by IRIS
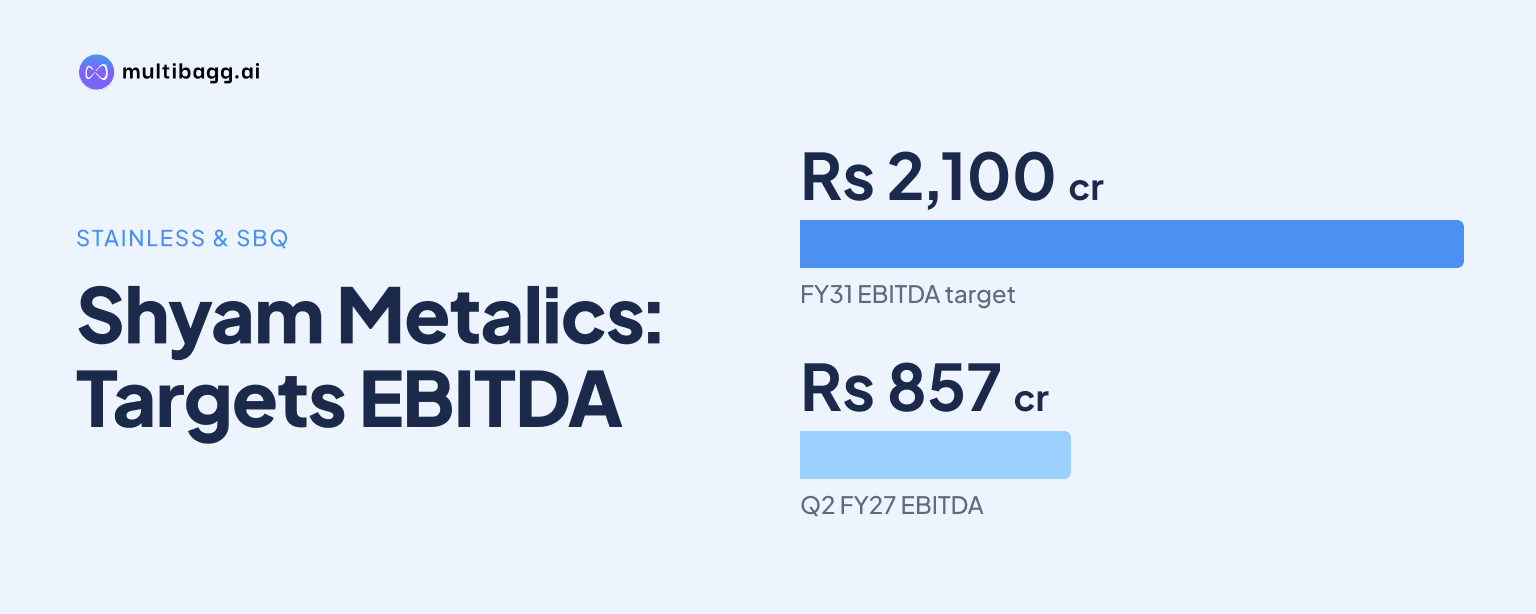
Shyam Metalics and Energy Limited targets approximately Rs 2,100 crore of earnings before interest, tax, depreciation and amortisation (EBITDA) from stainless steel and specialty bar quality (SBQ) businesses by FY31, supported by a Rs 2,700 crore Odisha expansion that management targets to commission by March 2029.
Know Shyam Metalics & Energy inside out
Results, valuation, peers and who's buying, in one view.
What is Shyam Metalics' FY31 EBITDA target?
Shyam Metalics expects its stainless steel business to contribute approximately Rs 1,100 crore of EBITDA and its SBQ business approximately Rs 1,000 crore by FY31, for a combined Rs 2,100 crore. Chairman and Managing Director Brij Bhushan Agarwal disclosed the target during the November 2, 2026 earnings call for Q2 FY27 and the half year ended September 30, 2026.
These are management expectations rather than reported earnings or formal annual guidance. Under its Vision 2031 plan, Shyam Metalics is seeking to raise the share of downstream and value-added products. In response to an analyst question, management said it expected value-added products to account for more than 75%, or about 70% to 80%, of business in the next two years, while basic supplies would account for about 20%.
The Rs 2,100 crore objective compares with group EBITDA of Rs 857 crore in Q2 FY27 and operating EBITDA, excluding other income, of Rs 823 crore. Q2 revenue was Rs 5,960 crore, up 33.4% year on year, while sales volume rose 26% to 15.49 lakh tonnes. The FY31 figure is therefore a targeted contribution from two businesses rather than a target for total Shyam Metalics EBITDA.
How will Shyam Metalics build its stainless steel and SBQ businesses?
Shyam Metalics is investing Rs 2,700 crore to expand its Odisha stainless steel plant with complete downstream processing capability, including the SBQ plant, with commissioning targeted by March 2029. Management described the project as an integrated stainless steel complex intended to capture more value from processing across the supply chain.
Management said backward integration could cover more than 75% to 80% of ingredients used in stainless steel production. The company aims to bring more production stages under its control to improve input availability and cost competitiveness. The call did not disclose separate capacity figures, a ramp-up schedule or an EBITDA bridge for the stainless steel and SBQ FY31 targets.
Shyam Metalics also has a planned 1.6 million-tonne hot-rolled (HR) mill and a Rs 900 crore, 0.8 million-tonne specialty bar combo mill for auto steel at Kharagpur. Management said new facilities would consume internally produced pig iron, sponge iron, specialty alloys and ferroalloys, converting materials currently sold in more basic forms into downstream products.
Q2 FY27 operating data showed growth in the newer downstream categories. Carbon-steel flat-product sales more than doubled year on year to approximately 81,500 tonnes, while stainless-steel volume increased 20.7% to approximately 29,850 tonnes. Stainless-steel realisation rose 35.2% year on year, while carbon-steel long-product volume grew modestly year on year and increased 6.8% quarter on quarter.
Got a follow-up? Ask IRIS
What raw-material projects support Shyam Metalics' expansion plan?
Shyam Metalics has proposed acquiring a 51% controlling stake in Alom Solar Private Limited, the successful bidder for the Phutamura coal block in Chhattisgarh. Management said the block has estimated reserves of 170 million tonnes and is expected to begin production in July 2027, supporting captive coal needs and reducing dependence on external sources.
The coal project is estimated to require Rs 360 crore of capital expenditure, of which Shyam Metalics' share would be close to Rs 185 crore. Management expects the initiative to generate incremental EBITDA of close to Rs 400 crore by FY31. This estimate is separate from the Rs 2,100 crore target for stainless steel and SBQ, and the call did not provide a combined FY31 EBITDA target for all expansion projects.
Shyam Metalics also commissioned a 1.5 million-tonne beneficiation plant at Sambalpur during the quarter after investing Rs 150 crore. Management said the facility upgrades lower-grade ore into higher-quality feedstock to improve resource utilisation and cost efficiency. It also commissioned a solar plant of close to 9 megawatts at Jamuria, which management said would increase renewable-energy use, lower power costs and reduce operating emissions.
How is Shyam Metalics financing the investment programme?
Shyam Metalics reported operating cash flow of Rs 1,544 crore in H1 FY27, covering capital expenditure of Rs 1,291 crore, and said it plans to fund the ongoing programme primarily through internal accruals. The company incurred Rs 716 crore of capital expenditure in Q2 FY27 and expects to deploy approximately Rs 8,864 crore of remaining planned capital expenditure over the next two to three years.
Since listing, Shyam Metalics has incurred Rs 9,921 crore of capital expenditure, representing approximately 53% of total planned capital expenditure of Rs 18,785 crore. Of this spending, Rs 6,671 crore had been capitalised. Approximately Rs 3,000 crore of capital work in progress (CWIP) was not yet contributing to operating earnings, and management said profitability and returns could rise as those assets are commissioned and ramp up.
As of September 2026, net debt stood at Rs 192 crore and working capital was negative 16 days. Return on equity (RoE) was 14% and return on capital employed (RoCE) was 20%. Management targets RoE of 16% and RoCE of 24% by 2031, citing higher utilisation, downstream integration and disciplined capital allocation as factors in meeting those targets.
Conclusion
Shyam Metalics has set a defined FY31 EBITDA ambition of Rs 1,100 crore from stainless steel and Rs 1,000 crore from SBQ. The plan depends on the Rs 2,700 crore Odisha expansion, greater internal conversion of metal inputs into downstream products, and projects intended to secure coal, ore and power inputs. Q2 FY27 results showed carbon-steel flat-product sales more than doubled, while stainless-steel volume and realisation also increased year on year.
The next disclosed milestones are expected July 2027 production from the Phutamura coal block, deployment of approximately Rs 8,864 crore of remaining planned capital expenditure over two to three years, and the March 2029 commissioning target for the Odisha expansion including SBQ. Management has not disclosed capacity, product-qualification or earnings-ramp details for the Odisha project, leaving execution progress against those milestones as the next matter to watch.