










Sigachi cuts FY27 revenue outlook to about Rs 600 crore
Key highlights
- Sigachi now expects about Rs 600 crore of FY27 revenue, compared with its earlier Rs 650 crore objective.
- Q2 FY27 operating income was Rs 130.45 crore and EBITDA was Rs 19.20 crore, producing a 14.72% margin.
- The 12,000-metric-tonne-per-annum Dahej MCC expansion is expected in Q2 FY28.
- Management said Rs 550 crore to Rs 575 crore of FY27 revenue is more easily achievable than about Rs 600 crore.
powered by IRIS
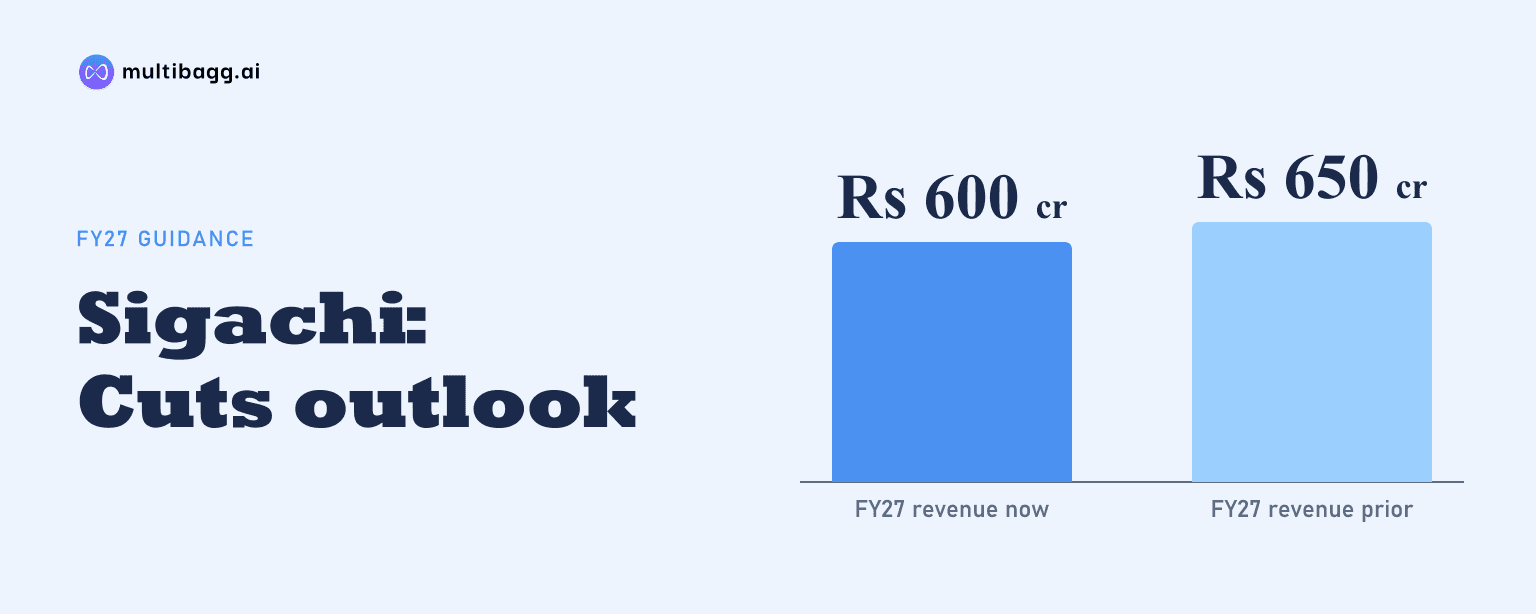
Sigachi Industries Limited expects about Rs 600 crore of revenue in financial year 2026-27 (FY27), down from its earlier Rs 650 crore objective, because its 12,000-metric-tonne-per-annum microcrystalline cellulose (MCC) expansion at Dahej is now expected in Q2 FY28. Management said Rs 550 crore to Rs 575 crore is more easily achievable.
Know Sigachi Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did Sigachi reduce its FY27 revenue outlook?
Sigachi reduced its FY27 revenue expectation because the new 12,000-metric-tonne-per-annum MCC project at Dahej Special Economic Zone (SEZ) will be commissioned in Q2 FY28 rather than contributing earlier to FY27. The company had included an earlier start-up of the project in its Rs 650 crore revenue objective, according to Chief Financial Officer O. Subbarami Reddy on the October 31, 2026 earnings call.
Management now expects revenue of “around Rs 600 crore or so” in FY27, while acknowledging that there would be a “little slip” from the previous target. In a later response, the CFO said Rs 550 crore to Rs 575 crore was more easily achievable, with revenue nearer Rs 600 crore depending on stretch business, fresh orders and a higher-value sales mix in the second half.
The revised outlook follows turnover of more than Rs 250 crore in the first half of FY27. Q2 FY27 operating income was Rs 130.45 crore, so the second half would need to exceed the first half materially for Sigachi to approach Rs 600 crore without output from the delayed Dahej expansion.
Can Sigachi reach about Rs 600 crore in FY27?
Sigachi said about Rs 600 crore remains possible if existing facilities raise utilisation, active pharmaceutical ingredient (API) sales deferred from Q2 move into Q3, and product mix improves in Q3 and Q4. Management described Rs 550 crore to Rs 575 crore as readily attainable and positioned the remaining revenue needed to approach Rs 600 crore as dependent on incremental business.
The company reported nearly 80% utilisation in the first half at its existing MCC facilities, comprising 79.91% at Dahej and about 79% at Jhagadia. Management expected utilisation to increase by another 10 percentage points after safety-equipment work, with an initial increase anticipated from November 15 to November 20, 2026.
MCC remained Sigachi's largest reported segment in Q2, generating Rs 91.22 crore, compared with Rs 16.67 crore from API and Rs 13.93 crore from O&M. Management also expects contributions from allied trade and its US subsidiary, but did not give separate FY27 revenue targets for those businesses.
What could improve Sigachi's second-half margins?
Sigachi expects second-half FY27 margins to improve through higher output from existing plants, no further increase in fixed overheads and a larger share of co-processed and special MCC grades. Q2 earnings before interest, tax, depreciation and amortisation (EBITDA) were Rs 19.20 crore, representing a 14.72% margin, while management referred to the current overall level as around 15%.
Management did not firmly reaffirm an 18% full-year EBITDA margin. Instead, it said second-half margins were expected to be at least 18%, and potentially above that level, so that the stronger second half could balance the first half. This is management's expectation, based on fixed-cost absorption and product mix, rather than a revised formal margin target.
The company said average realisation rose from 241.36 in Q1 FY27 to 262.83 in Q2 FY27, while the H1 FY27 average of 252.16 compared with 216.42 in the prior-year first half. Management attributed that change to sales mix and said co-processed products, currently about 20% of the mix, could rise by 50% over the existing level during Q3 and Q4.
Management said co-processed grades can have realisations three to four times those of normal grades, and that special products also have higher realisations and margins. The company did not disclose product-level volumes, prices or the precise revenue contribution expected from these grades in the remaining two quarters of FY27.
Got a follow-up? Ask IRIS
What are Sigachi's FY28 project and funding plans?
Sigachi expects the 12,000-metric-tonne-per-annum Dahej MCC expansion and its Dahej CCS facility to be commercialised in Q2 FY28, taking total MCC capacity to about 30,000 metric tonnes per annum. The CFO allowed for a possible one- or two-month variation to the project timing, meaning the expansion's main revenue contribution has moved beyond FY27.
Using 90% operation of the additional 12,000 metric tonnes, or 10,800 metric tonnes, and an assumed realisation of 225, the CFO illustrated potential revenue of Rs 243 crore from the expansion. He said the project could contribute more than Rs 200 crore of revenue after commissioning, alongside other businesses, but this was an illustration rather than formal FY28 guidance.
Existing output is also expected to increase before the new project starts. Sigachi reported production and sales of 7,128 metric tonnes in H1 FY27, after about 3,500 metric tonnes in Q1 and roughly 3,600 to 3,700 metric tonnes in Q2. Management expects quarterly output to reach 4,500 metric tonnes in Q4 following completion of safety measures.
Funding remains undecided after the proposed Rs 200 crore preferential issue was called off. Sigachi said it had spent about Rs 29 crore in total on the MCC and CCS projects and could use internal accruals, insurance proceeds, debt or equity for further capital expenditure. Management is also pursuing about Rs 49 crore of insurance receivables, subject to an indicated 5% to 10% discount, and hoped for receipt in November or December 2026.
Conclusion
Sigachi's revision from Rs 650 crore to about Rs 600 crore for FY27 reflects a timing change in its Dahej MCC expansion rather than a stated reduction in demand. The company is relying on higher utilisation at existing plants, deferred API dispatches and a greater proportion of co-processed and special MCC grades to make the second half larger and more profitable than the first.
The next indicators are completion of the remaining safety installation in November 2026, the conversion of API sales deferred from Q2 into Q3, and progress toward 4,500 metric tonnes of quarterly MCC output in Q4. Investors should also watch whether the Dahej MCC and CCS facilities meet the Q2 FY28 commissioning plan and how Sigachi chooses between debt, equity, internal accruals and insurance proceeds to fund expansion.