










Signature Global H1 sales drop 18% as Q2 realisation rises
Key highlights
- Signature Global reported H1 FY27 sales of Rs 3,800 crore, down from Rs 4,660 crore in H1 FY26.
- Signature Global sold 1.6 million sq ft in H1 FY27, compared with 3.0 million sq ft a year earlier.
- Signature Global’s Q2 FY27 average sales realisation was Rs 17,122 per sq ft, versus Rs 15,250 per sq ft in FY26.
- Group housing accounted for 94.5% of Signature Global’s H1 FY27 gross sales.
powered by IRIS
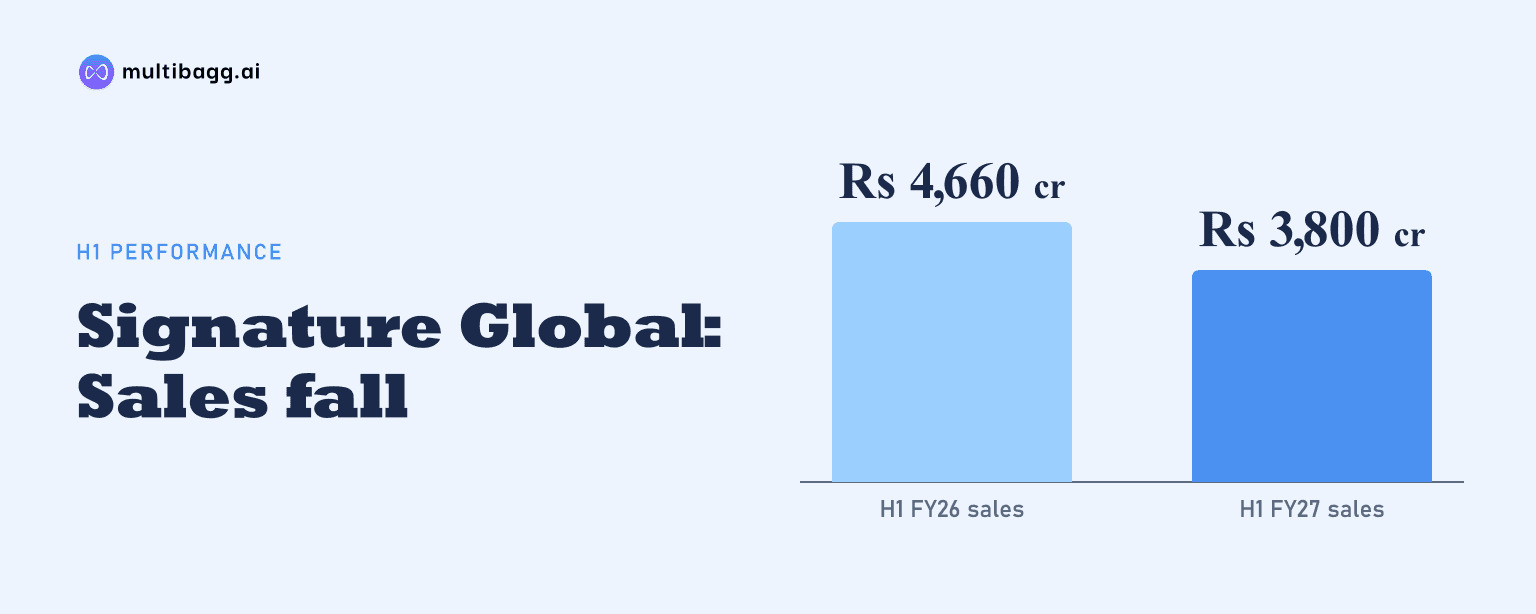
SIGNATUREGLOBAL (INDIA) LIMITED reported H1 FY27 sales of Rs 3,800 crore, 18% below H1 FY26, while Q2 FY27 average sales realisation rose to Rs 17,122 per sq ft. Signature Global sold 1.6 million sq ft in the half, down from 3.0 million sq ft a year earlier, indicating a higher-value sales mix alongside lower volume.
Know SignatureGlobal India inside out
Results, valuation, peers and who's buying, in one view.
Why did Signature Global H1 sales fall?
Signature Global’s H1 FY27 sales fell because reported sales declined to Rs 3,800 crore from Rs 4,660 crore in H1 FY26, while the area sold reduced more sharply to 1.6 million sq ft from 3.0 million sq ft. The presentation does not identify a specific reason for the lower sales value, such as demand, availability or launch timing.
The difference between the 18% sales-value decline and the 47% area decline is material to the sales mix. It shows that the value achieved from each unit of area sold was higher in H1 FY27, although the company does not disclose an H1 average realisation or a product-level bridge explaining the movement.
Quarterly sales also declined year on year, with Rs 1,830 crore in Q2 FY27 compared with Rs 2,020 crore in Q2 FY26. However, H1 FY27 sales represented 38% of management’s FY27 pre-sales estimate of Rs 10,000 crore, and the company said significant launches are planned in H2 FY27.
How much did Signature Global’s sales realisation increase?
Signature Global’s Q2 FY27 average sales realisation was about Rs 17,122 per sq ft, up Rs 1,872 per sq ft, or about 12%, from the Rs 15,250 per sq ft reported for FY26. The company described the measure as an upward shift in per-sq-ft realisation and said realisation is expected to stabilise in FY27.
The Q2 figure extends an increase reported over the preceding financial years, from Rs 11,762 per sq ft in FY24 to Rs 12,457 in FY25 and Rs 15,250 in FY26. Q2 FY27 is a quarterly measure while the earlier data are full-year figures, so the presentation establishes a latest quarterly level rather than a like-for-like annual comparison.
The higher realisation coincided with Signature Global’s entry into branded residences through Tonino Lamborghini Residences. The operating highlights page says the launch occurred in June 2026, while the project timeline lists May 2026; neither disclosure quantifies the project’s contribution to Q2 realisation.
What did Signature Global sell in H1 FY27?
Signature Global derived 94.5% of H1 FY27 gross sales from group housing, while plotted development contributed 3.5% and other products contributed 1.8%. Gurugram accounted for 96.5% of gross sales, compared with 2.4% for Sohna and 1.1% for Manesar.
The company sold more than 675 units in H1 FY27 at an average ticket size of Rs 5.59 crore. That disclosed ticket size is consistent with the direction of the higher Q2 realisation, but the presentation provides no H1 FY26 ticket size or project-wise pricing data to measure the year-on-year shift precisely.
The current mix also differs from the composition of the forthcoming portfolio. Of the 27.3 million sq ft of forthcoming projects, group housing accounts for 10.5 million sq ft, farmhouse villas for 6.8 million sq ft and other projects for 6.1 million sq ft; these saleable-area estimates are based on current zoning regulations.
Got a follow-up? Ask IRIS
Can Signature Global meet its FY27 pre-sales estimate?
Signature Global requires Rs 6,200 crore of sales in H2 FY27 to reach management’s FY27 pre-sales estimate of Rs 10,000 crore after recording Rs 3,800 crore in H1. Management said the balance of the annual launches is planned for H2 FY27 and that its Rs 15,000 crore FY27 launch estimate remains on track.
H1 FY27 launches were estimated at Rs 4,300 crore, compared with the full-year Rs 15,000 crore estimate. The presentation also says that the current focus is on sustaining last year’s sales levels, following FY26 actual pre-sales of Rs 8,200 crore, rather than presenting the FY27 estimate as a reported outcome.
Management’s pro forma FY27 guidance assumes embedded earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 3,500 crore on Rs 10,000 crore of pre-sales, implying a 35% embedded EBITDA margin. These are management estimates, while reported H1 FY27 revenue from operations was Rs 1,370 crore and reported profit after tax was Rs 50 crore.
How does Signature Global’s cash position support its pipeline?
Signature Global reported H1 FY27 collections of Rs 1,680 crore, down from Rs 1,860 crore in H1 FY26, but Q2 collections rose to Rs 1,010 crore from Rs 930 crore a year earlier. Operating cash surplus before land advance or acquisition increased 20% to Rs 480 crore from Rs 400 crore despite the lower H1 collections.
The company reported net debt of Rs 450 crore at September 30, 2026, compared with Rs 200 crore at March 31, 2026. Its H1 cash-flow presentation shows Rs 550 crore of land advances or acquisitions and Rs 170 crore of interest payments, contributing to a Rs 250 crore increase in net debt during the period.
Portfolio additions in H1 FY27 totalled about 9.95 million sq ft of estimated saleable area, led by 6.77 million sq ft in Farrukhnagar. The Farrukhnagar project covers 194 acres and has an estimated gross development value of Rs 5,500 crore to Rs 6,000 crore, while the company’s total portfolio across ongoing, recent-launch and forthcoming projects is about 59.7 million sq ft.
Conclusion
Signature Global’s H1 FY27 results show that sales volume contracted faster than sales value, while Q2 realisation reached Rs 17,122 per sq ft and group housing represented 94.5% of gross sales. The figures support a shift toward higher-value housing and a greater concentration in Gurugram, but they do not establish the cause of the lower area sold.
The next measure to watch is H2 FY27 execution: management plans the balance of its Rs 15,000 crore annual launch estimate in that period and needs Rs 6,200 crore of additional sales to meet its Rs 10,000 crore FY27 pre-sales estimate. Investors can also monitor whether realisation stabilises as management expects and whether the 27.3 million sq ft forthcoming pipeline launches over the disclosed two-to-three-year timeframe.