










Signature Global needs Rs 10,700 crore H2 launches for FY27
Key highlights
- Signature Global reported Rs 4,300 crore of launches in H1 FY27 against its Rs 15,000 crore FY27 estimate.
- Signature Global needs Rs 6,200 crore of H2 FY27 pre-sales to reach its Rs 10,000 crore annual estimate.
- Signature Global’s pro forma FY27 framework assumes Rs 3,500 crore of embedded EBITDA at a 35% margin.
- Signature Global added about 9.95 million square feet of estimated saleable area in H1 FY27.
powered by IRIS
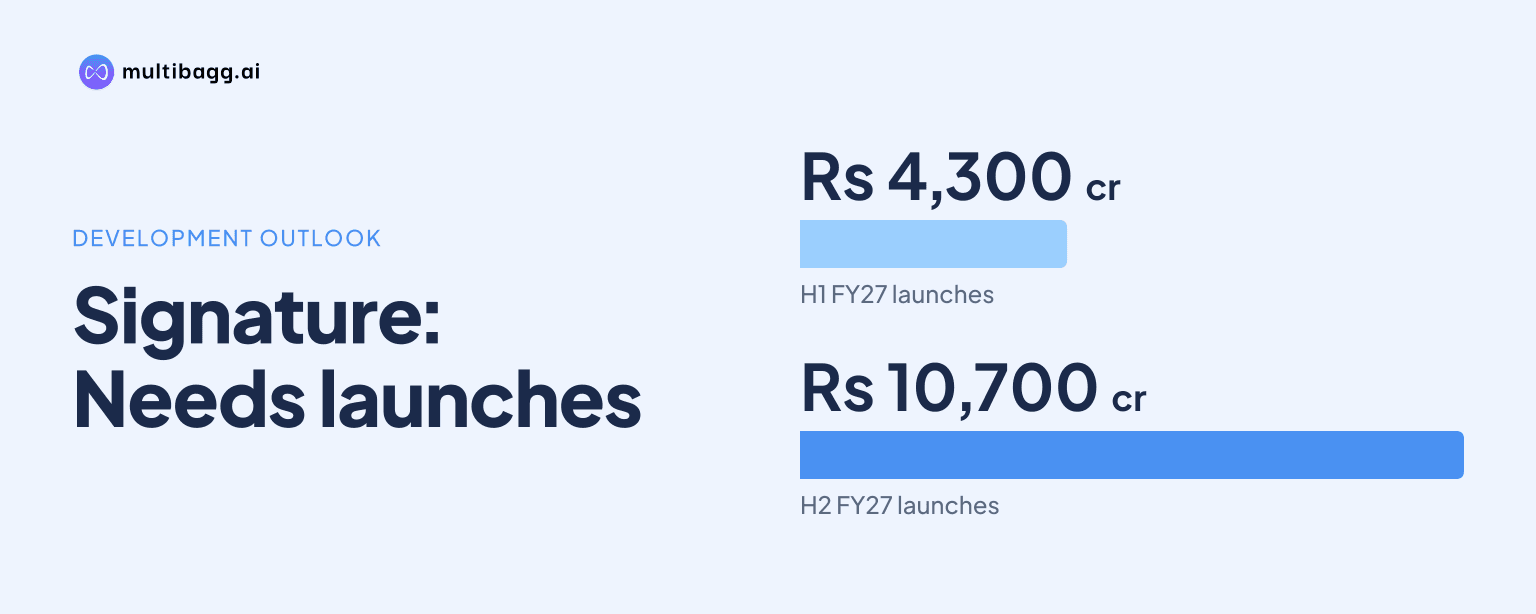
Signature Global needs Rs 10,700 crore of launch value and Rs 6,200 crore of pre-sales in H2 FY27 to meet its FY27 estimates of Rs 15,000 crore and Rs 10,000 crore, respectively, after reporting Rs 4,300 crore of launches and Rs 3,800 crore of pre-sales in H1 FY27. Management’s pro forma model assumes a 35% embedded EBITDA margin.
Know SignatureGlobal India inside out
Results, valuation, peers and who's buying, in one view.
What must Signature Global deliver in H2 FY27?
Signature Global must deliver Rs 10,700 crore of launches, Rs 6,200 crore of pre-sales, Rs 3,300 crore of collections and Rs 3,600 crore of revenue recognition in H2 FY27 to reach its stated full-year estimates. Its H1 FY27 launch value of Rs 4,300 crore represented about 29% of the Rs 15,000 crore FY27 estimate, while pre-sales of Rs 3,800 crore represented more than 38% of the Rs 10,000 crore estimate.
The remaining H2 FY27 launch requirement equals Signature Global’s entire FY26 actual launch value of Rs 10,700 crore. The Rs 6,200 crore remaining pre-sales requirement is lower than FY26 actual pre-sales of Rs 8,200 crore, but it accounts for most of the FY27 estimated sales activity. Management said the full-year launch guidance remains on track, with the balance planned for H2 FY27.
Launches are the estimated booking value of projects launched or proposed for launch, rather than revenue recognised during the same period. That distinction is reflected in Signature Global’s FY27 estimates: Rs 15,000 crore of launches, Rs 10,000 crore of pre-sales and Rs 5,000 crore of revenue recognition. The presentation labels FY26A as actual and FY27E as estimated.
Why does Signature Global expect most launches in H2 FY27?
Signature Global expects most launches in H2 FY27 because management has planned multiple project launches for the second half and has 27.3 million square feet of forthcoming projects scheduled for launch over the coming two years. Its stated saleable-area portfolio is about 60 million square feet, including 9.2 million square feet of ongoing projects and 23.2 million square feet of recent launches.
The company added about 9.95 million square feet of estimated saleable area in H1 FY27. Farrukhnagar contributed 6.77 million square feet, Sohna 2.70 million square feet, SG Sarvam in Sector 37D 0.38 million square feet, and Sector 71 on the Southern Peripheral Road region 0.10 million square feet. These are potential saleable-area estimates based on current zoning regulations.
Farrukhnagar was the largest H1 FY27 portfolio addition, covering 194 acres and carrying estimated development potential of 6.77 million square feet. Signature Global placed its estimated gross development value at Rs 5,500 crore to Rs 6,000 crore and described the planned product as large-format farmhouse plots. The project’s stated connectivity includes the KMP Expressway at about one minute and NH-48 at about 15 minutes.
Signature Global’s four focus areas show the concentration of its stated future development potential. Sector 71 has 17.8 million square feet of stated potential, followed by the Sohna Elevated Corridor at 10.2 million square feet, Sector 37D at 9.5 million square feet and Farrukhnagar at 6.77 million square feet. Management’s area estimates do not represent bookings or recognised revenue.
How does the H2 FY27 plan compare with recent sales?
Signature Global’s H1 FY27 pre-sales of Rs 3,800 crore were lower than Rs 4,660 crore in H1 FY26, while Q2 FY27 pre-sales of Rs 1,830 crore were lower than Rs 2,020 crore in Q2 FY26. The comparison means the H2 FY27 launch schedule must convert into a larger level of bookings than the first half to achieve the Rs 10,000 crore full-year estimate.
Sales realisation moved in the other direction, reaching about Rs 17,122 per square foot in Q2 FY27, compared with about Rs 15,250 per square foot in FY26. The FY26 figure followed Rs 12,457 per square foot in FY25 and Rs 11,762 per square foot in FY24. Signature Global sold more than 675 units at an average ticket size of Rs 5.59 crore during H1 FY27.
The June 2026 launch of TONINO LAMBORGHINI RESIDENCES marked Signature Global’s entry into branded residences. The presentation does not state the project’s booking contribution, so it does not establish how much of the Rs 3,800 crore H1 FY27 pre-sales came from that launch. Management said its current focus was sustaining last-year sales levels while launches remain on track.
Got a follow-up? Ask IRIS
What does Signature Global’s FY27 margin framework assume?
Signature Global’s pro forma FY27 framework assumes embedded earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 3,500 crore, equal to 35% of estimated pre-sales of Rs 10,000 crore. The H1 FY27 pro forma also shows a 35% embedded EBITDA margin, with Rs 1,330 crore of embedded EBITDA on Rs 3,800 crore of pre-sales.
Management’s FY27 model deducts Rs 30 crore of depreciation and amortisation and Rs 170 crore of finance cost from embedded EBITDA to reach Rs 3,300 crore of embedded profit before tax. It then applies an assumed tax rate of 25.2%, producing Rs 2,470 crore of embedded profit after tax. Finance cost is defined in the presentation as interest payments expected to be incurred in FY27.
The presentation labels the measures pro forma and embedded, rather than statutory reported profit. The H1 FY27 framework includes Rs 20 crore of depreciation and amortisation, Rs 60 crore of finance cost and Rs 310 crore of assumed tax. The 35% margin is therefore management’s guidance assumption and depends on delivery of the FY27 pre-sales estimate.
Which operating measures will show H2 FY27 execution?
Signature Global’s operating cash surplus rose 20% year on year to Rs 480 crore in H1 FY27 from Rs 400 crore in H1 FY26, even as collections declined to Rs 1,680 crore from Rs 1,860 crore. The company defines operating cash surplus as collections after construction, selling, general and administrative expenses and taxes, before land advances or acquisitions.
Collections improved in Q2 FY27 to Rs 1,010 crore from Rs 930 crore in Q2 FY26, although H1 collections remained below the prior-year period. The Rs 5,000 crore FY27 collections estimate leaves Rs 3,300 crore for H2 FY27. Management said collections improved significantly in Q2 FY27 compared with Q1 FY27 and expects launch-led operating cash flow growth in H2.
Net debt was Rs 450 crore as of September 30, 2026, and CARE reaffirmed an A+ stable rating on gross debt, including non-convertible debentures. Signature Global had delivered housing projects totaling about 19.9 million square feet and reported that 4.1 million square feet of its 9.2 million-square-foot ongoing portfolio had partial occupancy certificates. The remaining ongoing area for completion was stated as 5.1 million square feet.
Conclusion
Signature Global’s FY27 estimates depend on a launch-heavy second half, with Rs 10,700 crore of launch value, Rs 6,200 crore of pre-sales and Rs 3,300 crore of collections still required after H1 FY27. The company’s 27.3 million-square-foot forthcoming project base and H1 addition of 9.95 million square feet provide the stated portfolio basis for that plan, while the 35% embedded EBITDA margin remains a management assumption tied to pre-sales delivery.
The next disclosures to watch are the multiple H2 FY27 project launches that management has planned, their conversion into bookings, and progress toward the Rs 5,000 crore revenue-recognition and collections estimates. Management has also said the majority of yearly launches are expected in H2 FY27, with consequent growth in operating cash flow expected during that period.