










Sonata Software Limited says Q2 costs cut margin 150 basis points
Key highlights
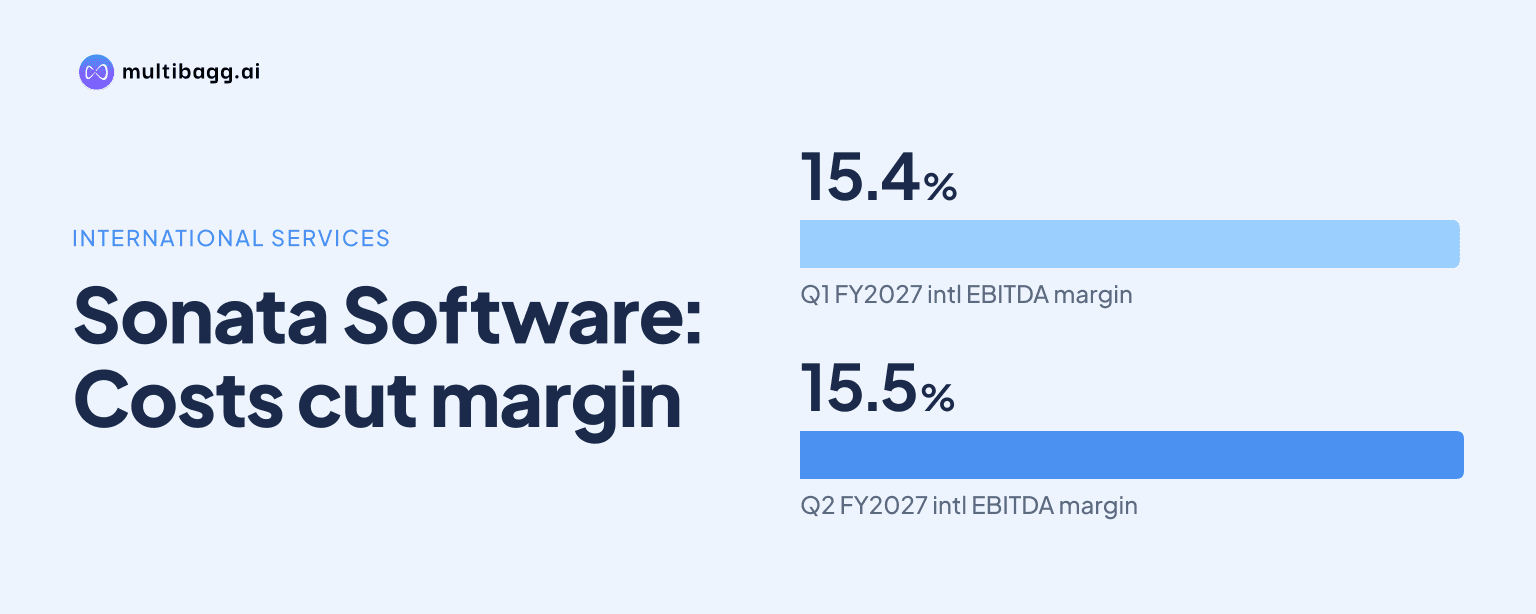
- Sonata’s Q2 FY2027 international-services EBITDA margin was 15.5%, up 10 basis points from 15.4% in Q1 FY2027.
- Severance costs accounted for about 50 basis points of Q2 FY2027 margin, while proof-of-concept investment accounted for about 100 basis points.
- International-services revenue reached Rs 797.9 crore in Q2 FY2027, up 2.7% quarter on quarter.
- International-services utilisation rose to 90.5% in Q2 FY2027 from 88.5% in Q1 FY2027.
powered by IRIS
Sonata Software Limited said its international-services earnings before interest, tax, depreciation and amortisation (EBITDA) margin for Q2 FY2027 was 15.5%, after about 150 basis points, or 1.5 percentage points, of severance and AI proof-of-concept spending in the quarter ended September 30, 2026.
Know Sonata Software inside out
Results, valuation, peers and who's buying, in one view.
What cost Sonata 150 basis points of Q2 margin?
The 150 basis points consisted of about 50 basis points of severance costs and about 100 basis points of proof-of-concept investment during Q2 FY2027. EBITDA is the profitability measure management used for the international-services business before other income and foreign-exchange effects.
The severance expense arose after a ramp-down in a large account across a couple of geographies. Management described the severance item as one-time, while the proof-of-concept spending funded demonstrations of Sonata’s AI-led offerings for selected customers and could support pipeline and order-book conversion in coming quarters.
Management did not quantify the benefit from each offsetting operating action. It cited higher utilisation, an improved employee pyramid, fixed-price optimisation and selling, general and administrative savings, but also said salary increments for lower-management staff affected the quarter; that group accounts for about 60% of Sonata’s people.
How did Sonata’s international-services margin change in Q2?
Sonata’s international-services EBITDA margin increased by 10 basis points sequentially to 15.5% in Q2 FY2027 from 15.4% in Q1 FY2027, despite the 150 basis points of identified spending. International-services revenue was Rs 797.9 crore, up 2.7% quarter on quarter and 9.3% year on year.
The operational metric management quantified was utilisation, which rose to 90.5% from 88.5% in Q1 FY2027 after completion of a large-deal ramp-up. International-services revenue grew 1.0% quarter on quarter and about 0.9% year on year in US-dollar terms, while constant-currency growth was 1.2% sequentially and 1.3% year on year.
Profit after tax for international services rose 11.1% sequentially to Rs 69.1 crore from Rs 62.2 crore. Days sales outstanding, a measure of receivables collection time, fell to 52 days from 60 days, although management said the lower figure reflected advance collections and that it expects to maintain the measure around 60 days in coming quarters.
Will Sonata’s proof-of-concept spending continue after Q2?
Sonata said some proof-of-concept spending may continue in Q3 FY2027, but management did not provide a forecast for its size. The company said such investment is not planned as a fixed quarterly amount because it depends on customer requirements, the opportunity involved and the potential deal size.
Management characterised the Q2 spending as important but not substantial, and said it had been made for a few existing customers. Its rationale was to demonstrate value from three priority offerings within its AI-led go-to-market approach, with the intention that work reflected in pipeline and order book could contribute to revenue in the next couple of quarters.
The wider investment programme includes talent transformation and advisory solutions under Sonata’s plan to engineer AI enterprises. Management said its Harmoni.ai portfolio includes an enterprise workbench, a migration studio for legacy modernisation, AgentBridge for process transformation, AI-ready data and a resilient AI backbone, but it did not attach revenue or margin figures to those individual offerings.
Got a follow-up? Ask IRIS
What margin outlook did Sonata give for international services?
Sonata reiterated an aspiration to operate international-services EBITDA margins between 18% and 20%, and management said it expects margins to improve from the 15.5% Q2 FY2027 level. It did not give a date for reaching that range or quantify the expected improvement in Q3 FY2027.
Management’s stated basis for improvement was that Q2 included the salary increase, severance and proof-of-concept costs while still delivering a 10-basis-point sequential margin increase. It said revenue growth and margins should show positive momentum in coming quarters, but added that the extent and timing of future proof-of-concept investment cannot be extrapolated from Q2.
International-services order book was Rs 9.85 crore in Q2 FY2027, with a book-to-bill ratio of 1.18 times. AI-led work accounted for Rs 2.42 crore, or approximately 25%, of that order book, while the AI-led pipeline stood at Rs 35.8 crore; these measures represent potential work rather than realised revenue.
A large-account renewal and ramp-down remain relevant to the outlook. Management said the Q2 decline was linked to a programme ramp-down after renewals, but described that event as behind it and said it saw positive traction from the next quarter. It also identified isolated Q3 FY2027 headwinds in banking, financial services and insurance, and technology, media and telecom.
How could client trends affect Sonata’s margin recovery?
Sonata said its top 10 clients supplied 51% of international-services revenue in Q2 FY2027, while four new customers were added during the quarter. Management expects the top 10 contribution to rise, although it flagged isolated headwinds in one or two accounts during Q3 FY2027.
Management said a potential ramp-down in a technology, media and telecom account could affect the next quarter, but that the account’s order-book value had increased and revenue would be spread over a longer period. It said the longer-term view, over eight to 10 quarters, was positive for total business volume in that account.
The company also said mid-sized accounts were scaling faster under its prove-and-scale model, in which AI-led offerings are demonstrated before broader deployment. Management cited healthcare and life sciences as consistently growing, described banking, financial services and insurance as showing improvement after an earlier account run-down, and said research and development was under pressure.
Conclusion
Sonata reported a small sequential increase in international-services EBITDA margin to 15.5% even after 150 basis points of severance and AI proof-of-concept costs. The 50-basis-point severance item was tied to a large-account ramp-down, while the 100-basis-point customer investment was intended to support the company’s AI-led sales effort and potential future conversion.
The next result will show whether utilisation above 90.5%, operational efficiencies and 1.0% sequential US-dollar revenue growth support further margin movement. Investors will also watch management’s disclosure on continuing proof-of-concept spending, conversion of the Rs 35.8 crore AI-led pipeline, and the isolated Q3 FY2027 headwinds it identified in banking, financial services and insurance and technology, media and telecom.