










Sonata Software margin reached 7.3% as revenue fell 25.4%
Key highlights
- Sonata Software’s consolidated EBITDA margin before foreign-exchange effects and other income rose to 7.3% in Q2'27 from 5.5% in Q1'27.
- Sonata Software’s consolidated revenue fell 25.4% sequentially to Rs 2,445.2 crore in Q2'27.
- Sonata Software’s consolidated PAT increased 7.7% quarter on quarter to Rs 116.4 crore.
- Sonata Software declared a 125% interim dividend in its Q2'27 presentation.
powered by IRIS
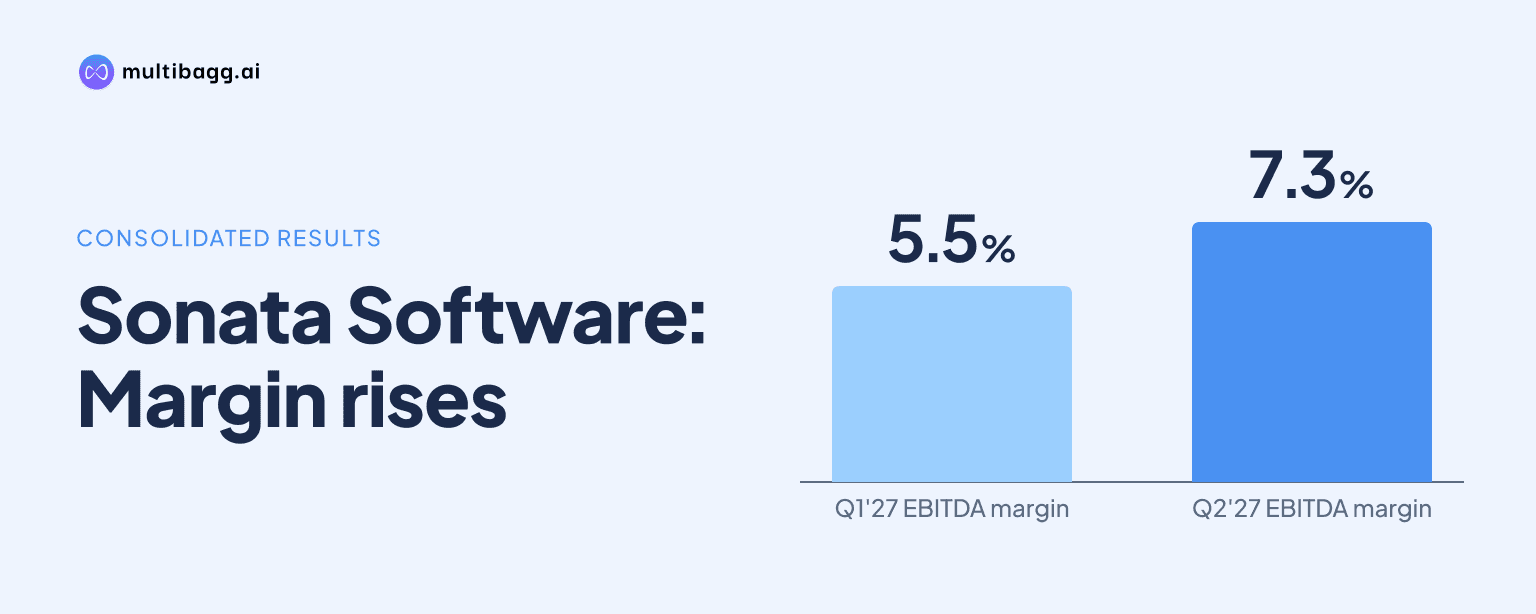
Sonata Software Ltd. lifted its consolidated earnings before interest, tax, depreciation and amortisation (EBITDA) margin to 7.3% in Q2'27 from 5.5% in Q1'27, although revenue fell 25.4% sequentially to Rs 2,445.2 crore. Profit after tax (PAT) rose 7.7% to Rs 116.4 crore, and Sonata Software declared a 125% interim dividend.
Know Sonata Software inside out
Results, valuation, peers and who's buying, in one view.
What changed in Sonata Software’s consolidated Q2'27 earnings?
Sonata Software’s consolidated revenue declined by Rs 833.9 crore from Rs 3,279.1 crore in Q1'27 to Rs 2,445.2 crore in Q2'27, a 25.4% sequential reduction calculated from the reported figures. EBITDA before foreign-exchange effects and other income was broadly unchanged at Rs 179.5 crore, compared with Rs 179.0 crore in Q1'27, despite the lower revenue base.
The reported EBITDA margin before foreign-exchange effects and other income rose by 1.8 percentage points to 7.3% from 5.5%. EBITDA after foreign-exchange effects and other income increased 13.7% sequentially to Rs 201.8 crore from Rs 177.5 crore, while its margin rose to 8.2% from 5.4%.
PAT increased to Rs 116.4 crore in Q2'27 from Rs 108.1 crore in Q1'27, lifting the consolidated PAT margin to 4.7% from 3.3%. The effective tax rate was 26.0% in Q2'27, compared with 21.1% in Q1'27, while Sonata Software’s presentation also disclosed the 125% interim dividend.
Which segments drove Sonata Software’s quarterly revenue change?
Sonata Software’s disclosed segment results show that International Services grew while Domestic Business recorded a steep revenue decline. International Services revenue increased 2.7% quarter on quarter to Rs 797.9 crore in Q2'27 from Rs 777.2 crore, and the presentation reported 9.3% year-on-year growth in rupee terms.
Domestic Business revenue fell 33.9% sequentially to Rs 1,655.6 crore in Q2'27 from Rs 2,505.6 crore in Q1'27. The presentation reported 19.0% year-on-year revenue growth for the segment in Q2'27, compared with 10.1% in Q1'27, showing that the sequential decline occurred against a higher year-earlier revenue base.
International Services EBITDA before foreign-exchange effects and other income increased 3.4% to Rs 123.7 crore from Rs 119.6 crore, with its margin moving to 15.5% from 15.4%. Domestic Business EBITDA on the same basis declined 6.0% to Rs 55.8 crore from Rs 59.3 crore, but its margin rose to 3.4% from 2.4%.
The segment figures support the reported consolidated margin expansion, but the presentation does not specify individual cost actions or transaction-level factors behind it. Domestic Business products gross contribution, labelled GC in the presentation, rose 4.5% sequentially to Rs 82.0 crore from Rs 78.5 crore, even as segment revenue declined 33.9%.
Got a follow-up? Ask IRIS
How did Sonata Software’s International Services business perform?
Sonata Software’s International Services revenue was $82.8 million in Q2'27, up 1.0% quarter on quarter in reported currency from $82.0 million. On a constant-currency basis, the presentation reported 1.2% sequential growth and 1.3% year-on-year growth, while the book-to-bill ratio remained 1.18 times for Q2'26, Q1'27 and Q2'27.
International Services PAT rose 11.1% sequentially to Rs 69.1 crore from Rs 62.2 crore, although it was below Rs 78.0 crore in Q2'26. PAT margin improved to 8.6% from 8.0% in Q1'27 but remained below the 10.7% recorded in Q2'26.
EBITDA before foreign-exchange effects and other income was Rs 123.7 crore, higher than Rs 119.6 crore in Q1'27 but lower than Rs 126.3 crore in Q2'26. The related margin was 15.5%, compared with 15.4% sequentially and 17.3% a year earlier, indicating a modest quarter-on-quarter gain but a lower year-on-year level.
Return on capital employed rose to 19.2% in Q2'27 from 14.9% in Q1'27, while return on net worth increased to 17.7% from 15.2%. Days sales outstanding, which measures the number of days taken to collect receivables, fell to 52 days from 60 days sequentially and 68 days in Q2'26.
What operating indicators should readers track after Q2'27?
Sonata Software’s International Services utilisation rose to 90.5% in Q2'27 from 88.5% in Q1'27 and 87.3% in Q2'26. Total segment headcount declined to 5,680 from 5,795 sequentially and 6,136 a year earlier, with delivery headcount falling to 5,299 from 5,409 in Q1'27.
Attrition in International Services declined to 10.0% in Q2'27 from 13.0% in Q1'27 and 14.0% in Q2'26. Sonata Software reported total headcount of 6,214 in Q2'27 when Domestic Business employees were included, compared with the 5,680 employees reported for International Services alone.
Client concentration changed across the reported periods. The top 10 customers accounted for 51% of International Services revenue in Q2'27, unchanged from Q1'27 and below 53% in Q2'26, while the top 20 share fell to 66% from 70% in both earlier comparison quarters.
Sonata Software added four International Services customers in Q2'27, compared with seven in Q1'27 and six in Q2'26. The United States accounted for 74% of segment revenue, up from 71% sequentially, while Europe represented 19%, down from 23%, and the rest of the world accounted for 7%, compared with 6% in Q1'27.
Conclusion
Sonata Software’s Q2'27 results showed a divergence between revenue and profitability: consolidated revenue fell 25.4% sequentially, while EBITDA before foreign-exchange effects and other income remained near Rs 180 crore and the margin reached 7.3%. International Services delivered revenue growth and a 15.5% EBITDA margin, whereas Domestic Business reported a 33.9% revenue decline but a 1.0-percentage-point margin increase.
The next reported quarter will show whether International Services can extend growth from Rs 797.9 crore while maintaining its 1.18-times book-to-bill ratio, 90.5% utilisation and 52-day receivables cycle. Readers can also track whether Domestic Business revenue changes from Rs 1,655.6 crore after its Q2'27 decline, alongside the effect of the declared 125% interim dividend.