










SPR Auto says new mature-year wins exceed Rs 1,000 crore
Key highlights
- SPR Auto said mature-year incremental business wins exceed Rs 1,000 crore, beyond around Rs 6,000 crore of regular business.
- SPR Auto said it is considering another three or four capex decisions that could change its investment plan.
- Speakerless acoustic headliners could lift realisation by 15% to 18% in small cars and around 30% to 40% in larger vehicles, according to management.
- SPR Auto said first-half standalone growth was 17%, while it expects growth to moderate toward a 7% to 8% CAGR over the next two years.
powered by IRIS
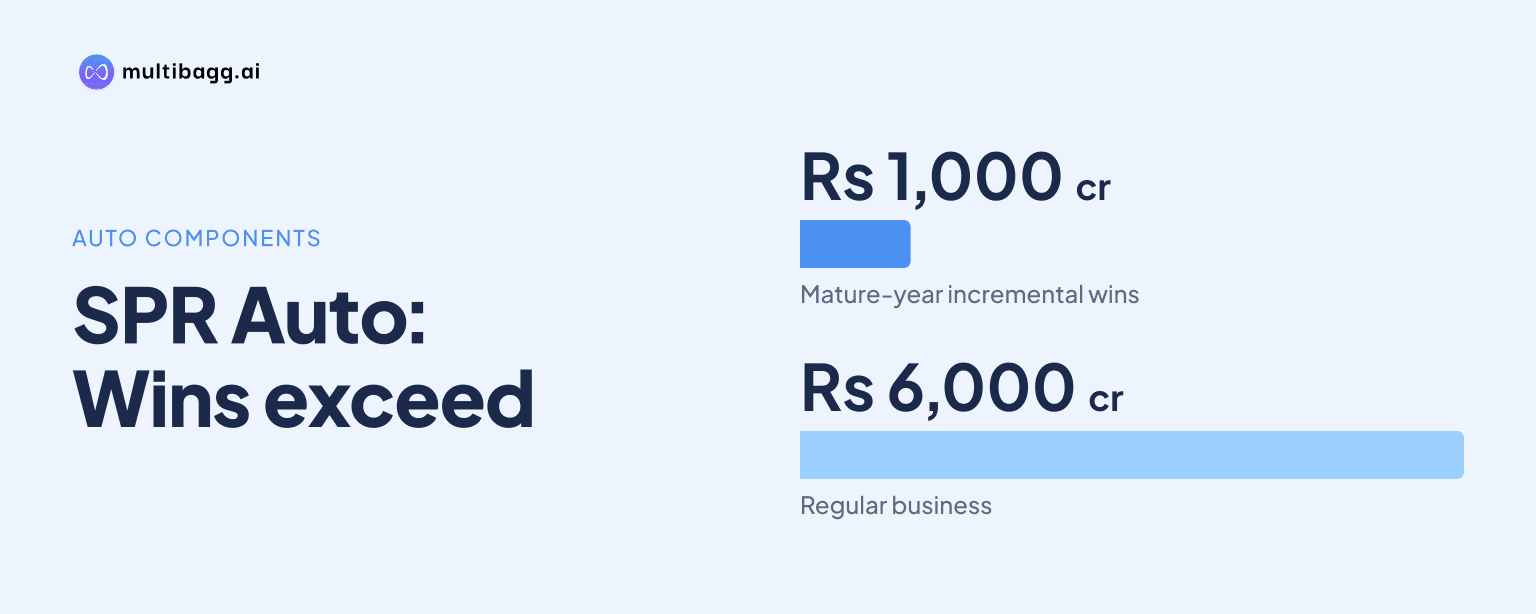
SPR Auto said new business wins across its operations should exceed Rs 1,000 crore in a mature year, in addition to around Rs 6,000 crore of regular standard business. Management did not disclose the customers, programme values or launch dates, saying detailed order-win information is commercially sensitive and closely tracked by competitors.
Know SPR Auto Technologies inside out
Results, valuation, peers and who's buying, in one view.
What is SPR Auto’s mature-year business-win figure?
SPR Auto’s stated figure is more than Rs 1,000 crore of incremental mature-year business across all its operations. Management described this as business won over and above its existing regular standard business, which it put at around Rs 6,000 crore. The comparison indicates that the new-program pipeline is incremental to the business volume management expects to maintain through regular operations.
Management did not identify the customers, products, individual programme values or execution dates behind the more-than-Rs-1,000-crore figure. It said the company normally avoids providing full order-win details because competitors closely track such programmes and disclosure could affect SPR Auto if a programme is disrupted. The disclosed amount is therefore an aggregate mature-year opportunity, rather than a programme-by-programme revenue schedule.
The additional mature-year wins are more than one-sixth of the around Rs 6,000 crore regular-business base cited by management. This is a comparison of business volumes at maturity, not a statement of current-period sales, profitability or a confirmed order-book conversion rate. SPR Auto said it was confident that all its businesses would grow, but did not provide a consolidated timeline for the incremental wins to reach mature-year volumes.
Which SPR Auto products could support new programmes?
SPR Auto said every business had won new programmes and customers, while withholding a detailed breakdown of the aggregate figure. In interiors, management said it had been nominated by many customers for future programmes, including electric vehicles. It also said it was working with at least two or three customers after providing proof of concepts for new headliner technologies, including Immersa Technologies-related work.
For speakerless acoustic headliners, management said realisation improvement versus conventional headliners with sunroofs can range from about 15% to 18% in a small car. In larger vehicles, depending on the required sound quality, it said the improvement could reach around 30% to 40%. These are management estimates that vary by vehicle design, including whether a vehicle has a minor or panoramic sunroof, rather than disclosed values of confirmed orders.
Ambient lighting is another interiors area where management said growth was faster than in its other interiors businesses. It said SPR Auto had won new customer programmes in lighting and was satisfied with the growth rate, but did not quantify either lighting revenue or its adoption rate. The company also referred to investments in precision plastics, motors and controllers, engine valves, pistons and interior products, showing that its capacity additions span several automotive-component categories.
The company outlined a slower outlook for the piston business after reporting 17% growth in its standalone business in the first half. Management said it expected the next two years to tone down toward a 7% to 8% compound annual growth rate, or CAGR, rather than sustaining growth of around 17% to 20%. That expectation reflected management’s view that the automotive market could grow at a 7% to 8% CAGR, while demand could continue across internal-combustion-engine, compressed-natural-gas and hybrid-CNG powertrains.
Got a follow-up? Ask IRIS
How is SPR Auto preparing capacity for the additional business?
SPR Auto said it is adding capacity ahead of expected market demand across several locations and businesses. Management cited expansion in Pithampur and Pathredi, an ongoing expansion in Ghaziabad, and a new plant next to its existing Neemrana facility for precision injection moulding. It also said it was investing in TGPEL and in interiors capacity across multiple Antolin product lines.
Management did not provide a rupee capex budget because it said the plan changes with continuing business discussions. It said SPR Auto was already considering another three or four decisions that could alter the capex plan, while describing the planned spending as sizable. The absence of a capex amount means the call did not establish the investment cost, commissioning timetable or return profile for the new capacity.
Working-capital management is part of the execution plan. SPR Auto said group and standalone working-capital levels remained normal despite higher manufacturing levels, but added that its precision-plastics business needs raw-material availability for at least three months of production. This inventory requirement is a specific supply-chain mechanism intended to support production continuity as new programmes ramp.
Commodity pass-through arrangements may also influence how new business affects reported margins. Management said raw-material impacts are normally covered 100% through back-to-back customer arrangements, generally with a one-quarter lag because of inventories and finished-goods stock. It said aluminium prices had begun to decline, while direct-material, tooling and die prices continued to face upward pressure linked to war-related conditions.
What could affect the conversion of SPR Auto’s wins into revenue?
SPR Auto’s disclosed Rs 1,000 crore figure is a mature-year measure, meaning revenue timing depends on programme launches, customer production schedules and capacity readiness. Management did not disclose a launch calendar for the aggregate wins or quantify how much of the opportunity relates to interiors, precision plastics, powertrain products or lighting. That leaves the timing of conversion into reported sales unresolved.
Capacity additions are being planned across Pithampur, Pathredi, Ghaziabad and Neemrana, but management did not provide commissioning dates. The company said it was adding capacity ahead of market demand and was considering three or four further capex decisions. Those decisions could change the size and timing of its investment plan as customer discussions progress.
Raw-material movements could also affect period-to-period financial results even where commercial arrangements provide recovery. Management said aluminium, copper, steel and plastics are used across different products, and recovery formulas vary by customer and value addition. A one-quarter lag between raw-material movements and customer pass-through means commodity changes may not be reflected immediately in reported results.
Conclusion
SPR Auto’s disclosure of more than Rs 1,000 crore in incremental mature-year wins points to a new-program pipeline alongside its around Rs 6,000 crore regular-business base. The call linked the opportunity to several areas, including interiors, headliners, lighting, precision plastics and legacy automotive products, but it did not provide a customer-wise or product-wise split of the aggregate figure.
The next items to watch are SPR Auto’s pending three or four capex decisions, progress at its Pithampur, Pathredi, Ghaziabad and Neemrana expansions, and any future disclosure on programme launch timing. Management’s expectation that growth will moderate toward a 7% to 8% CAGR over the next two years, rather than continue at around 17% to 20%, is also relevant to how the regular-business base and new wins develop together.