










Sunrakshakk: New Businesses Supply 90.7% of H1 Revenue
Key highlights
- Sunrakshakk reported H1 FY27 revenue of Rs 541.50 crore, up 119.93% year on year.
- FMCG, FMCG intermediates and edibles supplied approximately 90.7% of Sunrakshakk’s H1 FY27 revenue.
- Sunrakshakk’s H1 FY27 EBITDA rose 96.32% to Rs 45.73 crore and PAT rose 130.39% to Rs 31.04 crore.
- Sunrakshakk’s textile segment recorded a Q2 FY27 loss of Rs 97 lakh on revenue of Rs 24.25 crore.
powered by IRIS
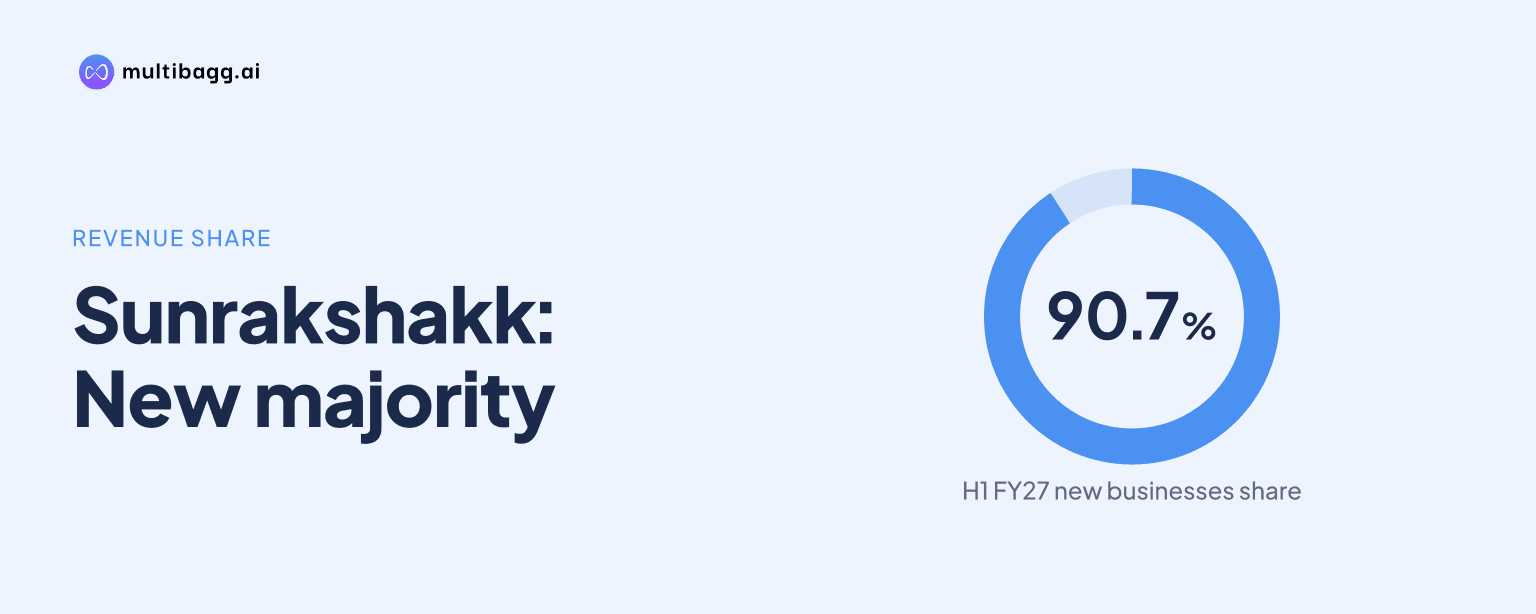
Sunrakshakk Industries India Limited said fast-moving consumer goods (FMCG), FMCG intermediates and edibles supplied approximately 90.7% of revenue in H1 FY27, as consolidated revenue from operations rose 119.93% year on year to Rs 541.50 crore for the half year ended September 30, 2026. The mix marks a substantial shift from the approximately 83% FMCG-led mix reported for FY26.
Know Sunrakshakk Industries India inside out
Results, valuation, peers and who's buying, in one view.
How much of Sunrakshakk’s H1 FY27 revenue came from newer businesses?
Sunrakshakk derived approximately 90.7% of H1 FY27 revenue from FMCG, FMCG intermediates and edibles, with textiles contributing the remaining approximately 9.3%. The newer-business share was close to the 90.6% reported in Q1 FY27 and 90.9% in Q2 FY27. It was higher than the approximately 83% FMCG-led revenue mix that management cited for FY26.
The FMCG segment, which management uses to include its FMCG intermediates and edibles activities, reported Rs 491.22 crore of revenue and Rs 42.71 crore of segment result in H1 FY27. That revenue is broadly consistent with the stated 90.7% contribution to consolidated H1 revenue of Rs 541.50 crore. During the November 17, 2026 call, an analyst said textiles had represented 100% of revenue in FY24, and management did not challenge that comparison.
What drove Sunrakshakk’s first-half revenue growth?
Sunrakshakk’s revenue from operations increased by Rs 295.29 crore year on year in H1 FY27, reaching Rs 541.50 crore from Rs 246.21 crore in H1 FY26. Q2 FY27 revenue was Rs 265.17 crore, up 119.20% from Rs 120.97 crore in Q2 FY26. Management attributed the expansion to the growing scale of FMCG, intermediate and edible activities, supported by manufacturing investments over recent quarters.
The quarterly trend was mixed because Q2 FY27 revenue of Rs 265.17 crore was 4.04% below Q1 FY27 revenue of Rs 276.33 crore. Management said lower home care and detergent sales, lower Guwahati soap-noodle revenue and modest moderation at Roorkee more than offset a 63.71% sequential increase in edibles revenue. The H1 increase therefore reflected rapid year-on-year expansion rather than uniform sequential growth across product lines.
Bhilwara’s edibles revenue rose to Rs 49.67 crore in Q2 from Rs 30.30 crore in Q1, while home care and detergent revenue at the same facility declined to Rs 27.14 crore from Rs 40.98 crore. Guwahati noodle-section revenue fell to Rs 30.35 crore from Rs 37.75 crore. At Roorkee, soap revenue declined to Rs 25.85 crore from Rs 27.50 crore and noodle revenue to Rs 82.74 crore from Rs 87.62 crore.
How did Sunrakshakk’s profits change in H1 FY27?
Sunrakshakk increased absolute earnings in H1 FY27, although its earnings before interest, tax, depreciation and amortisation (EBITDA) margin declined year on year. EBITDA rose 96.32% to Rs 45.73 crore from Rs 23.30 crore, while profit after tax (PAT) rose 130.39% to Rs 31.04 crore from Rs 13.47 crore. Basic earnings per share increased to Rs 10.01 from Rs 4.64.
The H1 EBITDA margin was 8.45%, compared with 9.46% in H1 FY26, while the PAT margin rose to 5.73% from 5.47%. In Q2, EBITDA margin was 8.73%, slightly below 8.81% in Q1 FY27 but below 9.65% in Q2 FY26. PAT margin rose sequentially to 6.03% from 5.44%, and management linked this to the raw-material-cost ratio declining to 74.37% of revenue from 75.60% in Q1.
Textiles remained loss-making at the segment level in Q2 FY27. The segment reported revenue of Rs 24.25 crore, down 7.53% year on year, and a segment loss of Rs 97 lakh. Management cited higher dyes and chemicals costs, and said installation of a machine also affected production during the quarter. Management expects raw-material and consumables volatility to settle in the current or following quarter, which is an expectation rather than a reported outcome.
Got a follow-up? Ask IRIS
What capacity supports Sunrakshakk’s FMCG expansion?
Sunrakshakk had aggregate installed capacity of approximately 20,840 tonnes a month across FMCG and FMCG intermediates after commissioning an additional soap production line at Roorkee in Q1 FY27. Roorkee makes soap, soap noodles and toothpaste; Bhilwara produces home care, detergent and edibles; and Guwahati produces soap noodles and cosmetics. Management said the three facilities serve more than 200 customers across categories.
Management reported utilisation of approximately 50% to 55% of current capacity. At Guwahati, it said both the soap-noodle and cosmetics sections were operating at about 50% utilisation, while it sought additional customers and saw higher demand from existing ones. Management said reaching 85% to 90% utilisation could take time, without providing a timetable.
Management also said it was in discussions with customers for the additional 1,700-tonnes-per-month soap line at Roorkee, with one or two discussions at a late stage. It expects the line to generate additional revenue by Q4 FY27. Soap and edibles were identified by management as the primary growth drivers, alongside priorities of higher utilisation, broader product portfolios and wider distribution.
What targets and risks has Sunrakshakk management disclosed?
Sunrakshakk management said H1 FY27 revenue of Rs 541.50 crore put the company ahead of the pace it had envisaged for its earlier aspiration of approximately Rs 1,000 crore in revenue by FY28. It said the Rs 1,000 crore benchmark could be reached sooner than the earlier timeline. Management also retained its stated revenue compound annual growth rate target of 30% to 35% between FY25 and FY29, without issuing a specific FY27 revenue forecast.
On profitability, management told an analyst it was targeting a 7% level by FY28, without specifying the profit measure on the call. It cited volatile crude-linked inputs, including linear alkylbenzene sulphonic acid and palm-linked materials, as a near-term issue. Management said procurement discipline, product mix and utilisation could help margins normalise progressively, while working-capital management would remain a priority as revenue expands.
Conclusion
Sunrakshakk’s H1 FY27 results show that FMCG, intermediates and edibles have become its main revenue base, supplying approximately 90.7% of sales as revenue reached Rs 541.50 crore. This scale lifted H1 EBITDA to Rs 45.73 crore and PAT to Rs 31.04 crore, although the EBITDA margin of 8.45% was below the 9.46% recorded a year earlier and textiles made a Q2 segment loss of Rs 97 lakh.
The next disclosed milestones are additional revenue from the 1,700-tonnes-per-month Roorkee soap line by Q4 FY27, if customer discussions convert, and higher utilisation from the current 50% to 55% range. Management’s stated aspiration remains approximately Rs 1,000 crore of revenue by FY28, potentially sooner, while input-cost volatility and the recovery of textile profitability remain unresolved matters to watch.