










Surya Roshni sees steel EBITDA per tonne above Rs 5,000
Key highlights
- Steel Pipes and Strips EBITDA per tonne was Rs 4,105 in Q2 FY27, versus Rs 4,006 in Q1 FY27 and Rs 5,013 in Q2 FY26.
- Surya Roshni expects steel EBITDA per tonne of Rs 4,800 to Rs 4,900 in Q3 FY27 and above Rs 5,000 in Q4 FY27.
- Steel Pipes and Strips volume reached 2.67 lakh tonnes in Q2 FY27, up 23% year on year.
- The steel order book was about Rs 1,200 crore, including 80,000 tonnes of API export pipes for Q3 and Q4 FY27.
powered by IRIS
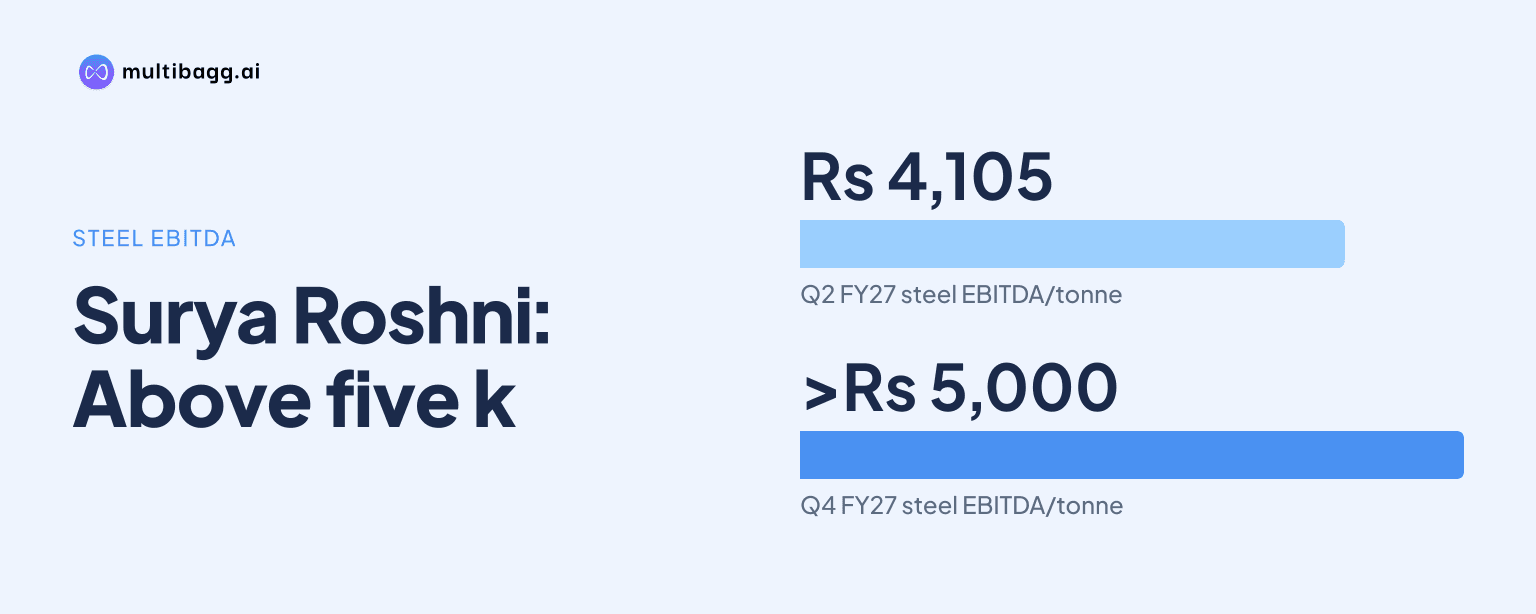
Surya Roshni Limited expects Steel Pipes and Strips EBITDA, or earnings before interest, tax, depreciation and amortisation, to exceed Rs 5,000 per tonne in Q4 FY27, following Rs 4,105 per tonne in Q2 FY27. Management attributed the first-half shortfall to higher sea freight and delayed price pass-through on fixed-price export and API pipe orders.
Know Surya Roshni inside out
Results, valuation, peers and who's buying, in one view.
What is Surya Roshni's steel EBITDA outlook for Q3 and Q4 FY27?
Surya Roshni expects Steel Pipes and Strips EBITDA per tonne of Rs 4,800 to Rs 4,900 in Q3 FY27 and more than Rs 5,000 in Q4 FY27. Management said around Rs 5,000 per tonne is the sustainable level and indicated that the full-year outcome should remain around that level.
The projected recovery follows a modest sequential rise from Rs 4,006 per tonne in Q1 FY27 to Rs 4,105 in Q2 FY27. However, Q2 FY27 EBITDA per tonne remained Rs 908 below the Rs 5,013 reported in Q2 FY26, meaning the Q4 target would take the metric above the year-earlier quarterly result.
Management did not describe the Rs 4,000 to Rs 4,500 range as a new normal when an analyst raised that possibility after the first half. Instead, it pointed to the Q1-to-Q2 increase and the expected benefit from price increases in the second half of fiscal year 2027, or FY27.
How did Surya Roshni's steel-pipe business perform in Q2 FY27?
Surya Roshni's Steel Pipes and Strips segment recorded volume of 2.67 lakh tonnes in Q2 FY27, up 23% year on year and 17% sequentially. Revenue rose 38% year on year to Rs 1,941 crore, while segment EBITDA increased 1% to Rs 103 crore.
The gap between revenue growth and EBITDA growth reflected in the per-tonne result. Although quarterly EBITDA per tonne rose Rs 99 from Q1 FY27, it was lower than the Rs 5,013 per tonne reported in Q2 FY26; volume growth was therefore not matched by a comparable year-on-year increase in unit profitability.
For H1 FY27, or the first half of FY27, the segment sold 4.96 lakh tonnes, 22% more than a year earlier, and generated revenue of Rs 3,531 crore, up 35%. H1 EBITDA per tonne was Rs 4,059, compared with Rs 4,037 in H1 FY26, while EBITDA rose 22% to Rs 188 crore.
Got a follow-up? Ask IRIS
What held back Surya Roshni's first-half steel margins?
Surya Roshni said sea freight increased by about Rs 1,700 per tonne, directly affecting steel profitability in Q2 FY27. Management also said its export and API pipe business operates on fixed prices, unlike trade sales where increases in steel prices are passed on automatically.
Steel prices began rising from August, which management said led distributors to restock and helped raise sales of hollow sections by about 35% in Q2 FY27. The benefit of the higher prices is expected to reach trade sales more quickly than fixed-price export and API contracts, which is the mechanism cited for the expected Q3 improvement.
Exports increased 64% year on year to about 65,000 tonnes in Q2 FY27, and United States volumes more than doubled sequentially. Value-added products accounted for about 48% of total steel volume, while the export mix exposed a larger share of sales to the contract-pricing timing that management identified.
What supports Surya Roshni's second-half steel plan?
Surya Roshni expects about 6 lakh tonnes of Steel Pipes and Strips volume in H2 FY27 after delivering 4.96 lakh tonnes in H1 FY27. Management said this would take full-year volume above its 11 lakh-tonne target, with exports representing 22% to 25% of FY27 volume.
The segment entered H2 FY27 with an order book of about Rs 1,200 crore, including export orders of about 1 lakh tonnes worth Rs 850 crore. About 80,000 tonnes of those export orders were API pipes scheduled for execution in Q3 and Q4 FY27, while domestic API orders had reached about 20,000 tonnes after oil-and-gas tendering revived.
For FY28, management targets steel volume of about 14 lakh tonnes and EBITDA per tonne of Rs 4,600 to Rs 4,800. That FY28 range is below the Q4 FY27 expectation of above Rs 5,000 per tonne, showing that management's stated longer-term planning assumption differs from its near-term fourth-quarter forecast.
Conclusion
Surya Roshni's Q2 FY27 steel results combined record volume of 2.67 lakh tonnes and revenue growth of 38% with EBITDA per tonne of Rs 4,105, below the Rs 5,013 recorded in Q2 FY26. Management's case for a second-half recovery rests on price pass-through, easing timing effects in fixed-price export and API work, and execution of its existing order book.
The next measure to watch is Q3 FY27 EBITDA per tonne against management's Rs 4,800 to Rs 4,900 forecast, followed by its expectation of above Rs 5,000 in Q4 FY27. Management also plans Rs 150 crore to Rs 155 crore of FY27 capital expenditure, with projects at Bhuj, Bahadurgarh, Gwalior and Hindupur expected to be commissioned by March FY27.